


Beta Bionics has seen its share price fall sharply this year, and that slide puts fresh focus on whether the current valuation is still supported by its sales base. With the stock under pressure and legal challenges in the background, investors are increasingly asking how much revenue power the business really has relative to what the market is paying for it.
- The share price is down 42.7% year to date, which raises the question of whether the current market value has moved out of line with the scale and trajectory of Beta Bionics' sales.
- Multiple securities class action lawsuits tied to alleged FDA violations and missed product expectations can influence how investors think about future sales growth, margins and the timing of any scale benefits in Beta Bionics' revenue model.
- There is a second opinion on Beta Bionics worth weighing. See what analysts think Beta Bionics's shares could be worth.
The issue now is whether Beta Bionics' current share price is adequately supported by the sales it generates today and what investors reasonably expect it to produce over time.
If you are weighing Beta Bionics against other potential ideas on this theme, it can help to compare it with 30 resilient stocks with low risk scores.
Has Beta Bionics Run Too Far on Sales?
P/S fits Beta Bionics because the market is mainly weighing what it pays for each dollar of current revenue rather than profits that are still negative.
On that yardstick, the stock trades at a P/S of 7.2x, compared with about 2.7x for the wider Medical Equipment industry and roughly 6.5x for closer peers. The gap shows investors are paying a richer tag for Beta Bionics' top line than for many other device makers, even though the business is still working through legal and regulatory issues around the iLet Bionic Pancreas.
The fair multiple implied by the valuation model, which blends the company’s growth profile, risk and size, sits below the current P/S level, so the shares screen overvalued on this framework. Because the recent lawsuits highlight uncertainty around product quality, disclosure and future demand, that premium P/S asks investors to accept a lot of execution and legal risk for each dollar of sales. Explore the numbers behind Beta Bionics's P/S valuation.
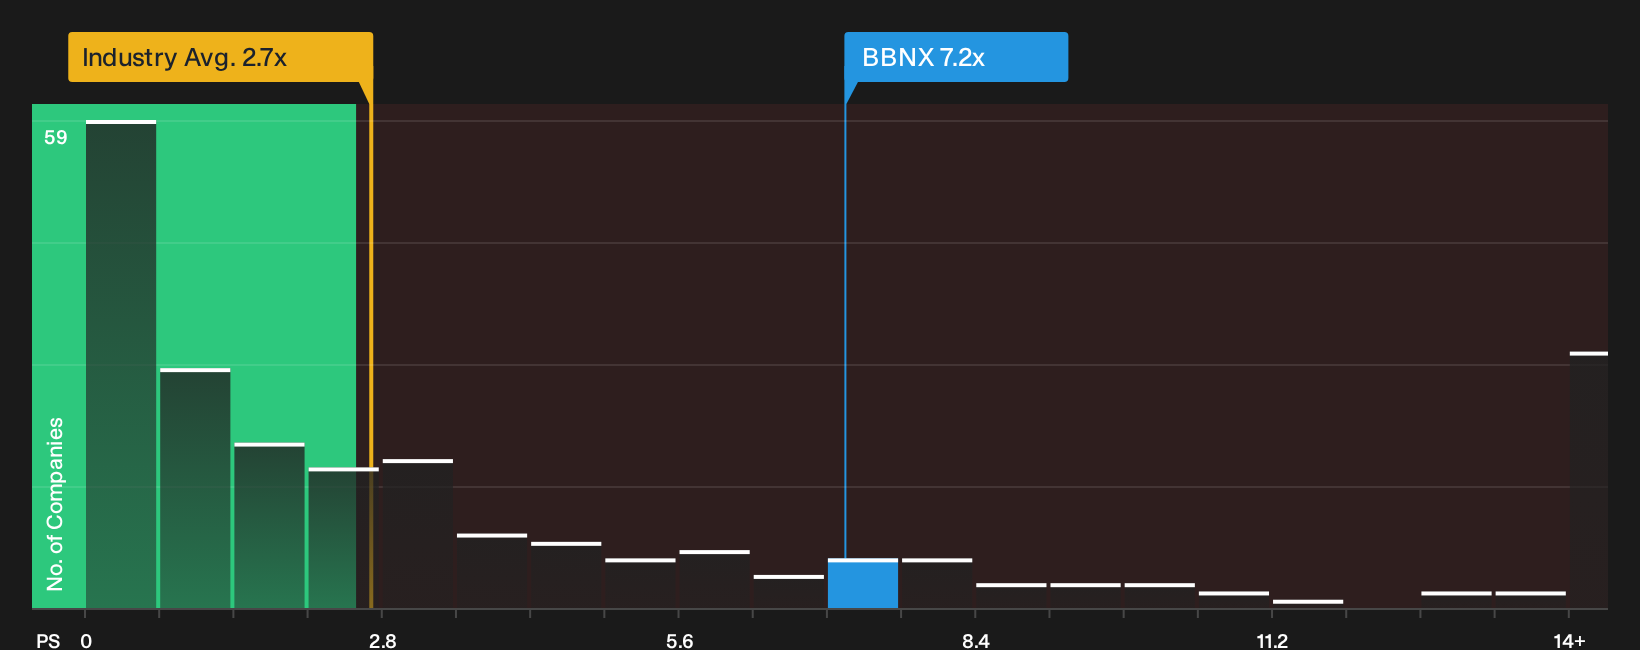
The Beta Bionics Narrative: What Would Justify Today's Price?
Beta Bionics' valuation puzzle sets up the role of Simply Wall St Narratives. These spell out what growth, margin and earnings paths would need to play out for the stock to be priced meaningfully above or below where it trades today, and present each scenario as a thesis about the business that can be revisited over time. These sit on Simply Wall St's Community page and are designed to be tracked as new information comes through.
Bull and bear voices on Beta Bionics are working off the same products and FDA backdrop, yet they see very different payoff potential.
Bull case: 30% undervalued
"Rapid expansion of the iLet installed base, particularly from multiple daily injection converts and underpenetrated type 2 diabetes patients, is creating a larger pool of high-visibility, recurring supply revenue..."
Discover why this Narrative puts Beta Bionics at 30% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect Beta Bionics to struggle with the operational and legal fallout from the FDA warning letter, elevated operating expenses, and questions around its 3D Intelligence algorithm timeline..."
Explore why this Narrative puts Beta Bionics at roughly fairly valued.
One more piece to consider before acting on Beta Bionics' valuation
Price tags tell one story, but the projections that analysts map out for Beta Bionics over the next few years offer a separate lens to compare with where the stock trades today. Explore where analysts expect Beta Bionics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com