


AI giants are pouring an estimated $828b this year into data centers and chips, and that rush for computing power is forcing investors to look harder at where genuine growth might come from next. Fast growing Indian businesses where founders still own a big slice can offer a different kind of story, tied closely to on the ground execution. This article highlights three such high growth, high insider ownership stocks from our screener.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders share the upside alongside you. However, if you want the absolute best, these 40 high growth high conviction stocks are the cream of the crop.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research is a specialty pharmaceutical business that develops complex, higher value therapies using proprietary drug delivery platforms across multiple treatment areas.
Operations: Rubicon Research generates ₹19,358 million in revenue from pharmaceutical products, specialty formulations, APIs, and related services.
Market Cap: ₹266.6 billion
Rubicon Research fits this fast growing, high insider ownership theme because its own drug delivery platforms give management multiple opportunities to scale new specialty products and license income over time.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a track record of commercialising 88% of approved products, is cited as supporting a deeper product basket that may help underpin revenue and earnings visibility."
One key consideration from here is how any pressure on future pricing and mix ultimately feeds through to margins and earnings quality.
That margin question is only the starting point, and the full narrative for Rubicon Research shows how Rubicon Research’s product mix, capital allocation, and insider alignment could accelerate or stall from here.

Tonbo Imaging India (NSEI:TONBO)
Overview: Tonbo Imaging India builds electro-optical and infrared defense vision systems, including AI-accelerated thermal sights and missile guidance platforms for global security customers.
Market Cap: ₹74.7 billion
Tonbo Imaging India appeals to this high growth, high insider ownership theme because analysts expect earnings to rise 53.36% a year and revenue 33.2% a year. However, margins are under pressure, and a premium 22.6x P/S means a shift in one unseen pressure could matter a lot for future returns.
That premium only matters if the growth shows up, so check the analyst forecasts for Tonbo Imaging India to see whether the current multiple matches the earnings story investors are betting on.

Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects delivers turnkey EPC solutions for high voltage power transmission and distribution, including substations, transmission lines, poles, and galvanizing services.
Operations: Bajel Projects generates approximately ₹27,508 million in revenue from power transmission and power distribution EPC projects and related products.
Market Cap: ₹18.6 billion
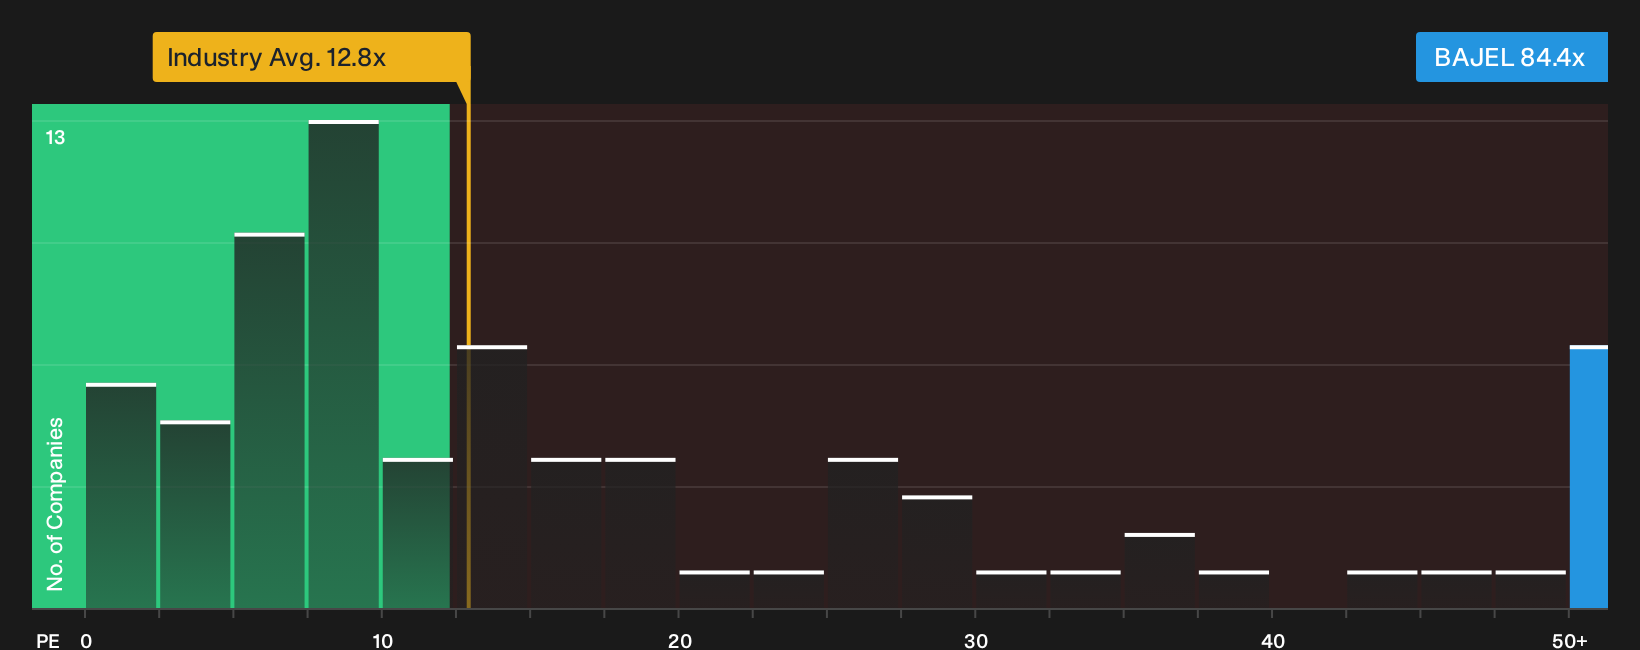
Bajel Projects fits into this theme of high insider ownership and large scale grid build out and upgrade work. Recent earnings growth of 71% and a forecast 57.7% yearly earnings rise are being compared with a P/E ratio of 84.4, which may be sensitive to changes in key underlying assumptions.
Those assumptions are exactly what you need to test with the 2 key rewards and 1 important warning sign before you determine whether Bajel Projects’ rich multiple supports or challenges your thesis.
Seeking Alternatives Before Momentum Builds
Fresh opportunities can move quickly, and once momentum appears, the most accessible entry points may narrow. Consider scanning these ideas that are still relatively under the radar and decide whether they fit your approach.
- Explore resilient compounding potential by reviewing companies in the 216 resilient stocks with low risk scores while they still trade before broader attention increases.
- Look for underappreciated upside across the 603 high quality undiscovered gems before these quieter stories attract more interest and pricing becomes less flexible.
- Assess long-term income trends by reviewing the 224 dividend fortresses while yields remain elevated and prices do not yet fully reflect their cash flow profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com