


Rayonier (RYN) has drawn fresh attention after a recent move in its share price. The timber-focused REIT is now trading at US$19.38 and has shown mixed returns over the past month and the last three months.
Recent trading has brought a short burst of momentum, with Rayonier’s 7-day share price return of 3.91% and 30-day share price return of 5.56% partly offsetting a 90-day share price decline of 11.02% and a 1-year total shareholder return that is down 7.63%.
Scan how Rayonier compares with other real estate and timber-focused businesses by running the list of solid balance sheet and fundamentals (25 results) while this move in the share price is still fresh.
Rayonier’s recent bounce has reopened a bigger question. With the stock at US$19.38 and fair value estimates clustered much higher, how wide is the gap between today’s price and what the assets suggest it is worth?
Most Popular Narrative: 18% Undervalued
At a last close of $19.38, the most followed narrative pegs Rayonier’s fair value closer to $23.67, which suggests a sizeable valuation gap built on long term timber, real estate and land-based income assumptions.
Continued conversion of Southern timberland into rural HBU sales and larger development projects such as Wildlight, Heartwood and Chenal, where management points to 50 to 100% premiums on recent rural tracts and the potential for 10 to 15 times higher values on development acres, has scope to lift real estate revenue and segment margins as more acres are brought to market.
See why 21 investors see Rayonier as 18% undervalued.
Result: Fair Value of $23.67 (UNDERVALUED)
Still, Rayonier’s story could be knocked off course if timber pricing pressure lingers in the U.S. South or if lumpy real estate deal flow slows materially.
Find out about the key risks to this Rayonier narrative.
Another View: Rayonier Through The P/E Lens
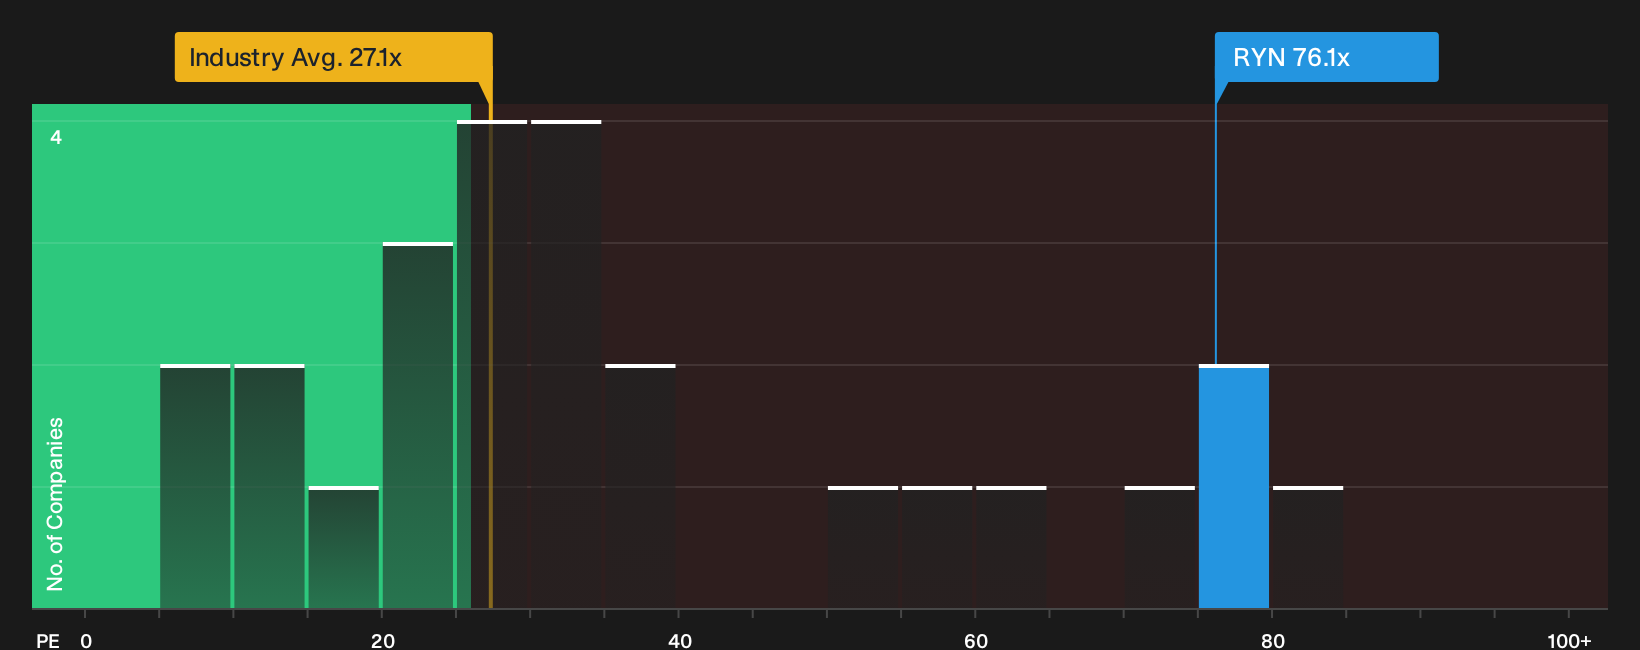
Rayonier may appear inexpensive on certain fair value models, yet its current P/E ratio of 76.1x is significantly higher than the North American Specialized REITs average of 27.2x and its own fair ratio of 64.5x. That premium raises a straightforward question for investors: is the apparent discount to fair value worth paying such a high multiple?
Before relying on that earnings multiple, it is worth stress testing the assumptions and evaluating what the numbers imply for risk using See what the numbers say about this price — find out in our valuation breakdown..
Place Rayonier’s valuation in context next to sector peers and its own history with
Next Steps
Mixed signals on Rayonier so far. If this debate around value and risk matters to you, consider acting promptly and review the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Rayonier?
If Rayonier has you thinking harder about value and risk, do not stop here. Let the data surface other opportunities before the rest of the market catches on.
- Target resilient balance sheets and steadier financial profiles by scanning the 30 resilient stocks with low risk scores that fit your comfort with volatility.
- Hunt for quality at a discount by reviewing the 29 high quality undervalued stocks that pair solid fundamentals with pricing that still looks reasonable.
- Build a watchlist of differentiated opportunities by checking the 18 high quality undiscovered gems that meet strict filters on financial strength and potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com