


Hesai Group (HSAI) is back in focus after an industry report ranked it as the top robotaxi lidar supplier worldwide, with a reported 62% share of the 2025 global robotaxi lidar market.
Hesai Group’s recognition in robotaxi lidar comes against a tougher tape for the stock, with the share price down 23.6% over the past month and 49.4% year to date, while the 3 year total shareholder return of 11.9% suggests that much earlier optimism is now giving way to fading momentum.
Seize the momentum in autonomous driving by scanning 95 robotics and automation stocks, which, like Hesai Group, are supplying the hardware behind next generation robotaxis and automation platforms.Hesai Group now pairs a sharp pullback with fresh industry validation, which presents a practical fork in the road for investors who care about price: lean in after this drop or wait for the valuation to reset further?
Most Popular Narrative: 54% Undervalued
Hesai Group closed at $12.18 while the most followed valuation narrative points to a fair value of $26.64, so the story hinges on whether the business can live up to the growth and profitability embedded in that gap.
The growth of the ADAS market and LiDAR adoption in EVs is expected to rise from 8% in 2023 to 20% in 2025 and 56% by 2030, potentially increasing future revenue and market share.
Expanding into the global market with new design wins, including a top European OEM, highlights the company's growing international presence and potential revenue diversification.
See why 34 investors see Hesai Group as 54% undervalued.
The prevailing narrative applies a 9.25% discount rate and arrives at a fair value of $26.64, which is well above both the last close and the analysts’ discounted cash flow value of $19.90. That spread reflects higher conviction in long term ADAS and robotics demand, as well as an assumption that Hesai Group can sustain firmer profit margins over time.
At the same time, the same storyline flags real pressure points around pricing, customer concentration and execution against multi million unit shipment goals. This means the implied 29.3x future P/E multiple needs consistent delivery on those forecasts. If you think those growth, margin and discount rate assumptions are too aggressive, then the gap between $12.18, $19.90 and $26.64 narrows quickly on your own worksheet.
Result: Fair Value of $26.64 (UNDERVALUED)
Still, the entire narrative can unravel quickly if LiDAR pricing pressure compresses margins, or if key customers like BYD or Li Auto reduce orders.
Find out about the key risks to this Hesai Group narrative.
Another View: What Multiples Say About Hesai Group
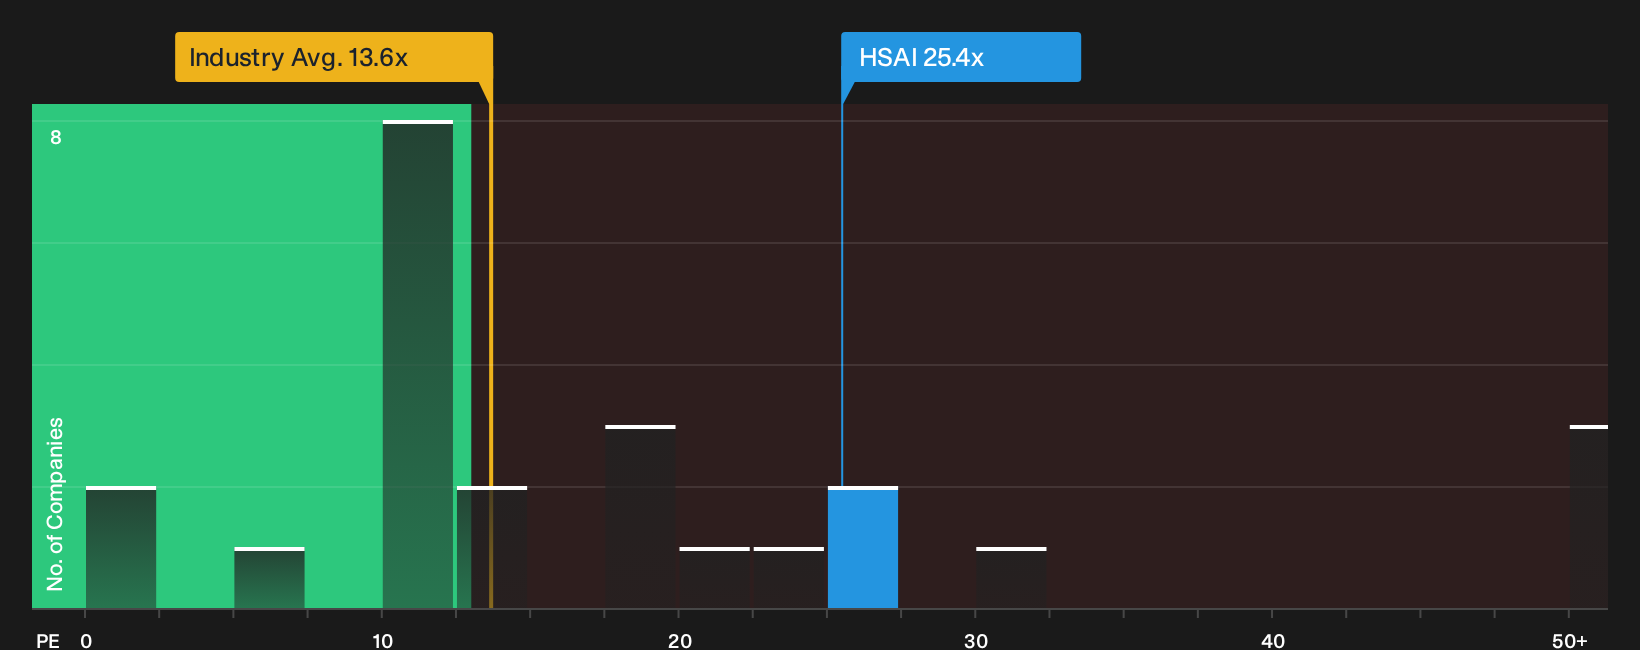
The first narrative leans heavily on future cash flows and discounted assumptions. A simpler yardstick, the current P/E, tells a different story. Hesai Group trades on 25.4x earnings versus 13.6x for the US Auto Components industry and 13.4x for peers, while its fair ratio is 29.7x.
That mix implies the stock is expensive against today’s sector and peer pricing, yet still below where the fair ratio suggests the market could move. For you as an investor, the question is whether that gap reflects genuine upside or just extra valuation risk if the growth narrative softens.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Hesai Group story can be confusing. Move quickly, review the underlying data, and weigh both 3 key rewards and 1 important warning sign.
Looking for more Hesai Group sized investment ideas?
If you only stop at Hesai Group, you miss a wider set of opportunities. Use the screener to quickly surface fresh ideas that fit your style.
- Target resilient performers by reviewing a 30 resilient stocks with low risk scores that aims to hold up when conditions get choppy and sentiment turns cautious.
- Hunt for mispriced potential with a 18 high quality undiscovered gems that have strong fundamentals but limited attention from the broader market.
- Focus on balance sheet strength by scanning a list of solid balance sheet and fundamentals (25 results) that can support reinvestment plans and future shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com