


- NBT Bancorp reported third quarter 2026 net interest income of US$142.08 million and net income of US$58.03 million, with basic earnings per share from continuing operations at US$1.12.
- Management paired higher profitability with a US$0.40 quarterly dividend and a fourteenth straight year of annual dividend increases, which indicates an emphasis on consistent capital returns alongside core banking earnings.
- This article examines how NBT Bancorp's investment narrative is influenced by stronger Q3 earnings together with the latest dividend increase.
Scan how NBT Bancorp’s earnings strength and dividend track record compare with other resilient financials on our hand picked list of 30 resilient stocks with low risk scores.
NBT Bancorp Investment Narrative Recap
NBT Bancorp appeals most if you think its core banking, fee businesses and regional expansion can keep supporting steady earnings while credit quality holds up. The latest quarter points to that story still being intact, with higher net interest income and fee contributions helping basic EPS from continuing operations reach US$1.12 in Q3 2026.
The short term swing factor is how loan demand and deposit costs behave as management leans into continued loan growth and digital channels. The biggest watchpoint remains concentration in upstate New York and nearby markets. Any slowdown in those local economies could pressure loan volumes and fee income.
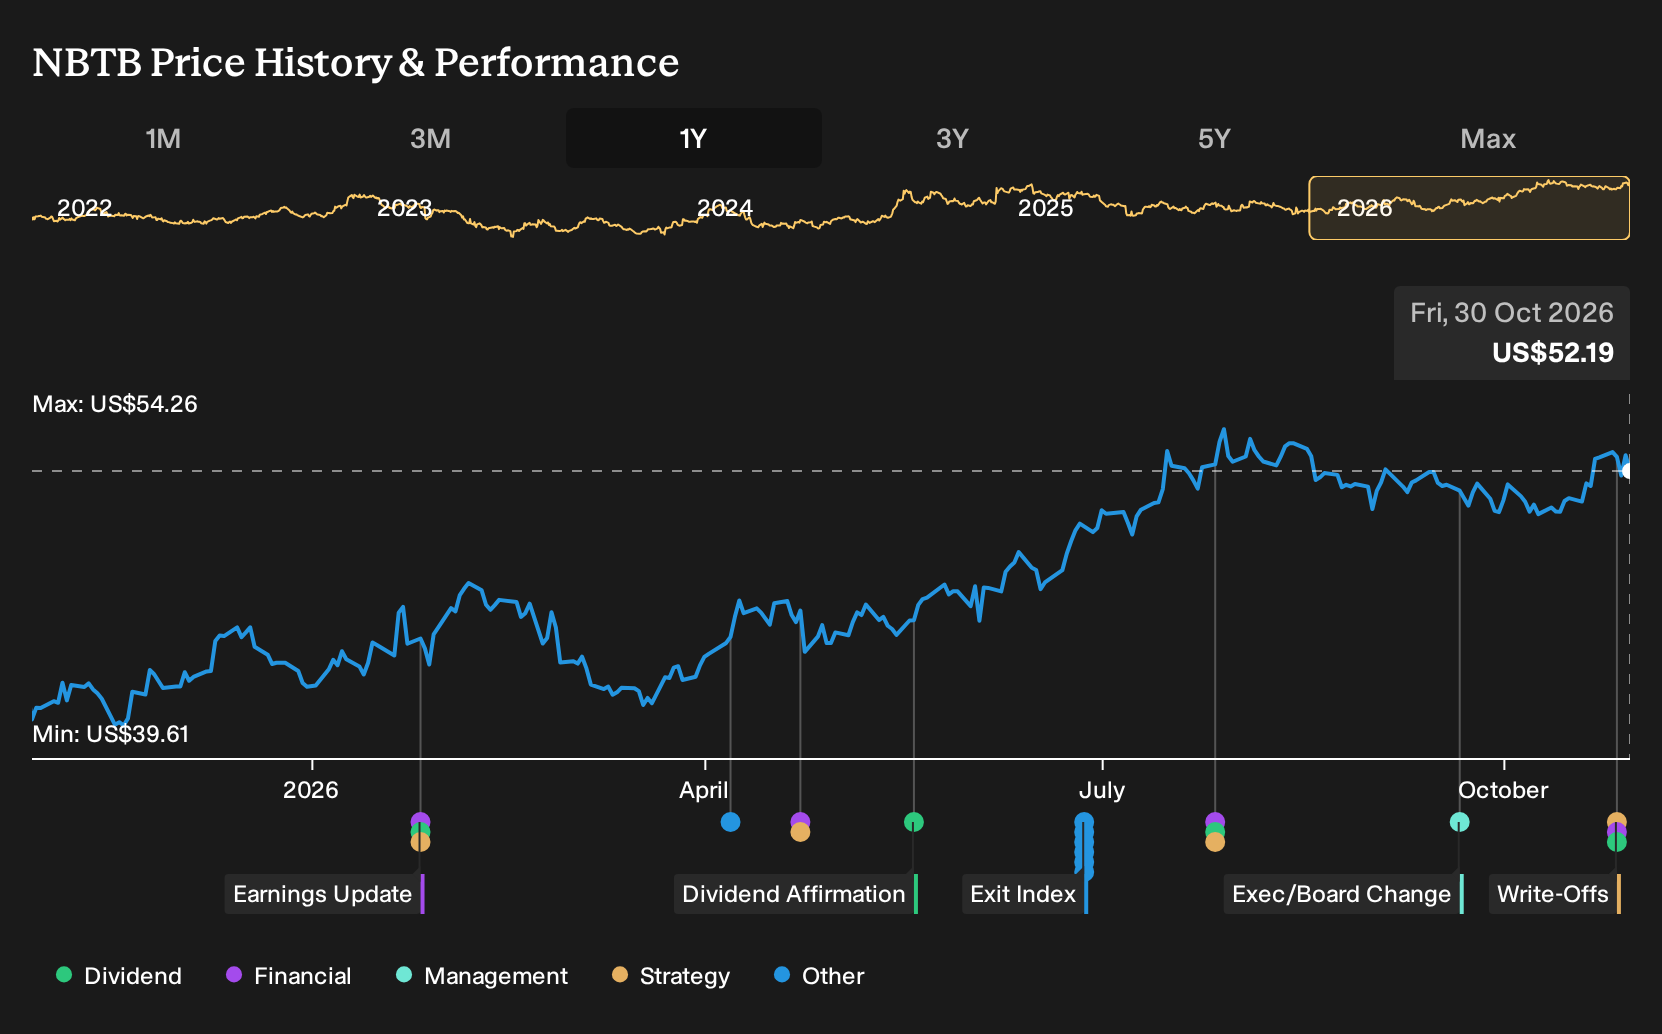
The dividend announcement is the clearest signal from this set of updates. NBT Bancorp’s Board approved a US$0.40 per share cash dividend for Q4 2026, an 8.1% increase on the payout made in Q3 2025, and extended a fourteen year run of annual dividend raises.
For investors, that ties directly into the core thesis and risks. Consistent capital returns depend on earnings staying healthy across traditional lending, newer Western New York operations and fee driven lines such as wealth and insurance. Any hit to those engines, or to funding costs, would make that long dividend streak harder to sustain over time.
NBT Bancorp’s current analyst narrative points to revenues of US$891.4 million and earnings of US$269.0 million by 2029, built on an assumed 7.2% yearly revenue growth rate and an earnings increase of about US$54.8 million from US$214.2 million today.
Uncover why NBT Bancorp's fair value indicates a 9% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Fair value estimates for NBT Bancorp from 2 private investors in the Simply Wall St Community span roughly US$56.83 to US$88.60, so you see both cautious and optimistic takes side by side. Set that against concentration risk in upstate New York and Buffalo, and the Micron related build out that could reshape loan demand over several years. Exploring multiple viewpoints helps you test your own assumptions before deciding how NBT Bancorp fits into your portfolio.
Explore another NBT Bancorp fair value estimate, including one that suggests potential upside of up to 70% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NBT Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for NBT Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NBT Bancorp's overall financial health at a glance.
Looking For More Ideas Beyond NBT Bancorp?
If you want to pressure test your view on NBT Bancorp, it helps to line it up against other companies with different income profiles, balance sheets and payout habits. The Simply Wall St Screener lets you move from this single stock to broader shortlists that match the kind of risk, income or quality mix you are actually looking for.
- For investors who want income and staying power together, scan a curated set of higher yield payers that aim to combine distributions with resilience through 5 dividend fortresses.
- If quality at a reasonable entry point is your priority, compare NBT Bancorp with other financially solid businesses trading below their estimated worth by reviewing 29 high quality undervalued stocks.
- When capital protection comes first, stress test your portfolio ideas against companies that score well on financial strength and risk metrics using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com