


- Elis reported Q3 2026 revenue of €1,323.9 million, up 6.1% on a reported basis, supported by organic activity, acquisitions, and currency effects, and confirmed all 2026 financial targets despite softer Latin American momentum linked to Mexico.
- The group highlighted that European contract rollouts are helping offset slower Latin American organic trends. Management still anticipates slightly higher adjusted EBITDA and EBIT margins and mid single digit free cash flow growth for the full year.
- We will look at how Elis's confirmed 2026 financial targets, backed by recent revenue performance, influence the existing investment narrative.
Scan how Elis compares to peers riding similar momentum and filter for companies with resilient balance sheets and cash generation using our curated list of solid balance sheet and fundamentals (200 results).
Elis Investment Narrative Recap
To be a shareholder in Elis, you need to believe the outsourced linen and workwear model can keep turning multi year contracts into steady cash generation while margins hold up. The latest Q3 update, with 6.1% reported revenue growth and confirmed 2026 targets, supports that view and keeps the main short term catalyst intact. That catalyst is execution on large European contract rollouts, which are currently offsetting weaker Latin American momentum.
The biggest risk still sits in Latin America. Wage inflation, the earlier Mexican healthcare tender loss, and any further contract changes could pressure regional profitability. Q3 did not remove that concern. It showed that Mexico related softness is manageable for now because Europe is doing more of the heavy lifting, but the sensitivity of margins to future tenders and regulation remains the key watchpoint.
The confirmation that Elis expects slightly higher adjusted EBITDA and EBIT margins, mid single digit free cash flow growth, and high single digit growth in diluted current net income per share for 2026 is the announcement that matters most here. Those goals frame what you are really underwriting: a business that can compound earnings from a large installed base while funding bolt on deals and keeping leverage in check.
For catalysts, those margin and earnings objectives tie back directly to contract ramp up, especially in European healthcare and workwear, and to efficiency measures such as energy savings. If Elis delivers on operational productivity while avoiding further major contract losses in Latin America, the story remains one of gradual earnings progression supported by a broad client footprint rather than big swings in any single market.
Elis' current analyst narrative points to revenue of €5.6b and earnings of €465.3m by 2029, which implies 4.6% yearly revenue growth and an earnings increase of about €87.5m from €377.8m.
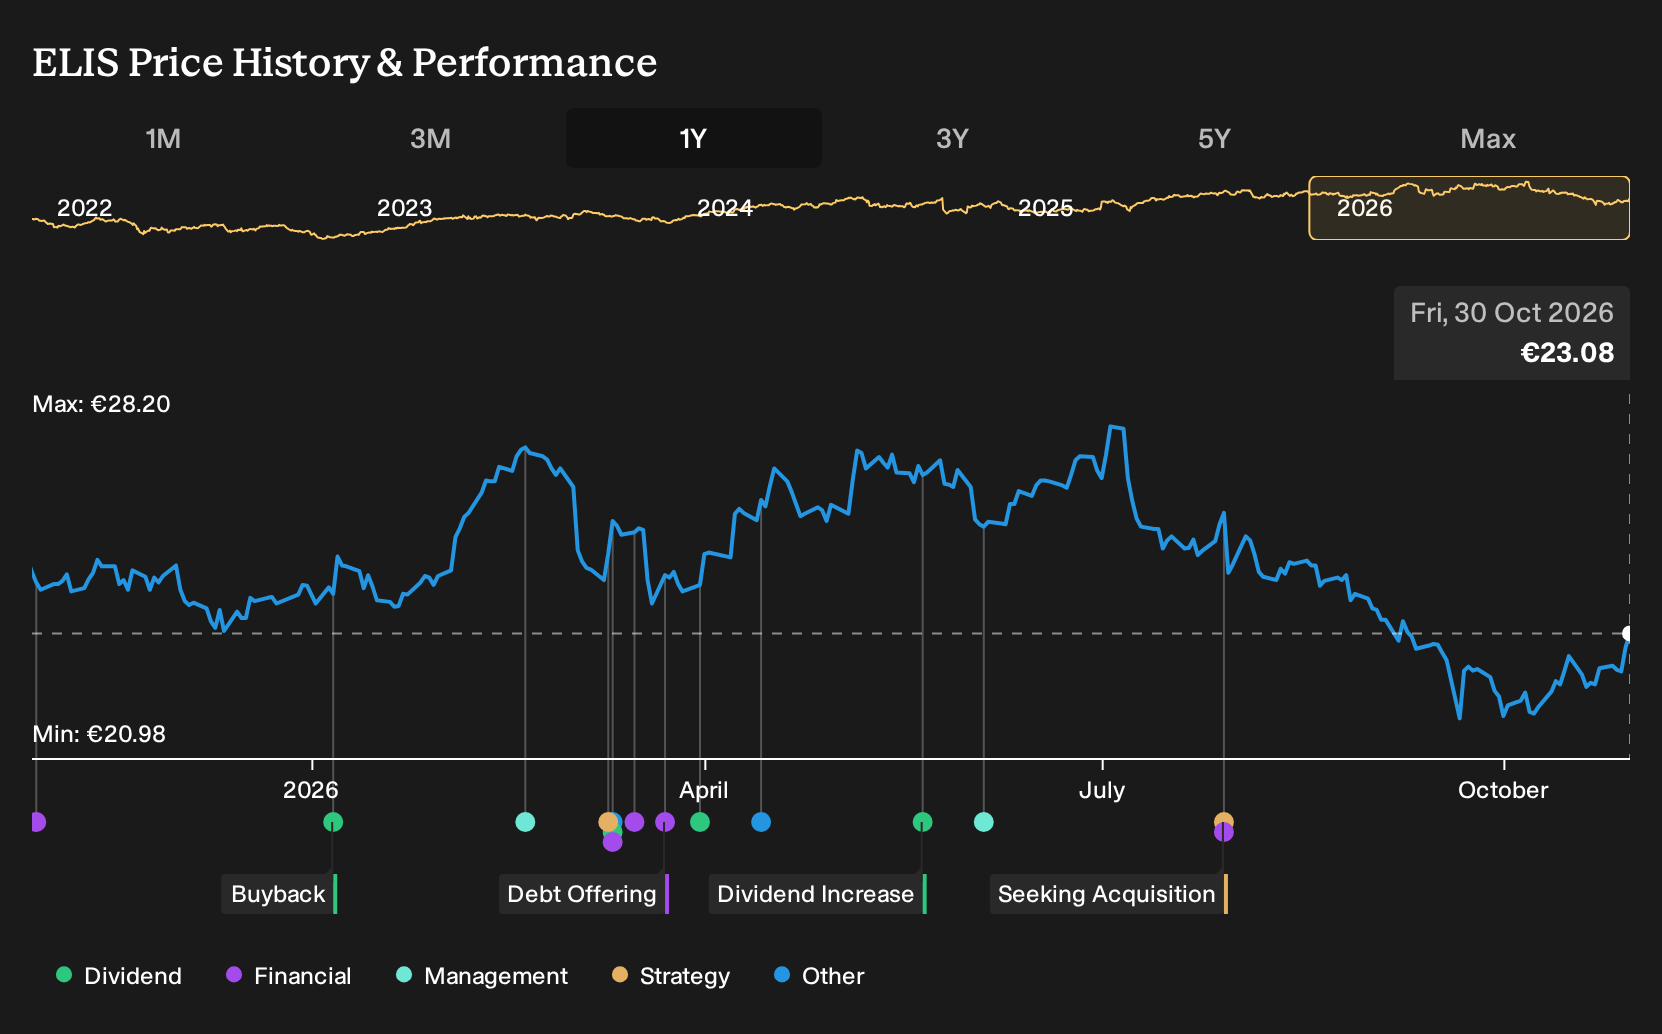
Uncover why Elis' fair value indicates a 30% potential upside to its current price. This gap could narrow quickly as expectations reset.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly €30 to €46 per share, which shows that retail views on Elis are far from aligned. That spread comes against a backdrop of Latin American margin risk and new European outsourcing contracts, so it is worth comparing several opinions before relying too heavily on any single valuation.
Explore another Elis fair value estimate, including one that suggests it could be worth just €29.96!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Elis research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Elis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elis' overall financial health at a glance.
Looking For More Ideas Beyond Elis?
If you want to stress test your view on Elis against what else is out there, the Simply Wall St Screener is a fast way to spot other businesses with balance sheet strength, dependable cash generation, or very different risk profiles.
- If you prefer resilience over drama and want businesses with fewer financial red flags, then start with a 216 resilient stocks with low risk scores that might fit a more cautious style.
- If you are hunting for strong cash flows and robust finances at prices that do not look stretched, check out a 194 high quality undervalued stocks that could sit alongside or compete with Elis in your watchlist.
- If you are looking for ideas that most investors may be overlooking but still have solid fundamentals, scan through a 602 high quality undiscovered gems that might offer a different angle to Elis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com