


BeOne Medicines stock has delivered a powerful 3 year run, so the natural question now is whether the current price is still justified by the earnings that support it. With oncology trial headlines drawing fresh attention, investors are asking what they are really paying for in terms of profit power today.
- Over the past 3 years, BeOne Medicines has returned about 101.3%. That raises the stakes on whether its earnings now back up that kind of share price reset.
- Recent oncology data around the TEVIMBRA and ZIIHERA combination and other solid tumor programs can shape expectations for future profitability, since success in these areas may influence how much earnings power investors build into the current valuation.
- The analysts covering BeOne Medicines have run their own numbers. See what analysts think BeOne Medicines's shares could be worth.
The issue now is whether BeOne Medicines' current share price around US$370 is well supported by its earnings when weighed against the Fair Ratio benchmark.
If you are weighing BeOne Medicines against other oncology-focused opportunities, consider comparing it with companies screened as 34 healthcare AI stocks.
Does BeOne Medicines Look Pricey on Earnings?
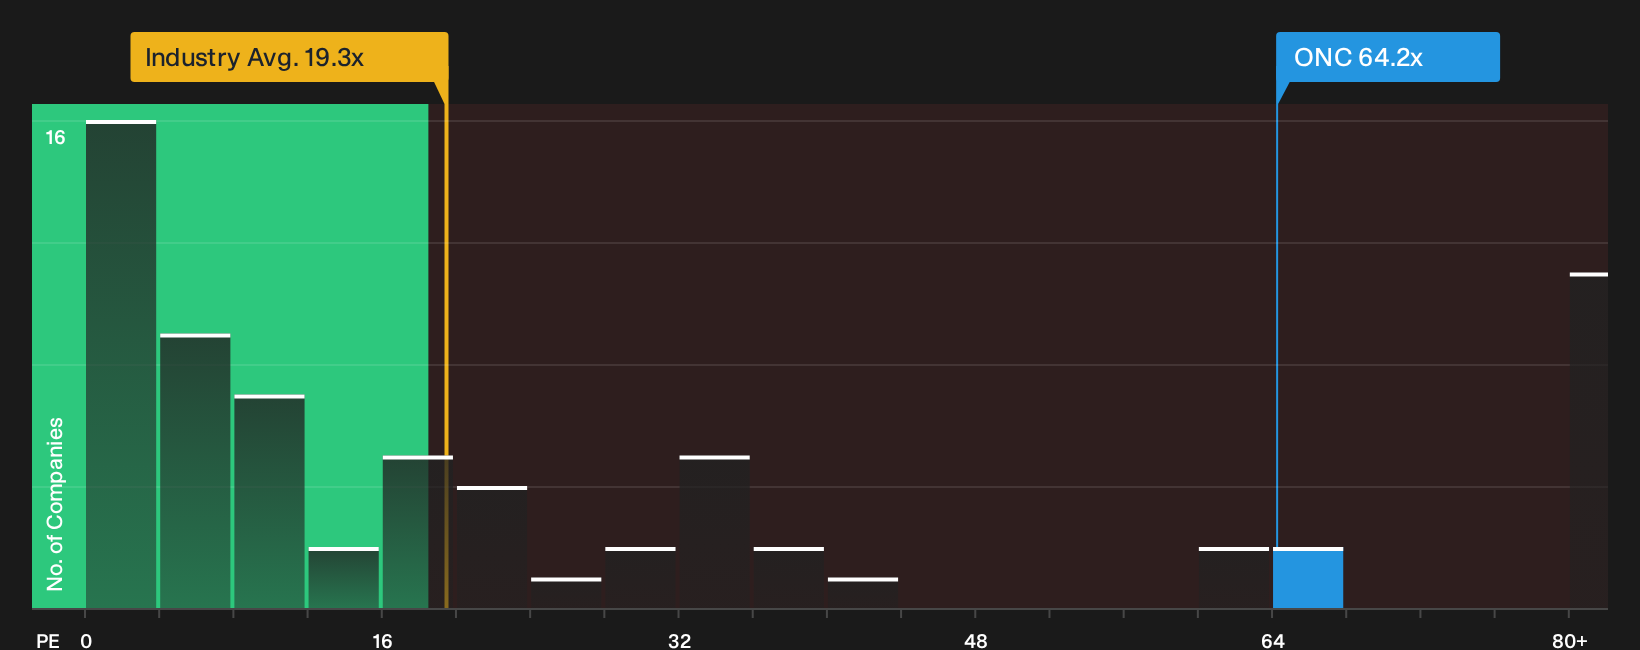
The P/E ratio is a useful yardstick here because BeOne Medicines already reports earnings that can be lined up directly with its share price. On this lens, the stock trades around 64.2x earnings, which is far above the Biotechs industry average of about 19.3x and also above the peer group near 49.1x. That points to investors paying a premium multiple to access BeOne Medicines' oncology franchise.
The Fair Ratio framework, which adjusts the benchmark P/E for factors like growth profile, profitability, scale and risk, points to a lower level than where the shares change hands today, so the current 64.2x screens as overvalued on this model. Because the recent TEVIMBRA and ZIIHERA trial data has strengthened the clinical story, it helps explain why the market is comfortable assigning a richer earnings multiple than both sector averages and closer oncology peers. Explore the numbers behind BeOne Medicines's P/E valuation.
The BeOne Medicines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle on BeOne Medicines leaves off. They spell out which combinations of growth, margins and earnings would need to hold for the stock to warrant a meaningfully higher or lower price than today. Each scenario ties a fair value estimate to a clear set of potential catalysts and risks so you can track over time which version of the story appears to be unfolding on the Community page.
Community views on BeOne Medicines split between those who see more upside left in the oncology build out and those who think the current price already bakes most of that in.
Bull case: 27% undervalued
"The emerging B cell franchise stack of BRUKINSA, newly approved BEQALZI in relapsed or refractory mantle cell lymphoma, and the BTK degrader tacabrutideg, which is targeting an accelerated approval filing and a head to head Phase 3 against pirtobrutinib, creates room for combined and sequential regimens that extend treatment lines and support higher aggregate revenue and gross profit per patient journey…"
Discover why this Narrative puts BeOne Medicines at 27% undervalued.
Bear case: roughly fairly valued
"While BeOne Medicines highlights a shift from a hematology-centric profile to a wider oncology portfolio with several solid tumor assets moving quickly toward pivotal trials, the decision to sustain mid teens operating expense growth into 2027 to fund this build out risks outpacing any incremental contribution from new regimens and could hold back further margin expansion and free cash flow…"
Explore why this Narrative puts BeOne Medicines at roughly fairly valued.
One more check for BeOne Medicines before you move on
Price multiples tell you what the market thinks of BeOne Medicines today. However, the people steering the business and how their rewards line up with your interests can be just as important. See who runs BeOne Medicines and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com