


Enphase Energy (ENPH) is back in focus after third quarter earnings missed expectations. Basic EPS from continuing operations came in at US$0.18 compared with US$0.51 a year earlier, and guidance pointed to softer near term revenue.
The share price reaction has been harsh. Enphase Energy has a 7 day share price return of down 18.8% and a 30 day move of down 21.9%. That short term slide sits on top of a 1 year total shareholder return of down 15.9% and a 3 year total shareholder return of down 68.3%, showing momentum has been fading even as the business talks up new areas like IQ SST, batteries and EV charging, alongside weaker guidance for the core residential solar market.
Scan beyond Enphase Energy's setback and compare hand-picked peers facing similar pressure with our 39 power grid technology and infrastructure stocks
Enphase Energy is pushing hard into batteries, EV charging and IQ SST, yet the share price has reset sharply. Is that drop giving you quality at a reasonable tag, or simply a cheaper way to take on the same risks?
Most Popular Narrative: 48% Undervalued
Against a last close of $25.65, the most followed narrative puts Enphase Energy’s fair value at $49.13, a wide gap that hinges on how new products and margin assumptions play out under an 11.9% discount rate.
Upcoming launches of next generation hardware, including the IQ Battery G5 with roughly 50% higher energy density at about 40% lower cost per kWh, the IQ Vault 80 kWh commercial storage system, and IQ9 microinverter families, are expected to lower unit costs and expand the range of addressable residential and small commercial projects. This can support both revenue growth and gross margin resilience.
See why 144 investors see Enphase Energy as 48% undervalued.
Result: Fair Value of $49.13 (UNDERVALUED)
Still, the narrative around Enphase Energy can unravel if weak U.S. residential solar demand persists, or if tariffs and pricing pressure continue to squeeze gross margins.
Find out about the key risks to this Enphase Energy narrative.
Another View: What Enphase Energy’s P/E Is Really Saying
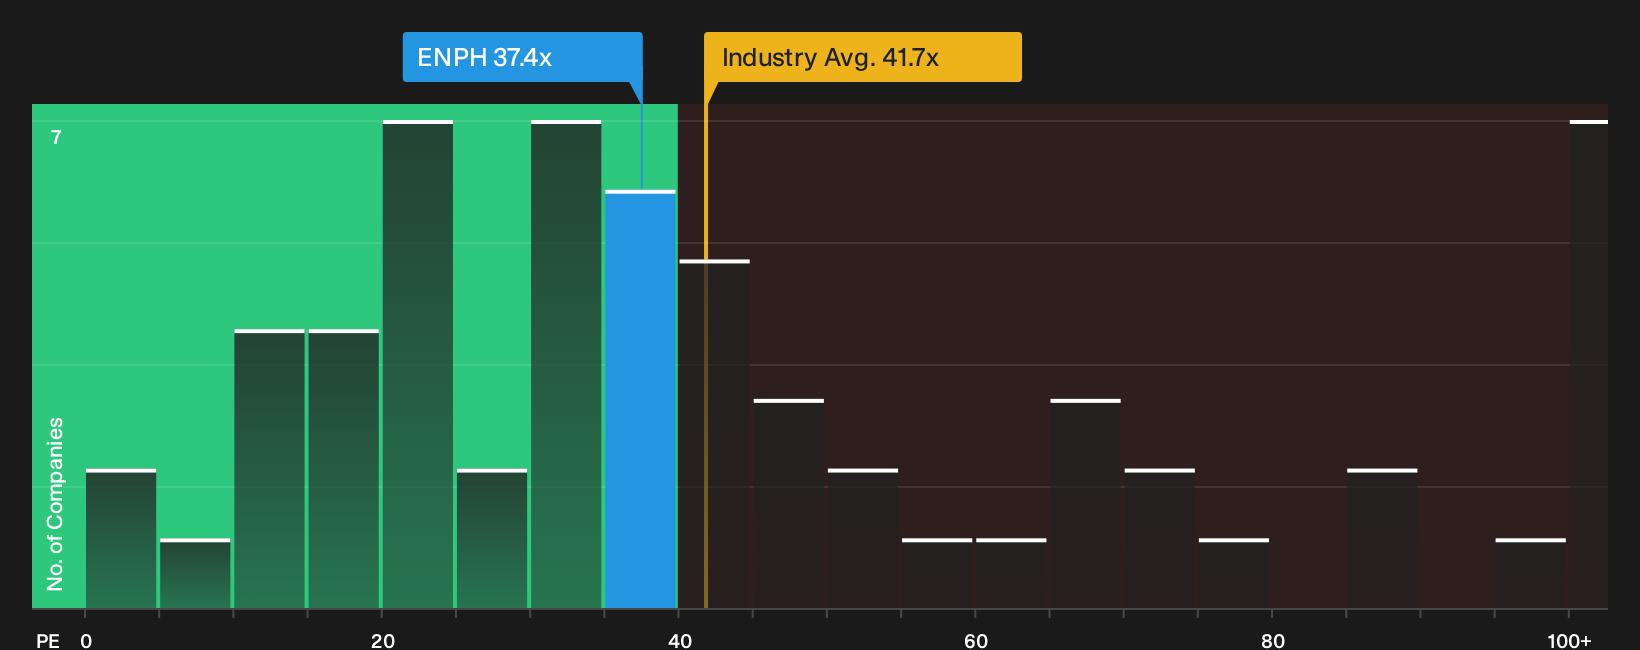
Set the narrative aside for a moment and look at the current P/E. Enphase Energy trades on 37.4x earnings. That is lower than the US Semiconductor average of 41.7x, yet above its own fair ratio of 34.9x, which suggests some valuation risk if sentiment keeps resetting.
If you prefer to anchor on earnings multiples rather than long range narratives, the question becomes simple: Are you comfortable paying a premium to Enphase Energy’s fair ratio because its peers are richer, or is that a sign to demand a bigger margin of safety instead?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings after Enphase Energy’s reset are normal, so use this as your cue to review the data now and pressure test your own stance using 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Enphase Energy?
If Enphase Energy has you reassessing where you want risk and reward, broaden your watchlist now with a few focused screens built to surface different opportunities.
- Target value potential by hunting for companies that combine strong fundamentals with appealing prices through our 29 high quality undervalued stocks.
- Strengthen your defensive side by scanning a list of solid balance sheet and fundamentals (25 results) that can better handle tough conditions and protect your capital.
- Spot tomorrow's potential leaders early by reviewing a curated pool of 18 high quality undiscovered gems before everyone else pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com