


Bristol-Myers Squibb (BMY) just lifted its 2026 guidance after reporting 7% revenue growth in the latest quarter, tying that outlook upgrade to momentum in key drugs, a busier pipeline, and heavier manufacturing investment.
On the market side, Bristol-Myers Squibb’s recent guidance lift comes after a 1-day share price return of 1.78% and a year-to-date share price gain of 16.87%. The 1-year total shareholder return of 41.65% points to momentum building as pipeline news and collaborations around oncology, neurology, and AI driven drug development reshape how investors view its risk and opportunity mix.
Scan how Bristol-Myers Squibb’s guidance lift fits alongside other potential opportunities by reviewing a curated group of 30 high quality undervalued stocks.
Bristol-Myers Squibb now trades at a meaningful discount to both intrinsic value estimates and analyst targets, despite the guidance lift. Is that pricing in real pipeline and patent risk, or leaning too far toward caution?
Most Popular Narrative: 119% Overvalued
The most widely followed narrative on Bristol-Myers Squibb pegs fair value at $28.50, far below the recent close at $62.48. This frames the current guidance lift against a much more cautious valuation anchor.
Price sits slightly above my fair value estimate, so the stock looks fairly priced rather than cheap. The yield is attractive, but at this level the margin of safety is thin and the growth-adjusted picture is not supportive. I''d rather wait for a pullback toward the lower supports, where the risk/reward would improve meaningfully. Until then, it stays on watch.
See why 1 investors see Bristol-Myers Squibb as 119% overvalued.
Result: Fair Value of $28.50 (OVERVALUED)
Still, if Bristol-Myers Squibb faces deeper drug pricing pressure or setbacks on newer therapies, that overvaluation narrative could unwind more quickly than expected.
Find out about the key risks to this Bristol-Myers Squibb narrative.
Another View: Multiples Paint Bristol-Myers Squibb As Cheap
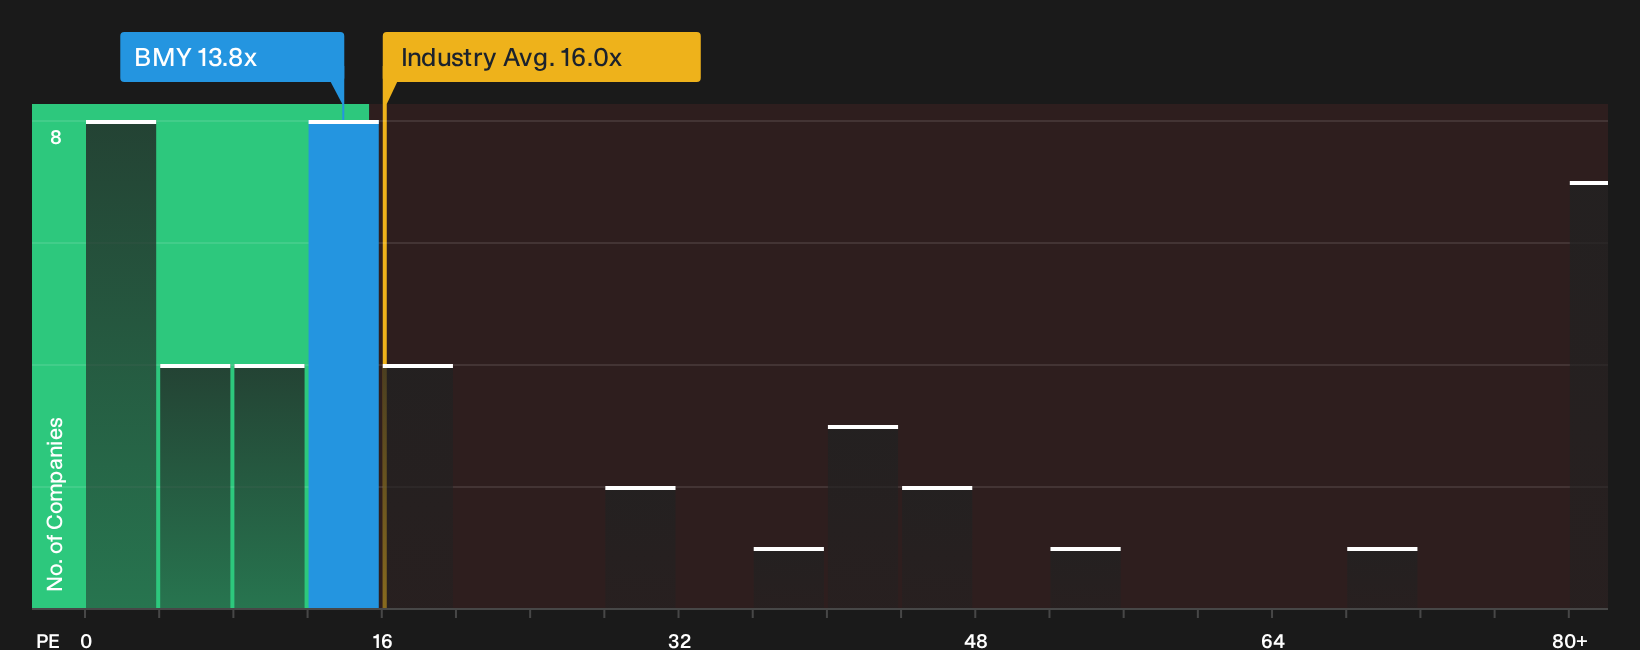
Where the $28.50 fair value narrative flags Bristol-Myers Squibb as 119% overvalued, the current P/E of 13.8x tells a different story. It sits below the US pharmaceuticals average at 16x and far below a fair ratio of 22.8x. This points to valuation risk skewed more toward opportunity than excess. Which signal do you trust when the market is this split?
Our valuation check based on earnings focuses squarely on that P/E gap versus peers and the fair ratio. It is worth seeing how the detailed breakdown lines up with your own assumptions before you lean too hard on any single price target. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Bristol-Myers Squibb’s value can be useful if you treat them as raw material, not a script you must follow. Take a close look at the key risks and potential rewards, then weigh them against your own expectations with 4 key rewards and 3 important warning signs.
Looking for more Bristol-Myers Squibb sized ideas?
If Bristol-Myers Squibb has you rethinking value, do not stop here. Fresh ideas often come from comparing a few different setups side by side.
- Target resilience first and filter for companies with sturdier finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced potential and see which businesses line up inside the 19 high quality undiscovered gems.
- Prioritize sleep-at-night holdings and narrow in on steadier options with the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com