


Manhattan Associates came into this Q3 2026 print priced for perfection, with the stock already carrying a rich P/E and a strong recent run. The report then landed with exactly the kind of headline that tests that premium. Cloud revenue reached US$134m and total sales hit US$306m, while adjusted EPS printed at US$1.55.
Instead of a selloff, the market leaned in. The share price climbed about 3% to US$248.39 on the first full trading day after the release, signaling that investors saw enough in these numbers to keep backing the warehouse and supply chain software story.
Love Manhattan Associates' cloud momentum but cautious about paying up for a rich P/E and perfection pricing? Consider filtering for peers with robust operations and cleaner balance sheets in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): US$306.2m vs. US$275.8m (+11.0%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$61.3m vs. US$58.6m (+4.6%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.05 vs. US$0.97 (+8.6%)
- Cloud Revenue (Q3 2026 vs. Q3 2025): US$134m vs. US$105m (+27.6%)
Management says every Active AI pilot turned into a subscription. Ask Charlie what Manhattan Associates' AI pilots proved to customers.
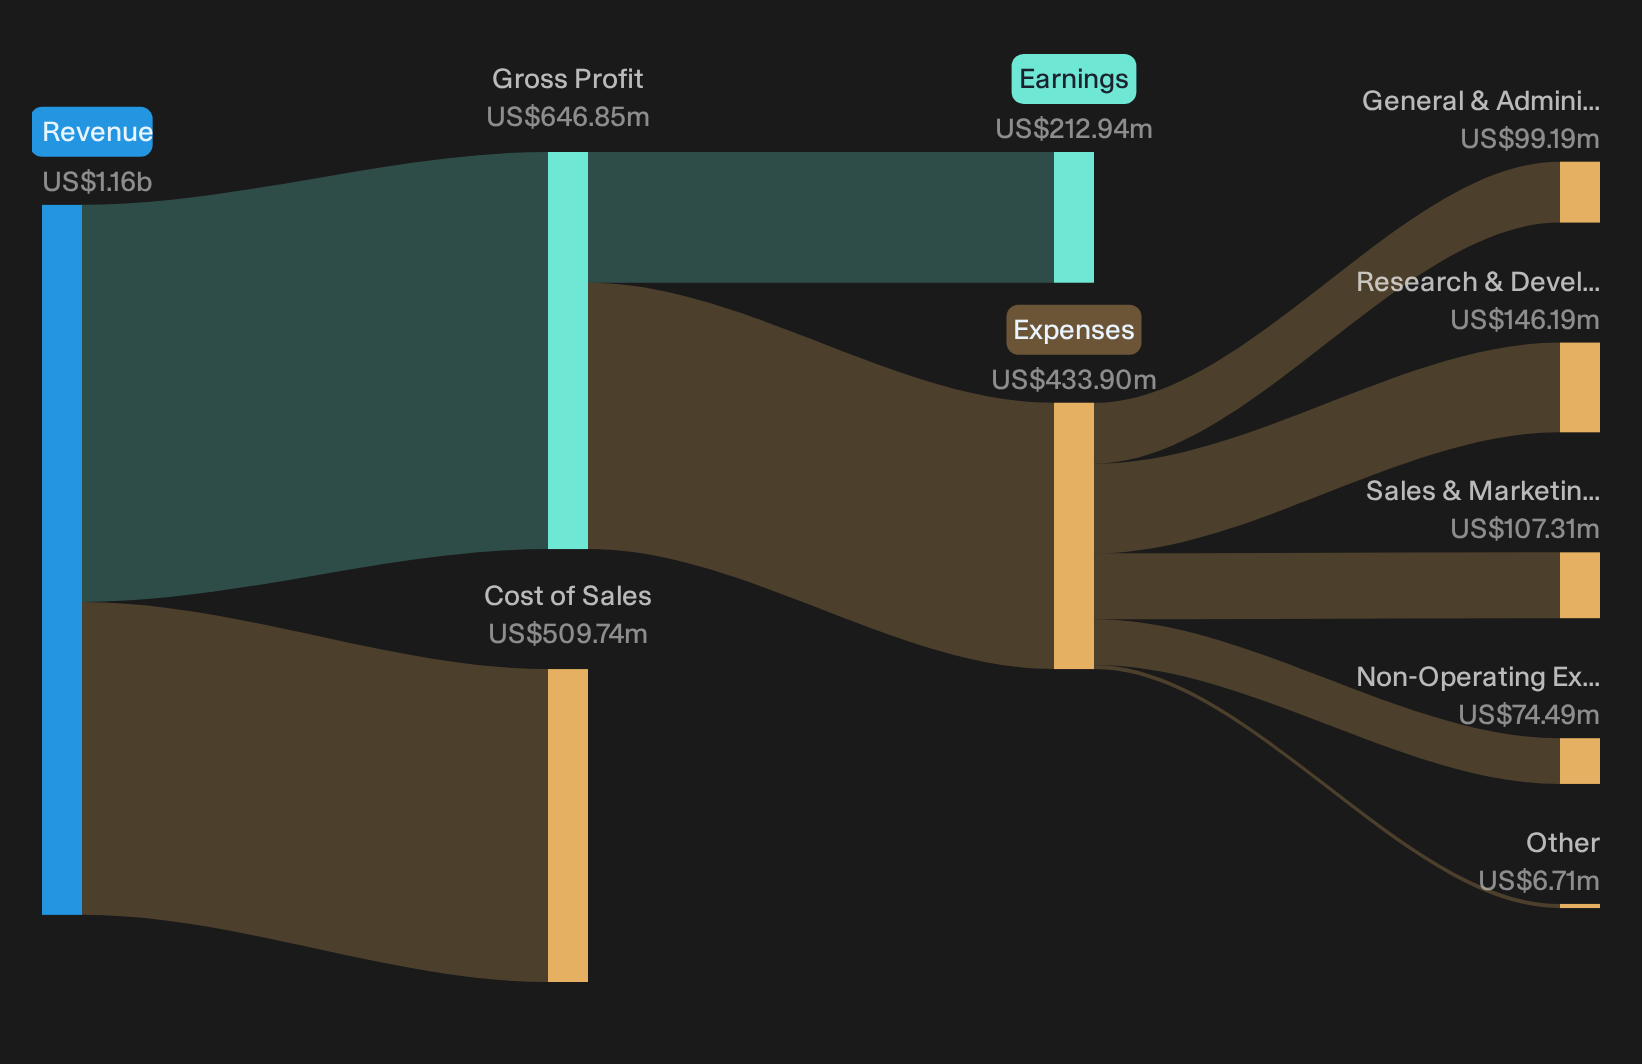
Manhattan Associates: Cloud Milestones Versus Bullish Hopes
The upbeat thesis centers on Manhattan Associates turning its installed base into a high margin cloud and AI franchise.
"The main thing that has to go right is that Manhattan Associates converts a large share of its on prem customers to the Manhattan Active cloud platform while maintaining strong margins and managing service utilization and legal or governance risks."
Q3 shows measurable progress on the first part of that sentence. Cloud revenue of US$134m now matches services at US$134m, and RPO has reached US$2.59b, with four consecutive quarters of record bookings. An adjusted operating margin of 37.6% indicates the shift is not significantly eroding profitability.
One Narrative disagrees with today's price. → See where this Narrative says Manhattan Associates should trade.
Manhattan Associates: Cloud Wins, Margin Fears Lingering
Bearish skepticism hinges on whether Manhattan Associates can keep cloud growth attractive without eroding profitability as AI and Editions scale.
"While the Editions packaging is intended to expand adoption of the unified Manhattan Active platform across more customer tiers, criticism that average billings growth was only 5.8% with gross margin around 56% and flat operating margin suggests that a heavier mix of lower priced, packaged deals could lock in weaker unit economics and restrict future net margin expansion."
Q3 adjusted operating margin of 37.6% and a higher full year margin outlook show no clear squeeze yet. The concern on weaker unit economics is not resolved either, because services revenue is almost flat and Editions are still early, so there is limited proof that these contracts scale profitably over time.
Hunt For Quiet Fundamental Shifts
Manhattan Associates just showed how a solid cloud story can keep investors engaged at a premium P/E. The real opportunity could sit in stocks where fundamentals are changing faster than the valuation.
- Company 1 - 38% below our estimate - uses government backed trade in subsidies to expand intake of used devices for refurbishment.
- Company 2 - 29% below our estimate - sells AI centric networking and infrastructure adopted as enterprise machine learning projects move into production use.
- Company 3 - 28% below our estimate - supplies diagnostic equipment utilities rely on when upgrading grids for electrification and higher reliability standards.
Three companies from the same screener. Open the full list of 30 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com