


- Precigen, a biotechnology company focused on gene and immunotherapies, now faces a new rival in recurrent respiratory papillomatosis after the FDA approved Inovio Pharmaceuticals' Voceryq, which targets the same adult RRP market as Precigen's PAPZIMEOS.
- This approval introduces a fresh treatment option into a previously less crowded segment. It raises questions about how Precigen's existing commercial infrastructure, in house manufacturing and payer relationships might absorb direct competition in its primary indication.
- We will examine how Precigen's investment narrative around PAPZIMEOS is tested by Inovio's FDA approved RRP competitor entering its core market.
Pressure test Precigen's story against peers by lining up its profile beside 30 high quality undervalued stocks.
Precigen Investment Narrative Recap
To own Precigen, you need to believe PAPZIMEOS can still anchor the story even with Voceryq now approved in adult RRP. The near term focus remains on how efficiently the commercial team can turn existing coverage wins and hub referrals into treated patients, while keeping in house manufacturing running at a scale that supports margins.
The biggest risk is now more balanced between execution and competitive pressure. Slower than hoped adoption, combined with a single primary indication and less than one year of cash runway, could force fresh capital. That would matter more if Voceryq captures share before any pediatric or geographic expansion pays off.
One datapoint that ties directly into this development is management's prior emphasis that PAPZIMEOS raised the clinical bar and would be difficult to displace. That claim now meets its first direct test in the field, with physicians and payers comparing two approved options for the same adult RRP population.
For you as an investor, the key watch items are simple. Tracking real world treatment durability, payer behavior on gross to net discounts, and any commentary on how often PAPZIMEOS is chosen versus Voceryq will say more about Precigen's path to the targeted cash flow breakeven by the end of 2026 than short term share price swings.
What The Precigen Consensus Is Really Asking You To Underwrite
Precigen's narrative ties back directly to the analyst spreadsheet. The current models lean on a very fast 96.9% yearly revenue growth rate over the next three years, from a base where the business is still reporting a loss of $336.7 million in earnings today. Those same forecasts point to consensus earnings of $393.8 million by 2029, which implies an earnings swing of about $730 million from the current loss to the projected profit. In addition, analysts are penciling in 2029 revenue of $654.3 million as the PAPZIMEOS story matures within RRP and beyond.
Precigen's narrative projects $654.3 million in revenue and $393.8 million in earnings by 2029. This requires 96.9% yearly revenue growth and an earnings improvement of about $730 million from a current loss of $336.7 million.
Discover why Precigen's fair value indicates a 97% potential upside to its current price, which could narrow quickly.
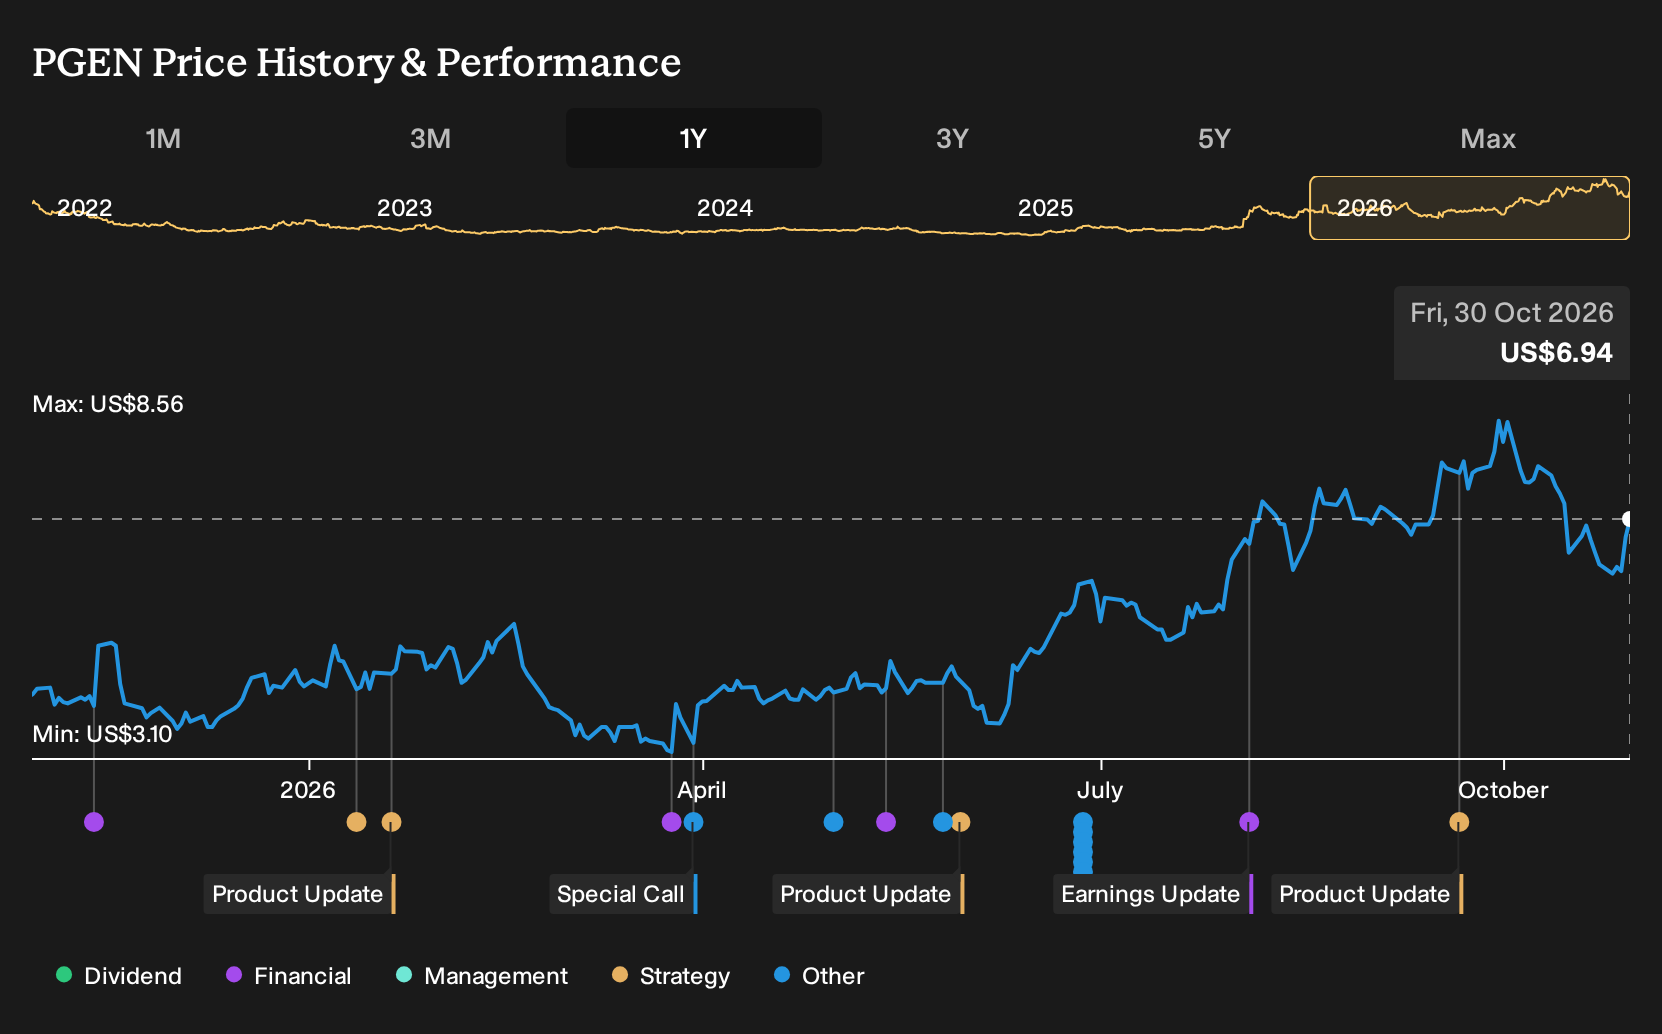
Exploring Other Perspectives
One alternate view on Precigen zooms in on concentration risk. Before this news, the most optimistic analysts were comfortable with PAPZIMEOS carrying forecasts of about US$621.6 million in 2029 revenue and US$374.0 million in earnings. You can now ask whether that single product dependence still feels right, knowing these projections did not factor in Voceryq at all.
Explore 2 other Precigen fair value estimates, including one that suggests as much as 570% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Precigen research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Precigen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Precigen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Precigen?
Once you have formed a view on Precigen, it can help to set that stance in context by lining it up against other opportunities with different risk and return profiles. A broad watchlist gives you options if the Precigen thesis takes longer to play out than expected or if the risk feels too concentrated.
- If you want to focus on financial resilience first and potential upside second, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without constant refinancing worries.
- For investors who prefer opportunities where the price already looks conservative relative to fundamentals, consider a 30 high quality undervalued stocks that share stronger cash generation and cleaner balance sheets.
- If you are aiming to dial down volatility and concentrate on steadier profiles, scan through a 29 resilient stocks with low risk scores that score well on Simply Wall St's internal risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com