


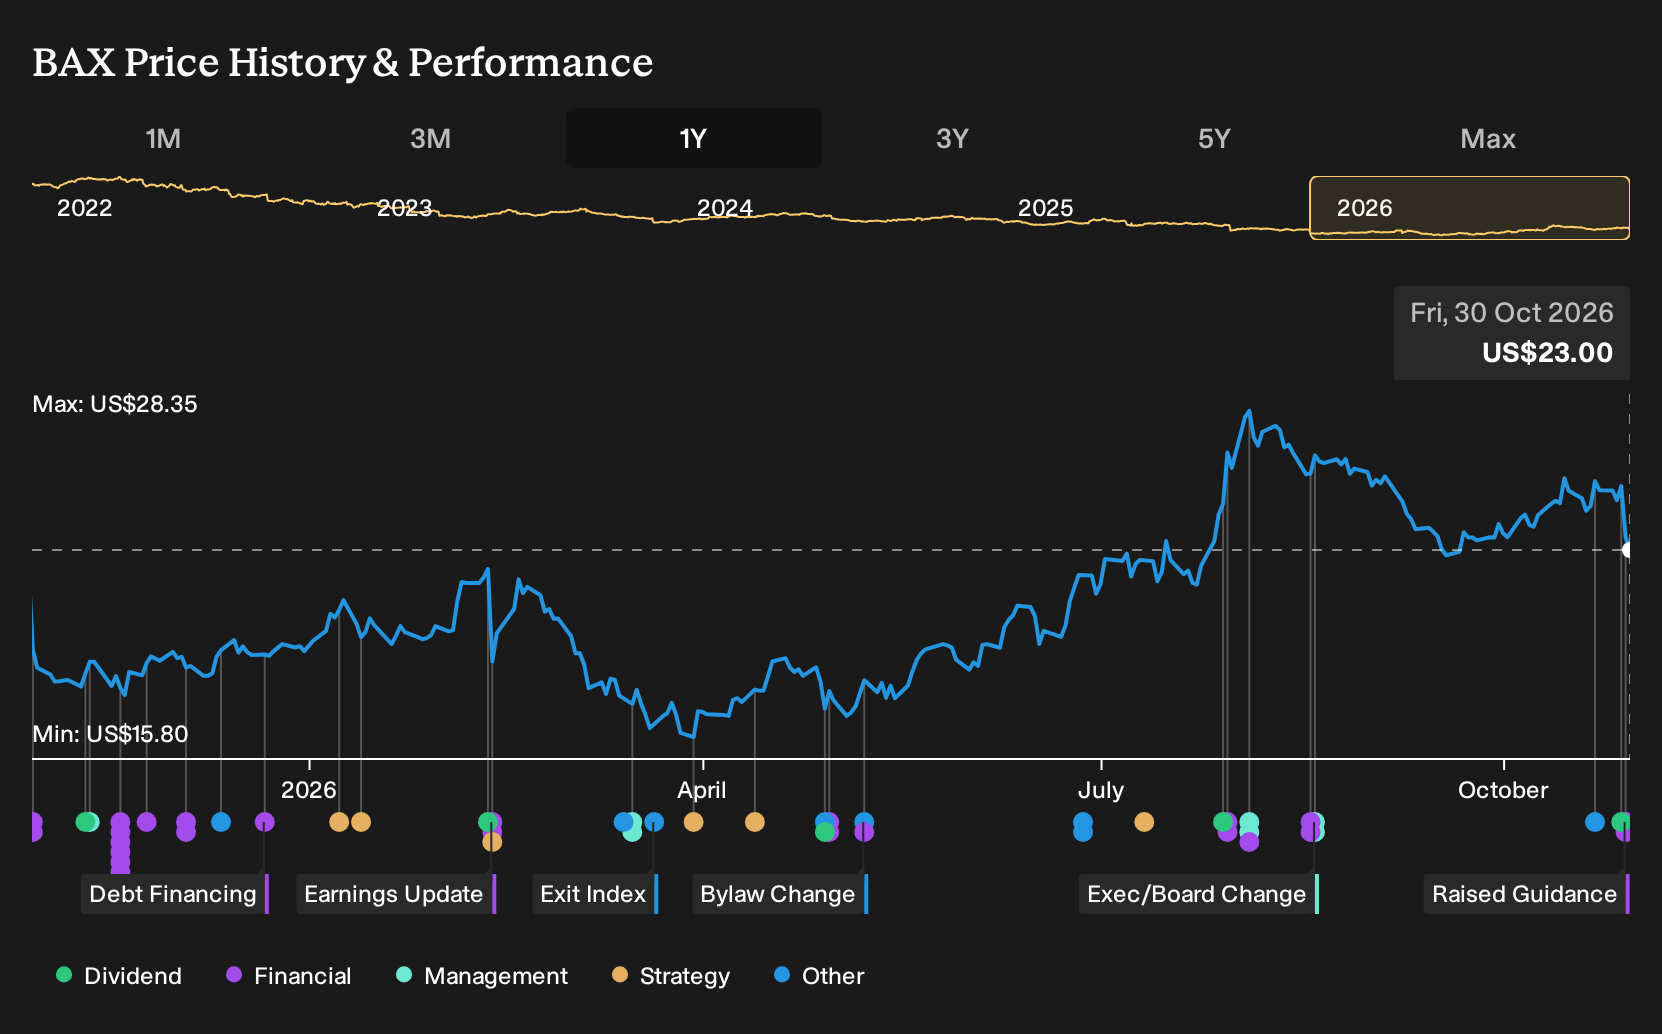
- Baxter International reported Q3 2026 sales of US$2,976 million and net income of US$294 million, raised full year 2026 earnings guidance, and affirmed a quarterly dividend following past quarter performance.
- The earnings upgrade came alongside an FDA warning letter over significant manufacturing violations at the Round Lake facility, adding fresh operational and compliance pressure just as Baxter International discontinues cephalosporin injectables there.
- Next, the focus shifts to how Baxter International's raised 2026 outlook, despite FDA scrutiny, could reshape the broader investment narrative.
Scan how Baxter International's mix of upgraded guidance and regulatory heat compares with other healthcare players by checking the hand picked 29 resilient stocks with low risk scores that aim for resilience when headlines turn messy.
What Is Baxter International's Investment Narrative?
To own Baxter International, you need to be comfortable with a classic trade off. The group has a broad hospital focused portfolio, improving earnings guidance for 2026, and recently reported Q3 sales of US$2,976 million with net income of US$294 million. That points to operational momentum. The decision to discontinue cephalosporin injectables at Round Lake and the FDA warning letter pull attention back to execution and quality systems, because any disruption here can touch both supply reliability and cash generation.
In the short term, the key levers are how cleanly Baxter International exits the affected products, maintains demand and pricing in core therapies, and funds remediation and capital needs while already carrying debt that is not well covered by operating cash flow. The affirmed dividend is modest at US$0.0100 per share, yet still signals a desire to show stability as the new management team, with relatively short tenure, tries to prove that higher guidance is compatible with tighter compliance costs rather than flattered by them.
Yet there is a further pressure point in this story that only really shows up once you look at ...
There's only one way to know the right time to buy, sell or hold Baxter International. Head to Simply Wall St's company report for the latest analysis of Baxter International's Fair Value.
Exploring Other Perspectives
One alternate angle focuses on the risk that Baxter International never fully escapes lower margin hospital and TSA income. The most pessimistic analysts were penciling in revenue of about US$12.3b and earnings of roughly US$691.3 million by 2029, yet still viewed that scenario as already reflected in the share price. That is a much cooler story than the baseline. Use it as a reminder that reasonable people can look at the same numbers and disagree widely, and treat this raised 2026 outlook as a fresh reason to revisit which camp you find more convincing.
Explore 4 other Baxter International fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Baxter International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Baxter International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Baxter International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Baxter International?
If this Baxter International update has sharpened your view on risk, income, and balance sheet quality, you can use that same checklist to look for other opportunities with the Simply Wall St Screener.
- If you want potential upside with a margin of safety, filter for companies that combine quality metrics with valuation support through the 30 high quality undervalued stocks.
- If reliable income is a priority, scan for higher yielding businesses with more robust payout profiles using the 5 dividend fortresses.
- If capital preservation comes first, start with shares that score well on fundamentals and financial strength by running the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com