


FTAI Aviation (FTAI) drew fresh attention after third quarter 2026 results showed higher revenue and earnings, along with a larger share repurchase plan and new dividends on both common and preferred stock.
FTAI Aviation’s latest earnings, dividend declarations and the expanded US$1b repurchase authority have come after a sharp recent move, with a 7 day share price return of 21.31% and a 30 day gain of 12.12%. However, the stock is still down 10.97% on a year to date share price basis, while long term investors have seen very large 3 year and 5 year total shareholder returns. This points to strong momentum over time despite a 16.82% share price decline over the past 90 days and a 4.46% drop on the day of the results that hints at some investors reassessing risk and valuation at the current US$187.27 level.
Scan how FTAI Aviation compares with other companies showing strong momentum and fundamentals using the hand picked 31 high quality undervalued stocks.
FTAI Aviation just rallied hard on earnings, buybacks and fresh dividends, yet the share price is still below its recent peak. Do you lean into the momentum now, or wait for a cheaper entry while you evaluate whether the valuation case is compelling?
Most Popular Narrative: 16.8% Undervalued
FTAI Aviation is trading at $187.27 against a widely followed fair value estimate of $225.05. This frames the current pullback as a pricing gap rather than a verdict on the business model.
FTAI Aviation is not a traditional aircraft lessor. It is evolving into a hybrid aerospace infrastructure and aftermarket platform.
Strengths: structural tailwinds, integrated model, aftermarket margins. Weaknesses: leverage, concentration, execution complexity. Key risk: dependence on aging fleet economics holding longer than expected.
See why 5 investors see FTAI Aviation as 17% undervalued.
Result: Fair Value of $225.05 (UNDERVALUED)
Still, FTAI Aviation leans heavily on aging CFM56 and V2500 engines, and higher leverage could quickly matter if aviation cycles or credit conditions turn against it.
Find out about the key risks to this FTAI Aviation narrative.
Another View: FTAI Aviation Through The P/E Lens
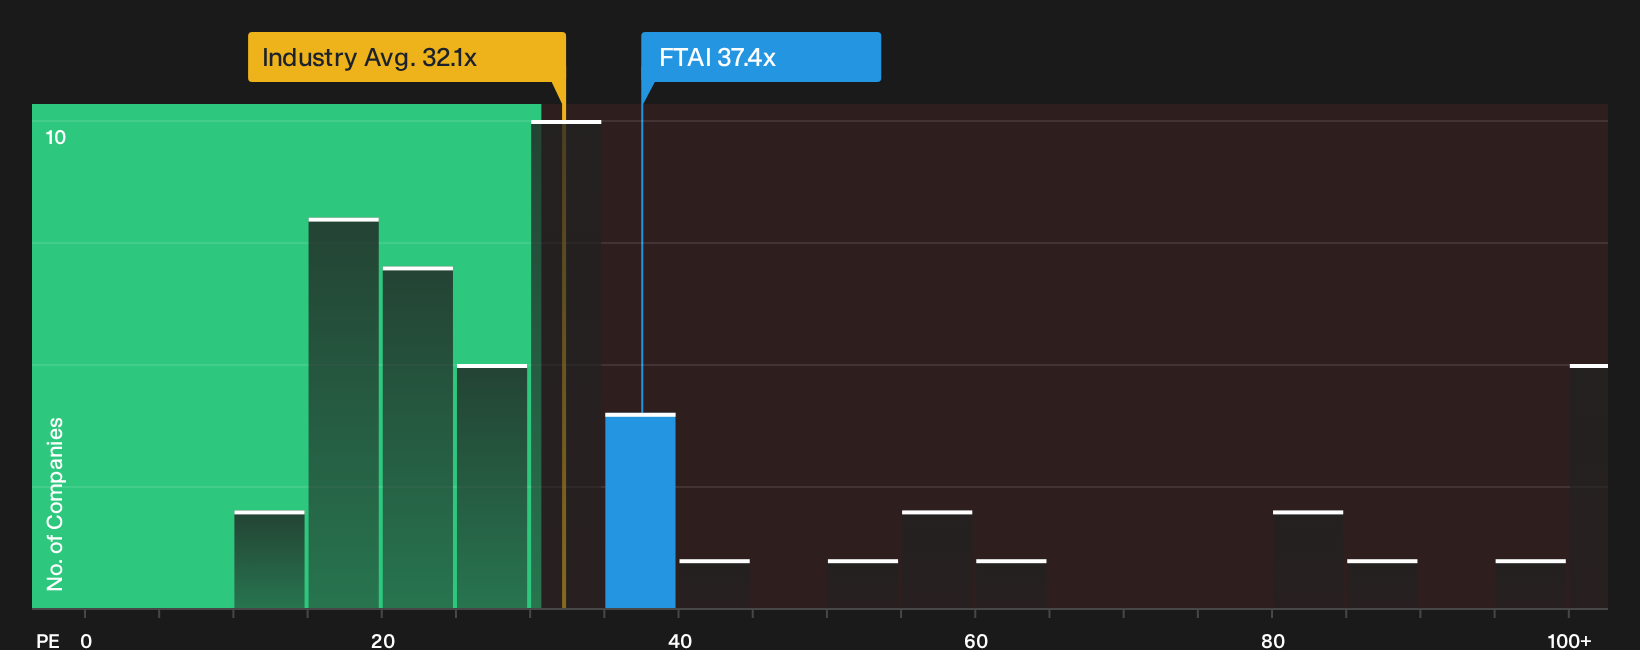
That 16.8% discount to a US$225.05 fair value points one way. The current P/E ratio of 37.4x sends a different signal, since it is richer than both the US Aerospace & Defense industry at 32.1x and the peer group average at 20.6x, even though our fair ratio estimate sits higher at 56.8x. For you as a shareholder, that mix of premium pricing today and potential room for the multiple to move toward the fair ratio raises a simple question: Is this a cushion for future upside or a sign that expectations already run hot?
Before leaning too heavily on one metric, it helps to see how these valuations stack up in more detail, including what the current multiple implies for risk and upside compared with peers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on FTAI Aviation in this piece is mixed, with clear positives and clear pressure points. Act while the data is fresh and weigh both sides for yourself by checking the 3 key rewards and 1 important warning sign.
Looking for more FTAI Aviation style investment ideas?
Do not stop your research with FTAI Aviation. With so much competition for your capital, giving yourself a broader watchlist now can really sharpen your decisions.
- Target dependable cash flow by steering toward companies that appear built to weather shocks using our 29 resilient stocks with low risk scores.
- Hunt for quality at a potential discount by scanning businesses that combine strong fundamentals with appealing valuations through the 19 high quality undiscovered gems.
- Strengthen your income playbook by focusing on companies that pair higher yields with resilient profiles via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com