


Niterra shares closed at ¥3,451 on 30 October, roughly flat over the past week but still down sharply over three months. The Q1 2027 report then landed with a jolt. Basic earnings per share printed at ¥248.98 and quarterly net income reached ¥97,267m, reshaping the earnings profile far more than the recent chart suggests.
The short term tape indicates this is a stock treading water. The trailing twelve month picture, with earnings of ¥186,125m and a P/E near 7x, presents a very different story that long term holders cannot ignore.
Love Niterra’s earnings punch but concerned the low P/E might signal a value trap rather than a bargain? Compare it with our 16 high quality undervalued stocks to see how it stacks up beside other cash generative, financially solid stocks.
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): ¥203,705m vs. ¥169,927m (up about 20%)
- Net Income (Q1 2027 vs. Q1 2026): ¥97,267m vs. ¥24,034m (up very sharply, roughly 4x)
- Basic EPS (Q1 2027 vs. Q1 2026): ¥248.98 per share vs. ¥60.55 per share (up very sharply, roughly 4x)
- Net Profit Margin (Trailing 12 Months vs. Prior Year): 24.3% vs. 13.5% (meaningfully higher profitability on recent earnings)
Niterra’s earnings surged while its P/E still trails peers. Ask Charlie what makes Niterra look this undervalued.
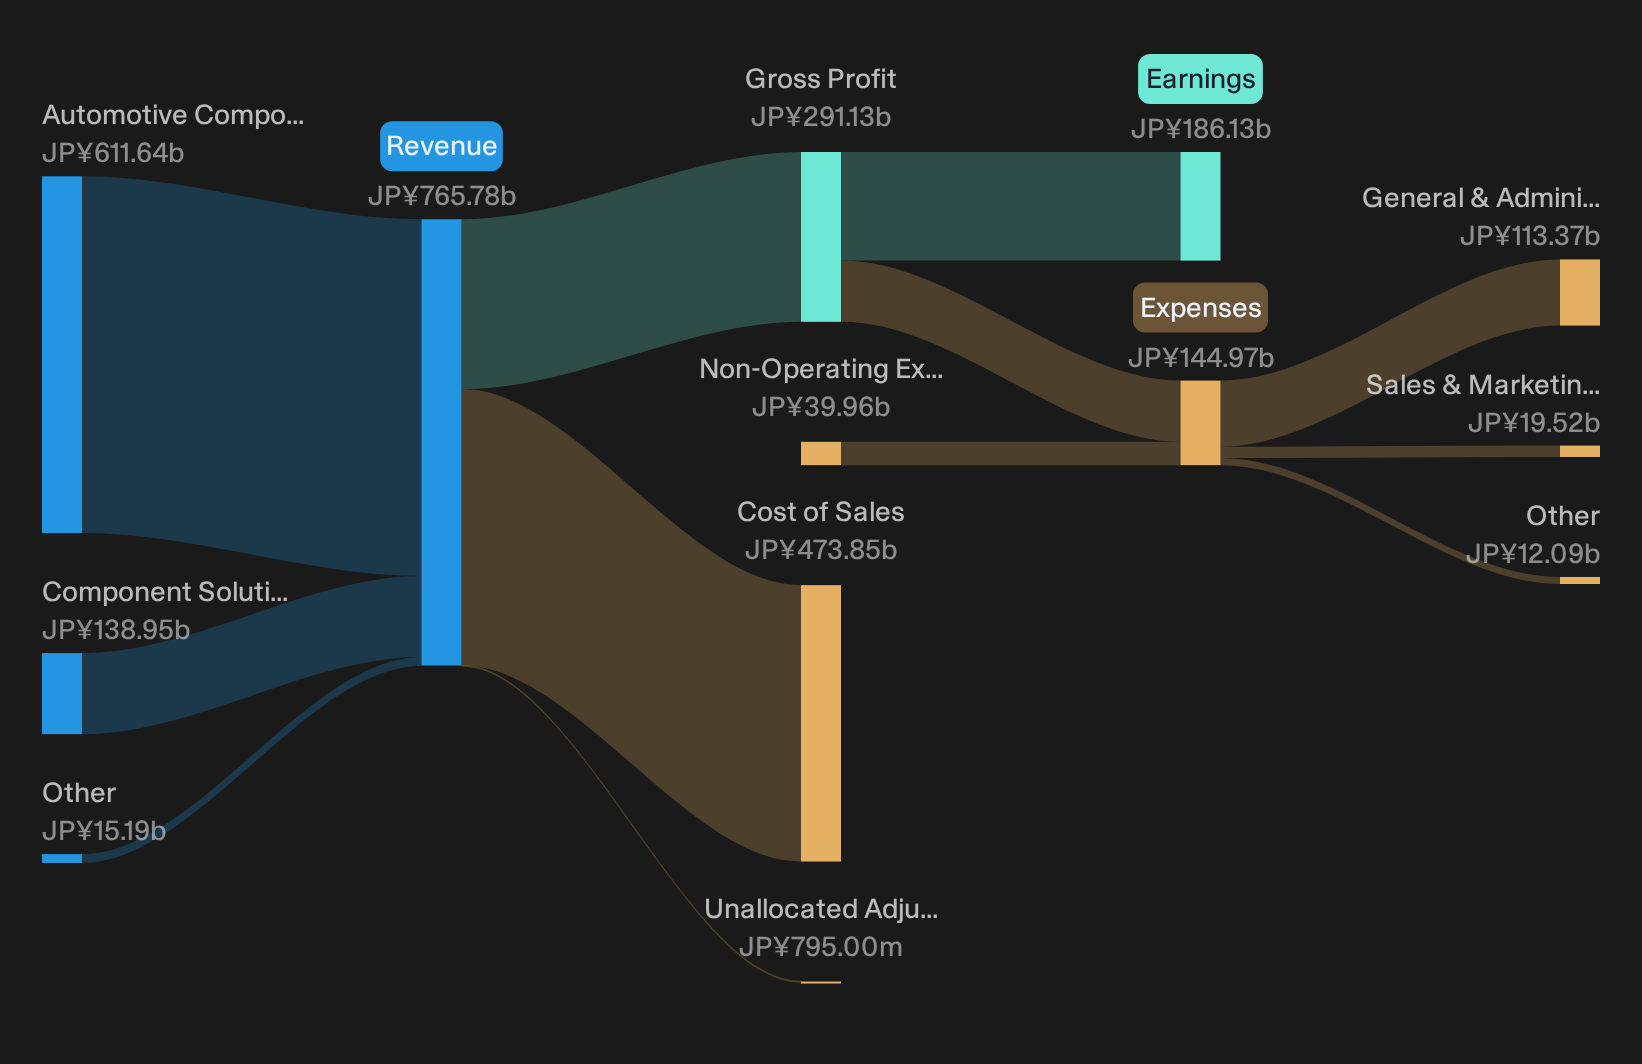
Niterra’s Earnings Muscle And Diversification Story
Niterra’s latest quarter leans in favour of the diversification and earnings power story. Revenue of ¥203,705m against ¥169,927m and net income of ¥97,267m against ¥24,034m both move in the same positive direction as the rebranding narrative. Basic EPS rising from ¥60.55 to ¥248.98 and a trailing net margin at 24.3% compared with 13.5% supports the view of a business now earning more on every yen of sales, not just relying on legacy spark plugs.
Testing ICE Risk And Profit Sustainability
Bearish worries focus on internal combustion engine exposure and the chance current profits prove hard to repeat. Recent numbers, though, point to stronger earnings rather than immediate stress. Net income is several times higher than a year ago and profitability on a trailing view has stepped up from 13.5% to 24.3%. Share performance has still fallen about 27% over 90 days, so sentiment has not caught up. That gap keeps questions alive about how durable this earnings mix is if auto demand softens or mix shifts.
Are you convinced Niterra’s earnings power now looks more durable than the share price suggests, or think the market has it right already? Check the consensus price target analysis for Niterra.
Hunt For Dislocated Earnings Power
Niterra highlights how earnings strength and share prices sometimes move out of sync. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 32% below our estimate - builds the payment plumbing merchants use to stitch together cards, carriers, bank transfers and pay-later options in a single stack. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 2 - 21% below our estimate - supplies the tiny connectors designers pick when devices need faster signals squeezed into tighter, lighter hardware. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 3 - 39% below our estimate - runs the virtual performers brands hire when they want live fan engagement without the limits of physical talent schedules. The real opportunity is finding stocks that could be undervalued before the market corrects them.
Those are three of them. See every one of the 16 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com