


- Soluna Holdings reported a past agreement with Applied Digital to create a jointly owned entity to build a 50 MW AI and high performance computing data center at the Dorothy 3 site in Texas, with Applied Digital expected to contribute capital and hold a 51% stake once multiple closing conditions are met.
- The planned Dorothy 3 facility, which is intended to source electricity from both the grid and the Briscoe Wind farm, highlights how Applied Digital is tying new AI data center capacity directly to power access and project level financing rather than relying solely on existing operations.
- We will now look at how Applied Digital's investment narrative could shift as it commits capital to this joint AI data center.
Scan beyond Applied Digital and explore other power hungry AI infrastructure plays by checking out our hand picked 54 AI infrastructure stocks that could be preparing for their next phase of capacity expansion.
Applied Digital Investment Narrative Recap
To own Applied Digital, you need to believe the AI and high performance computing build out can eventually outweigh its crypto exposure, heavy debt load and current losses. The short term story still revolves around getting new capacity leased at solid economics while managing a balance sheet that has less than one year of cash runway and interest expense above rent income.
The Soluna joint venture fits that thesis but does not change the main near term swing factors yet. Execution risk stays high around securing power, hitting build timelines and keeping hyperscaler clients committed. The biggest operational risk remains underutilized, capital intensive sites that do not generate enough cash to comfortably cover funding costs.
The lease commitments with CoreWeave and two other hyperscalers, about US$36b of signed rent in total, matter most against this new Dorothy 3 project. Those contracts frame how additional AI campuses like Dorothy 3 could be filled and how much incremental utilization the firm might realistically support if financing and power line up.
Analysts have raised revenue expectations but cut earnings forecasts, now modeling a loss in fiscal 2028 despite that contracted backlog. That tension between booked rent, high interest costs and expected losses is the context for judging Dorothy 3. You are weighing another capital intensive build against the existing obligation to turn those long term leases into sustainable cash generation.
Applied Digital's current earnings are a loss of US$451.8 million, with analysts forecasting earnings of US$41.0 million by 2029 and projecting revenue of US$3.4 billion in that same year. According to these projections, revenue would increase by 57.6% per year and earnings would improve by about US$492.8 million from today's loss to the 2029 forecast profit.
Uncover how Applied Digital's fair value indicates a 250% potential upside to its current price before the gap closes and sentiment improves.
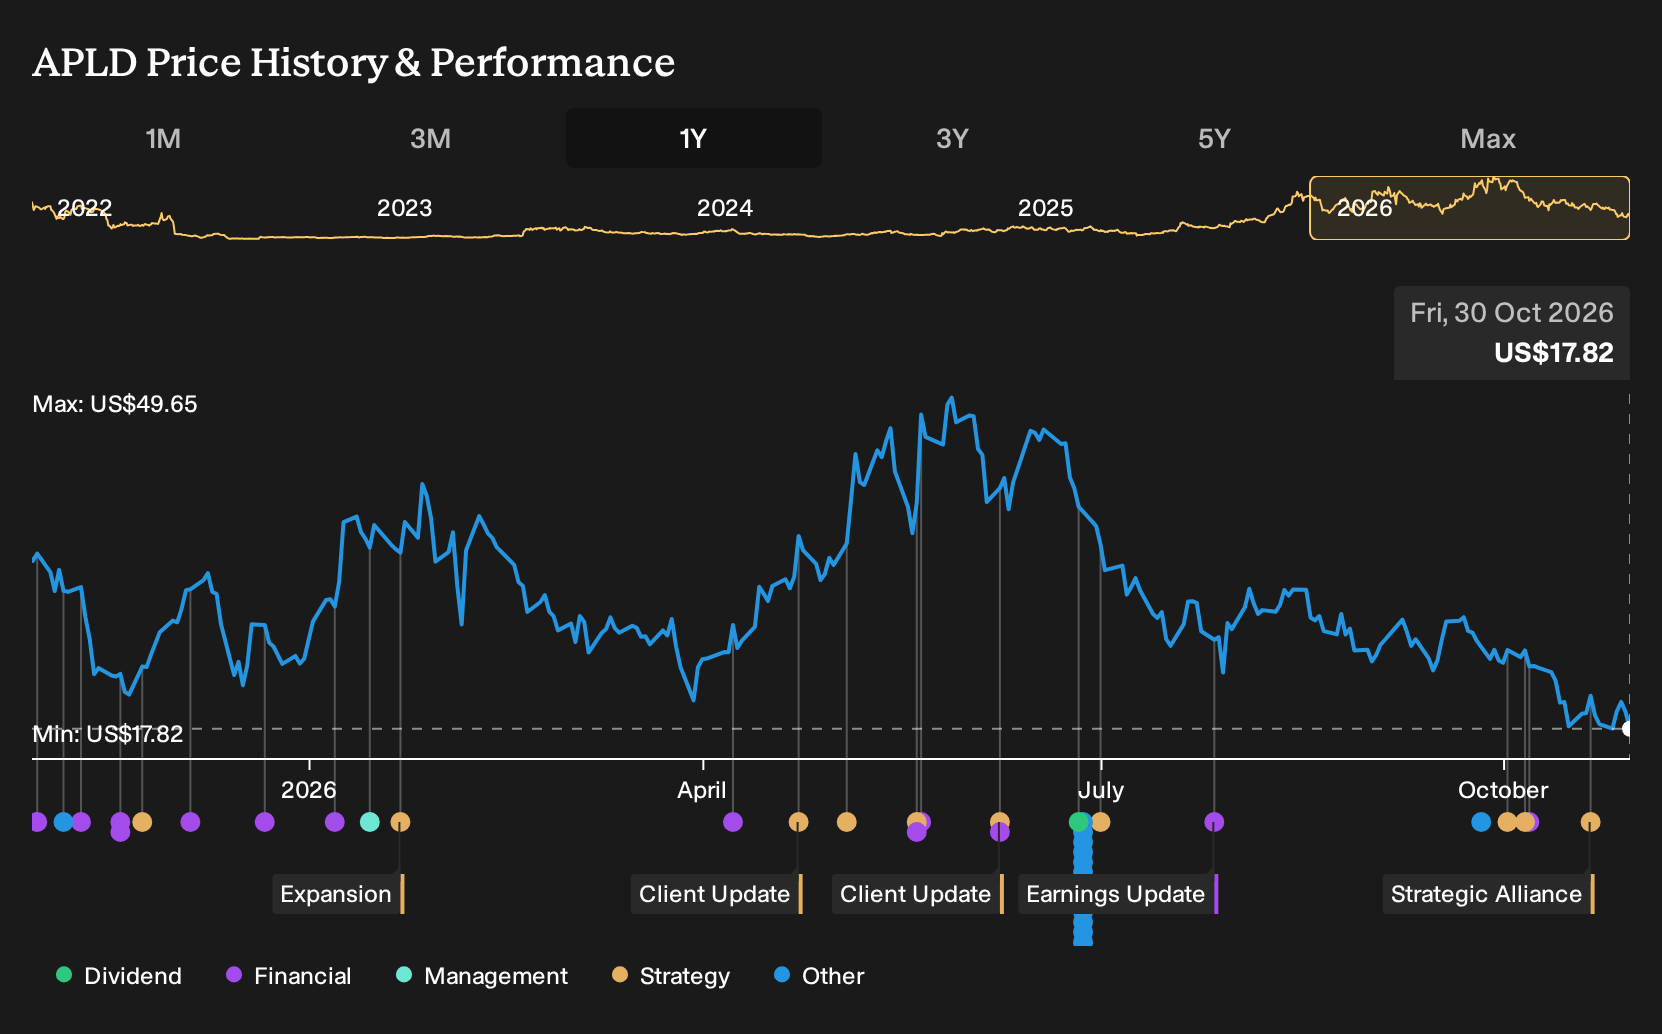
Exploring Other Perspectives
You have one big swing factor to watch here. The most bearish analysts worry that Applied Digital will struggle to fund new builds, even though they were still penciling in about US$2.2b of revenue and US$164.8 million of earnings by 2029. Their pre news view is far more cautious. Treat Dorothy 3 as a potential narrative reset and compare these contrasting expectations yourself.
Explore 5 other Applied Digital fair value estimates, including one that suggests it could be worth just $22.15!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and research.
- A great starting point for your Applied Digital research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Applied Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Applied Digital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Applied Digital?
Once you have formed a view on Applied Digital, it often helps to broaden the watchlist and compare it with other opportunities that fit different risk and return profiles. The Simply Wall St Screener can help you quickly surface companies that match the type of balance sheet strength, income potential, or mispricing you are hunting for.
- If you care most about price discipline and business quality, scan through our hand picked 33 high quality undervalued stocks that combine strong fundamentals with what may be appealing entry points.
- For investors who want income to play a bigger role in total returns, focus your search on companies in the 5 dividend fortresses that offer higher yields alongside more robust payout histories.
- If capital preservation ranks near the top of your priorities, narrow your universe to the 29 resilient stocks with low risk scores that score better on financial resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com