


Meiwa stock closed at ¥922 on 30 October, rounding off a month where the share price slipped about 7% even as the latest Q1 2027 report landed. The immediate read is soft. The longer view looks very different.
The fresh quarter showed revenue of ¥47,353m and basic earnings per share of ¥25.83, feeding into trailing twelve month earnings per share of ¥85.21. That earnings base underpins a P/E of 10.1x, which leaves the stock trading well below one widely used discounted cash flow fair value reference. Short-term price pressure meets a longer-term valuation gap, and that tension is the real story this season.
Like the earnings power at Meiwa but uneasy about the recent share price slip and valuation gap? Benchmark that setup against our 16 high quality undervalued stocks to see how other companies combine compressed P/E ratios with sturdier sentiment.
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥47,353m vs. ¥38,828m (up about 22%)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥1,004m vs. ¥983m (up about 2%)
- Basic EPS (Earnings Per Share, Q1 2027 vs Q1 2026): ¥25.83 vs. ¥24.46 (up about 6%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 2.0% vs. 2.3% (margin has deteriorated)
Earnings momentum softened even as Meiwa screens deeply undervalued on DCF. Ask Charlie what makes Meiwa look this cheap now.
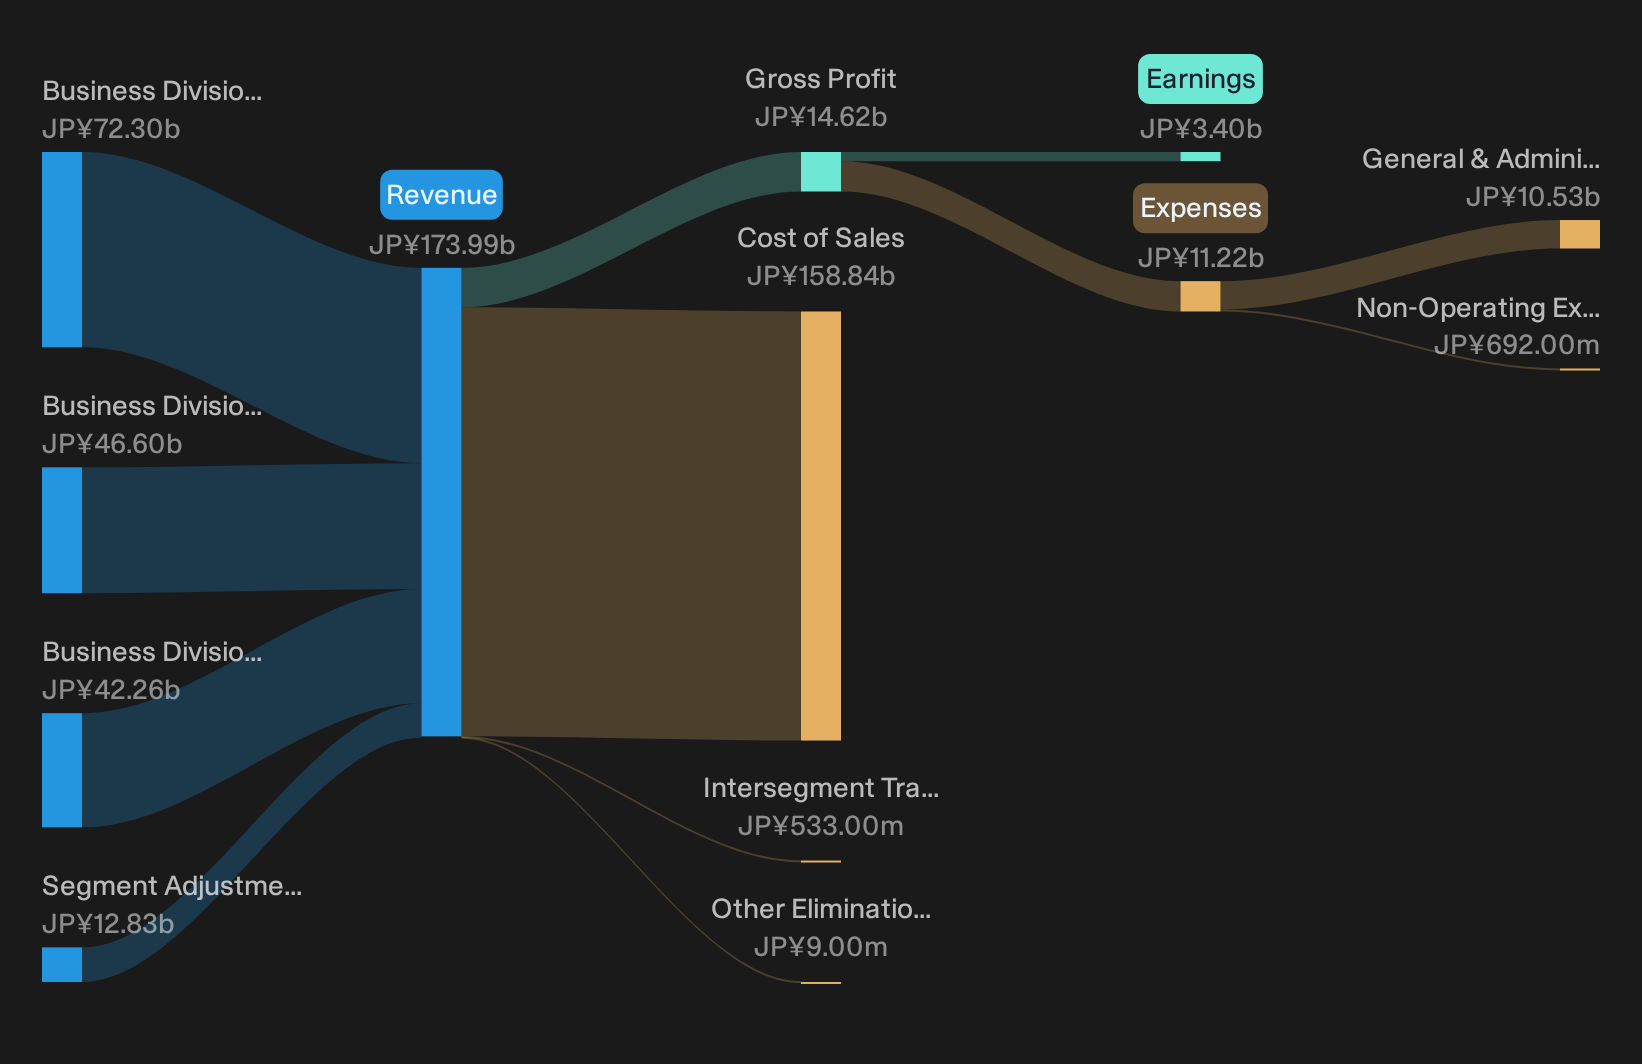
Revenue Upswing Keeps Meiwa’s Growth Story Intact
For anyone leaning optimistic on Meiwa, the top line does some heavy lifting. Q1 2027 revenue of ¥47,353m compares with ¥38,828m a year earlier, which points to solid demand across its materials and trading activities. Earnings per share also moved up from ¥24.46 to ¥25.83, so higher volume is at least converting into slightly better profit per share. Net income excluding extra items barely shifted, yet the combination of stronger sales and incremental EPS supports a view that the diversified platform can still grow without stretching the balance of risk and reward.
Margin Squeeze Leaves Room For a Cautious View
The bearish angle on Meiwa finds more support in profitability than in growth. Trailing net profit margin slipped from 2.3% to 2.0%, even with higher quarterly revenue and a small lift in EPS. That pattern fits worries about thin spreads in trading style businesses and sensitivity to input costs across chemicals, resources and petroleum products. Recent share price pressure over the past month and week adds to the sense that investors are treating the weaker margin profile with care, even though earnings have not fallen sharply in absolute yen terms.
After thin net margins and recent share price weakness, are these pressures isolated or early signals of deeper issues? Review the full risk analysis for Meiwa which shows 1 important warning signHunt For Mispriced Earnings Power
Meiwa highlights how a resilient profit base can coexist with a weaker share price. The real opportunity is spotting stocks that could be undervalued before fresh information prompts investors to reassess them.
- Company 1 - 42% below our estimate - builds no-code workflow tools teams adopt when email threads and spreadsheets limit collaboration.
- Company 2 - 39% below our estimate - manages virtual creators that advertisers hire for branded events, digital campaigns and fan monetisation.
- Company 3 - 44% below our estimate - extends long-standing regional banking ties into leasing, cards and fee businesses as clients seek bundled services.
Three companies from the same screener. Open all 16 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com