


- Cavco Industries reported second quarter fiscal 2027 sales of US$656.38 million and net income of US$55.44 million, with basic earnings per share from continuing operations of US$7.22.
- The business paired record shipments and revenue with orders that continued to outpace deliveries, resulting in a much larger backlog supported by demand for workforce housing tied to remote data center projects.
- The focus now turns to how Cavco Industries' record shipments and expanding backlog could reshape the existing investment narrative.
Cavco Industries Investment Narrative Recap
To own Cavco Industries, you need to be comfortable with a simple idea. The business depends on converting strong demand for factory built and workforce housing into healthy margins, even while tariffs, higher input costs and pricing pressure keep pushing on profitability. The latest quarter shows that shipments, data center related demand and backlog are all moving in the right direction.
The key short term catalyst remains execution on this order book as new facilities and plant upgrades come online. The biggest risk is that cost inflation, tariff exposure and integration expenses repeat the recent pattern of margin compression, which would blunt the benefit of higher volume. The new numbers do not remove that risk.
The most relevant update is Cavco Industries’ second quarter fiscal 2027 report, where sales reached US$656.38 million and net income was US$55.44 million, with basic EPS from continuing operations of US$7.22. These figures sit alongside prior six month results that showed higher revenue but lower net income compared with the same period a year earlier.
For you as a shareholder, that mix keeps the focus squarely on whether management can offset tariffs and higher SG&A with American Homestar synergies, better utilization and the growing Financial Services contribution. The earnings release provides fresh data on that trade off, but it still leaves execution risk around margins, especially if cost pressures persist while Cavco Industries ramps capacity.
Cavco Industries' current analyst narrative points to revenues of US$2.9b and earnings of US$242.3 million by 2029, based on an assumed 8.1% yearly revenue growth rate. That compares with earnings today of US$181.2 million. This implies an earnings increase of about US$61 million by the 2029 forecast year if those projections play out.
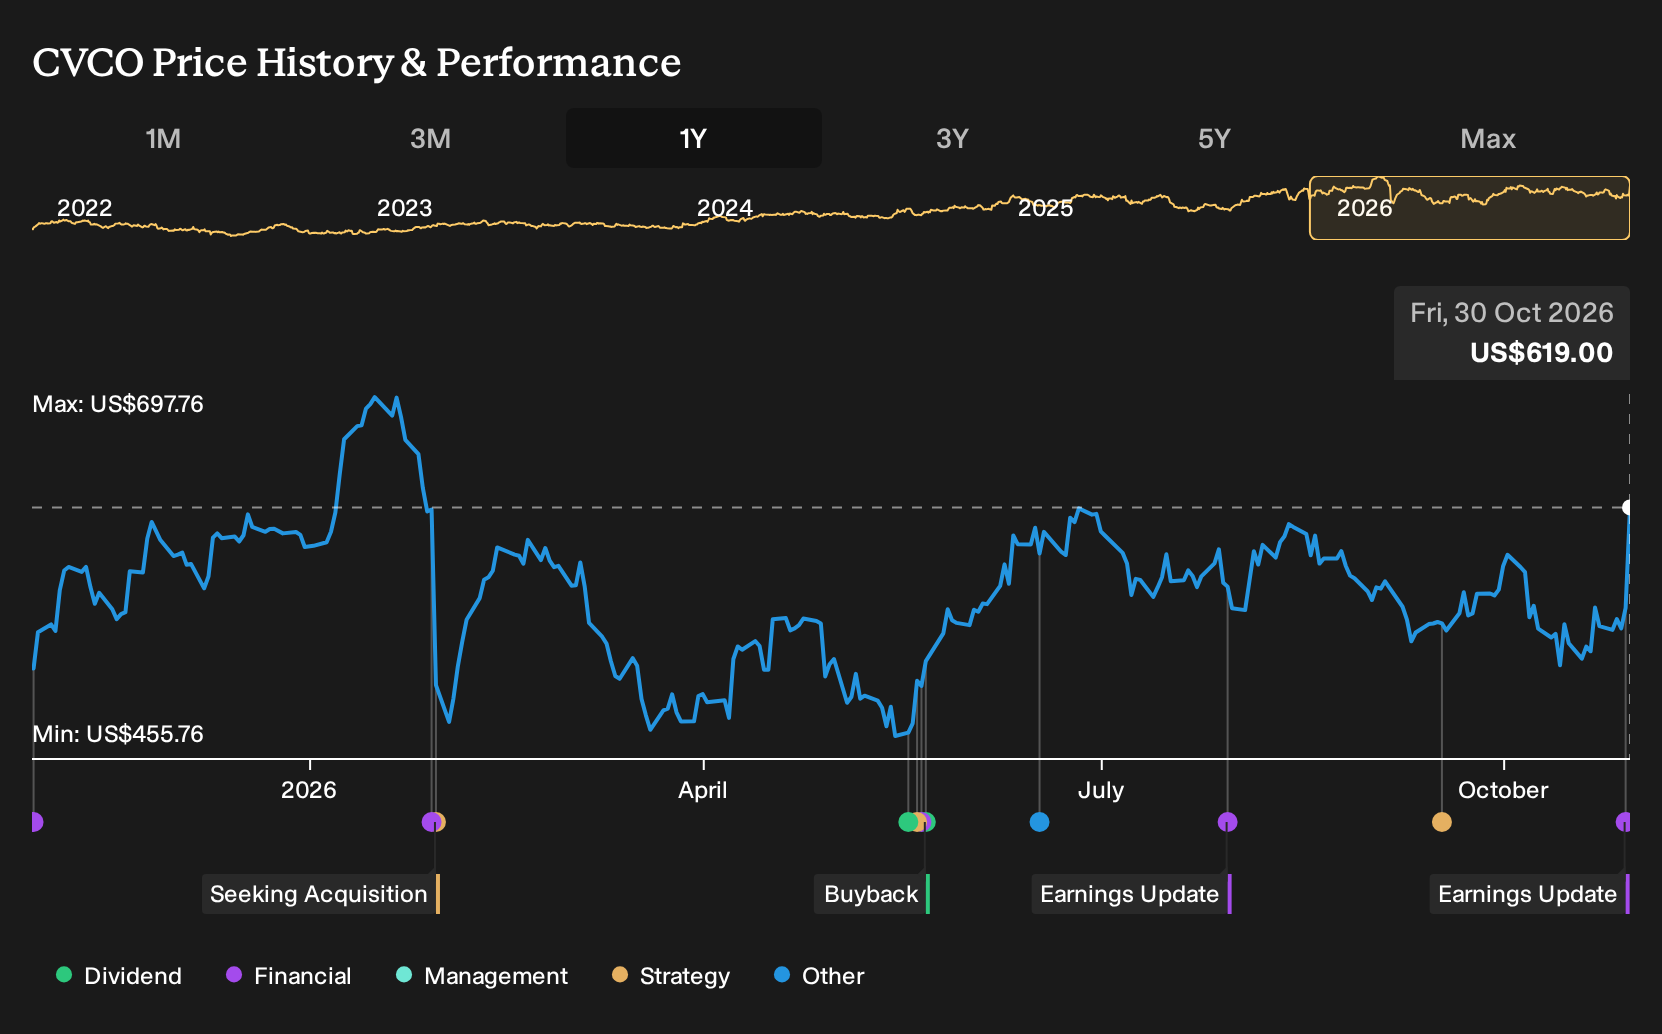
Uncover how Cavco Industries' fair value indicates a 7% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between roughly US$634 and US$665, which already span a meaningful price gap for Cavco Industries. Those private investors are reacting to older data. You now have more recent information on tariffs, margin pressure and backlog growth, so you can use it to test their assumptions and explore more viewpoints.
Explore another Cavco Industries fair value estimate, including one that suggests it could be worth just $634.09.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns seldom come from following the herd, so consider trusting your own analysis.
- A great starting point for your Cavco Industries research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Cavco Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cavco Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cavco Industries?
If Cavco Industries has sharpened your thinking about housing, capital cycles and execution risk, use that momentum to widen your watchlist. The Simply Wall St Screener lets you scan for stocks that match your risk tolerance and preferred business profiles in a few quick passes.
- For investors who care about resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions without stretching their finances.
- If you want potential value on your side, filter for companies that pair quality with attractive pricing by running a 33 high quality undervalued stocks that might warrant a closer look.
- Income focused investors can focus on cash returns by zeroing in on a curated 5 dividend fortresses that combine yield with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com