


Why Fabege stock is back in focus
Fabege (OM:FABG) drew fresh attention after reporting third quarter 2026 results, with net income of SEK 700 million and basic earnings per share of SEK 2.23 from continuing operations.
Despite the strong third quarter report, Fabege’s recent trading tells a different story, with the share price down about 15% over the past 90 days and the year to date share price return falling roughly 20%, while the 5 year total shareholder return has declined about 51%, pointing to momentum that has weakened rather than built.
Spot potential rebounds and other beaten-down real estate plays by scanning our hand picked list of 204 high quality undervalued stocks.Fabege now trades around SEK 64.5 while analyst and intrinsic value estimates cluster higher. Is this just a value gap on paper, or the start of a genuine reset in what the stock is worth?
Most Popular Narrative: 13% Undervalued
On the current narrative, Fabege is priced below an estimated fair value of about SEK 74, compared with the SEK 64.5 last close. This puts the focus squarely on whether that discount reflects temporary pressure or something more structural in Stockholm offices.
Fabege's concentrated portfolio in prime Stockholm locations positions it to benefit from ongoing urban migration and population growth, supporting future increases in occupancy rates and rental income as office demand slowly recovers (impact: revenue, margins).
The company's strong commitment to sustainable, certified properties, including new energy initiatives and a refreshed green finance framework, makes its assets more attractive to ESG-conscious tenants and investors, which could enable higher occupancy, rental pricing power, and lower long-term vacancy (impact: revenue, NAV growth).
See why 2 investors see Fabege as 13% undervalued.
Result: Fair Value of SEK73.97 (UNDERVALUED)
Still, risks to the Fabege story are clear, with Stockholm office weakness and declining property values both capable of undermining rental income and equity.
Find out about the key risks to this Fabege narrative.
Another View on Fabege’s valuation
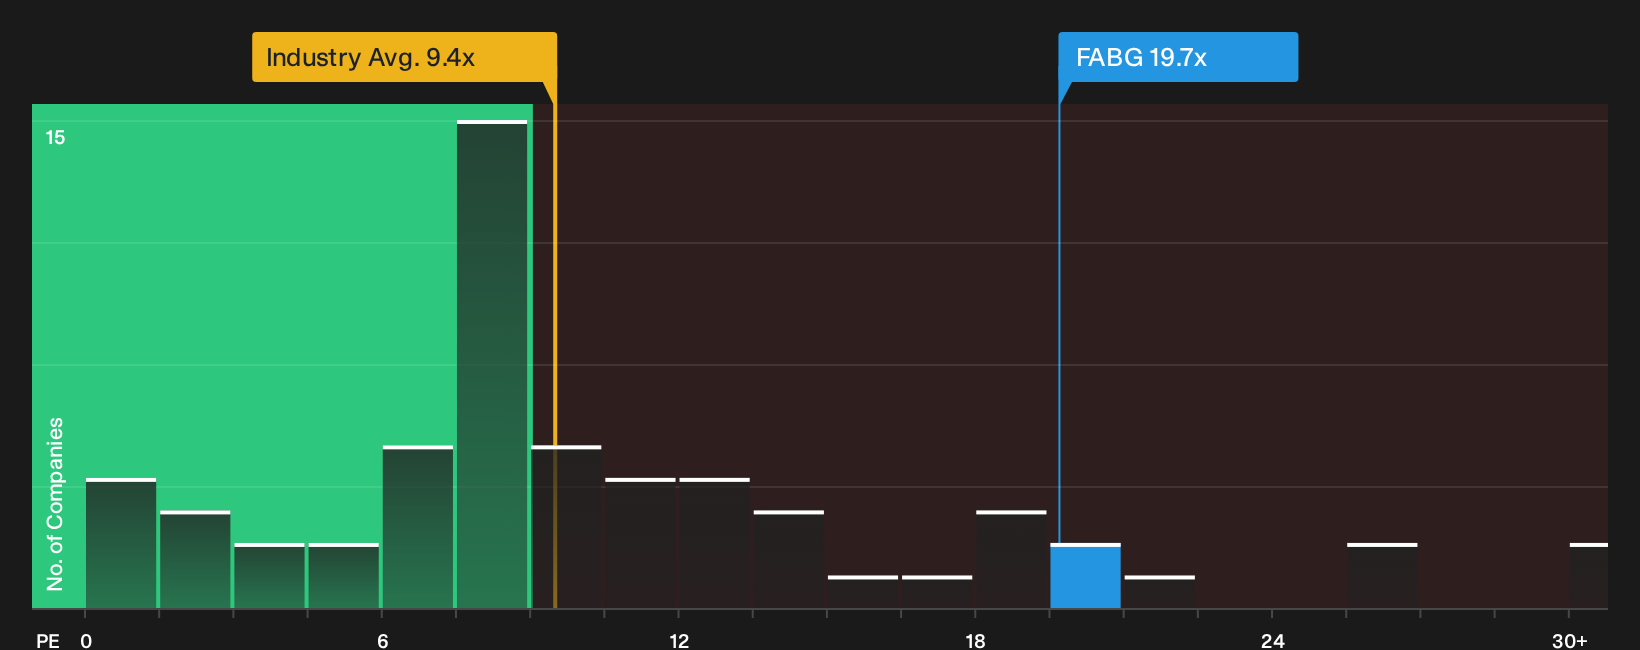
The fair value narrative paints Fabege as roughly 13% undervalued against a SEK 73.97 estimate. The market’s own P/E story is very different. At 19.7x earnings, the stock trades at more than double the Swedish real estate sector on 9.4x and well above peer averages near 11.7x.
That premium also sits slightly above a fair ratio of 19.4x that the market could gravitate toward over time. This leaves less room for error if forecasts miss or sentiment weakens again. The real question for you is whether that kind of valuation gap feels like a cushion or a warning sign.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the cautious tone and the upside case around Fabege? Take a moment to weigh both sides and stress test the numbers for yourself with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Fabege?
You have seen how complex a single story like Fabege can be, so consider spreading your research across a few fresh ideas that match your own risk and income goals.
- Target potential mispricings by scanning a curated pool of companies on our value hunt with the 204 high quality undervalued stocks.
- Explore income-focused opportunities by reviewing businesses with solid payout profiles using the 222 dividend fortresses.
- Reduce portfolio stress by filtering for sturdier balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals (199 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com