


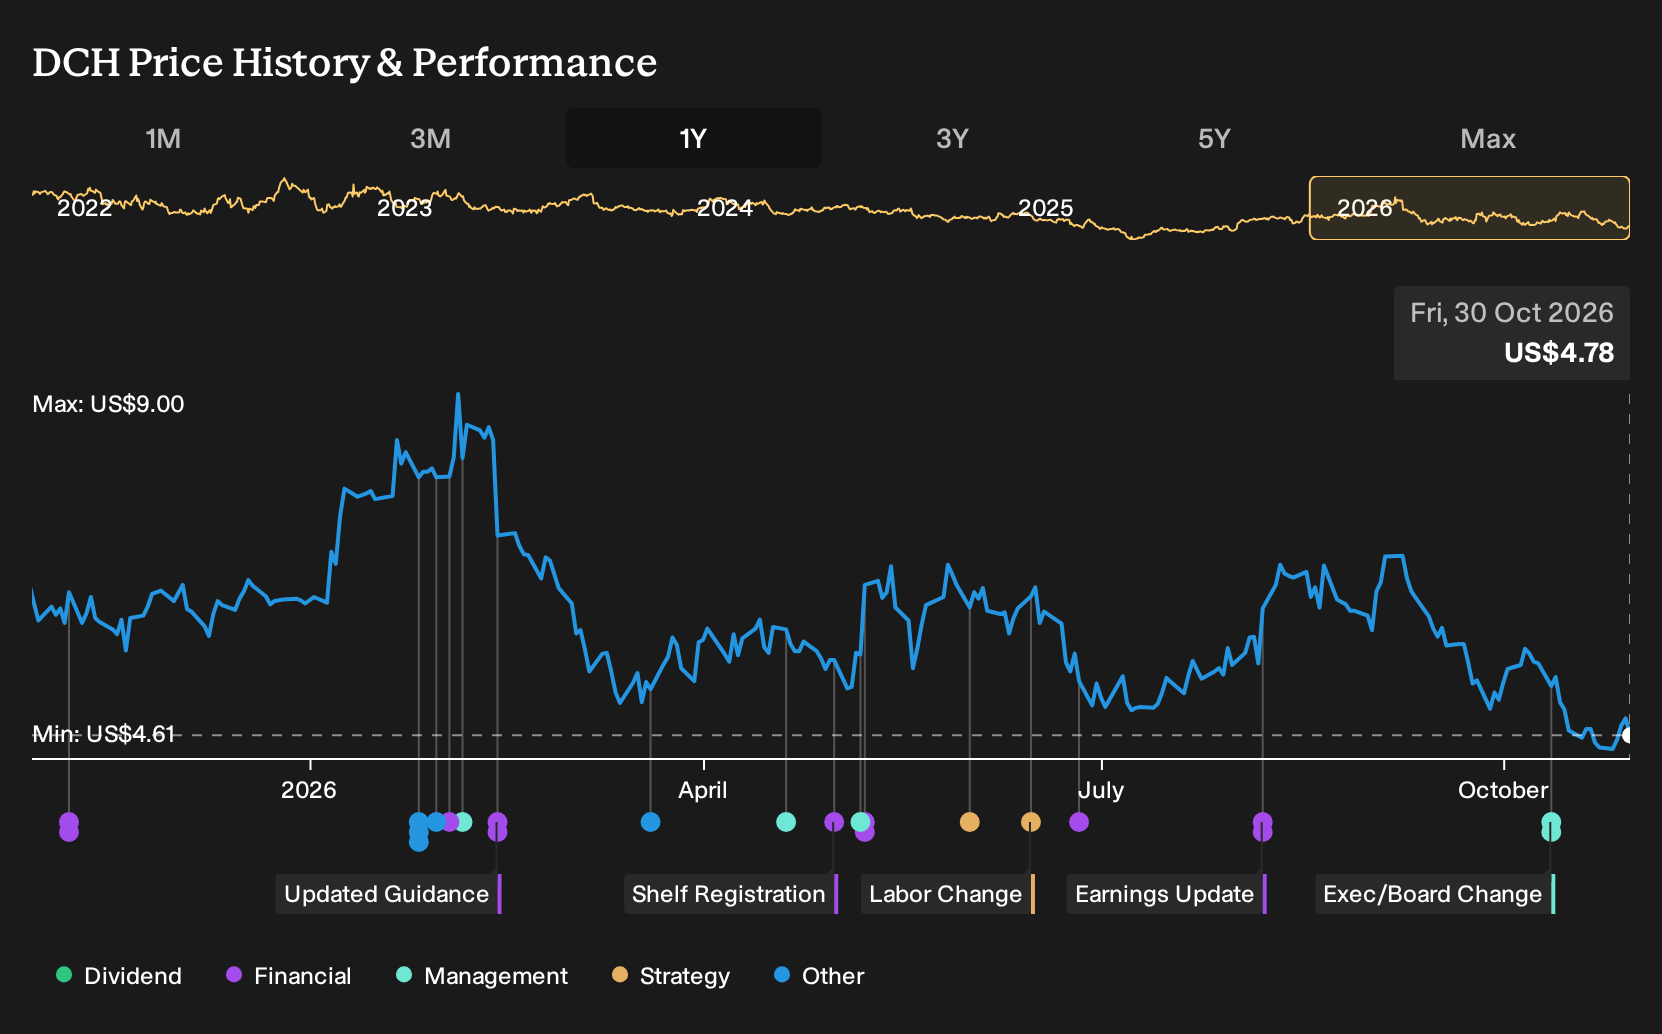
- Dauch is approaching its September 2026 quarter report, with Wall Street expecting earnings to decline year on year even though revenue is projected higher. This reflects operational pressure on profitability despite top line support.
- An interesting angle is that Dauch has recently delivered four straight earnings beats, yet analysts still cut EPS estimates into this release. This points to concern about how effectively the cost and productivity program is flowing through to reported profits.
- We will look at how Dauch's investment narrative, centered on execution and cost synergies, is tested by these lowered earnings expectations.
Compare how Dauch's earnings setup stacks against other potential ideas by scanning our hand picked list of 19 high quality undiscovered gems.
Dauch Investment Narrative Recap
To own Dauch, you need to believe the larger driveline and metal forming platform can turn its US$8.2b revenue base into consistent earnings and cash generation as integration and cost work mature. The latest guidance reset on near term earnings expectations points more to timing on profitability than to a change in what the business actually does.
The key short term catalyst is still execution on the cost synergy and productivity program, especially as management targets US$300 million of run rate savings. The biggest risk remains operational pressure from customer concentration and higher labor, energy and logistics costs. The recent earnings setup does not materially change that risk profile.
The most relevant recent update is the shift in expectations around the September 2026 quarter. Wall Street now looks for earnings to decline year on year even as revenue is projected higher. That puts a sharper spotlight on how effectively Dauch is converting volume and mix into profit while the integration work continues.
This setup affects near term catalysts because the cost synergy story is being tested right as analysts turn more cautious on earnings. For you, the question is whether the multi year savings plan, the quoting pipeline above US$2b, and the SDS joint venture contribution can offset the pressures from customer concentration and a still leveraged balance sheet over time.
Dauch's narrative projects US$12.2b revenue and US$272.6 million earnings by 2029. This assumes 14.1% yearly revenue growth and an earnings increase of about US$436 million from a loss of US$163.5 million today.
Uncover how Dauch's fair value indicates a 79% potential upside to its current price, which could narrow quickly as sentiment resets.
Exploring Other Perspectives
For a different angle on Dauch, focus on the bullish catalyst around deleveraging and free cash flow. The most optimistic analysts were penciling in US$12.3b of revenue and US$289.2 million of earnings by 2029, with a higher P/E assumption. That is far more upbeat, and this earnings news may push those storylines to evolve.
Explore another Dauch fair value estimate, including one that suggests as much as 205% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dauch research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dauch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dauch's overall financial health at a glance.
Looking For More Investment Ideas Beyond Dauch?
If the Dauch story has sharpened your thinking on risk, balance sheets, and earnings power, it can help to line that up against other opportunities using the Simply Wall St Screener. You can filter for exactly the type of profile you want, then compare how each stock stacks up on the same metrics you are using here.
- Prefer companies that look mispriced on quality fundamentals and valuation together, so you are not just chasing cheap for the sake of it? Then start with 33 high quality undervalued stocks.
- If capital protection matters more than big swings in either direction, focus on resilient businesses using the 29 resilient stocks with low risk scores.
- When a rock solid balance sheet is non negotiable and you want fewer surprises in stressed conditions, build your shortlist from the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com