


- Coloplast has opened its largest manufacturing facility in Felgueiras, Portugal, a two floor 50,000 m2 site that represents around €100 million in investment and is already producing continence care products with a workforce of more than 300 people.
- The Portugal plant expands Coloplast’s global manufacturing network and is intended to provide sufficient capacity to support its 2030 strategy targets without adding further sites. This highlights how the company plans to handle demand and capital spending over the coming years.
- We will now look at how Coloplast's enlarged Portuguese manufacturing capacity could influence the broader investment narrative around its growth ambitions.
Spot similar capacity driven growth stories by scanning our hand picked list of solid balance sheet and fundamentals (199 results), which, like Coloplast, are investing heavily while keeping financial foundations in focus.
Coloplast Investment Narrative Recap
For a shareholder in Coloplast, the core belief is that chronic care, continence and ostomy products keep compounding as a steady, global demand story while the firm improves efficiency enough to support its margin ambitions. The Portugal factory fits that view. It adds capacity to back the 2030 plan without more sites, so it mostly reinforces, rather than changes, the near term thesis.
The key short term swing factor still sits in execution on U.S. growth and stabilising Biologics after reimbursement changes, not in Portuguese bricks and mortar. The large Kerecis impairment, softer wound dressing trends and already compressed 9.7% net margin leave less room for error if demand, pricing or mix weaken.
The most relevant recent development around this expansion is Coloplast’s push to reorganise into distinct Chronic Care and Acute Care units with dedicated R&D for Chronic Care. That shift is meant to tighten the link between product design and manufacturing, so a high volume site in Portugal plugs directly into the new structure.
For you as an investor, the combination of a larger, modern plant and a clearer organisational split shapes how catalysts might play out. Efficiency gains and product rollouts such as SenSura Mio and Luja catheters rely on this network working smoothly. At the same time, risks like high debt, weaker margins and pressure in European wound care could matter more if utilisation or case mix fall short of expectations.
Coloplast Forecasts Behind The Factory Story
Coloplast's narrative projects DKK 34.3 billion revenue and DKK 6.6 billion earnings by 2029. That rests on analysts assuming 6.5% yearly revenue growth and an earnings increase of DKK 3.8 billion from DKK 2.8 billion today.
Uncover why Coloplast's fair value indicates a 4% potential downside to its current price, leaving little room for error.
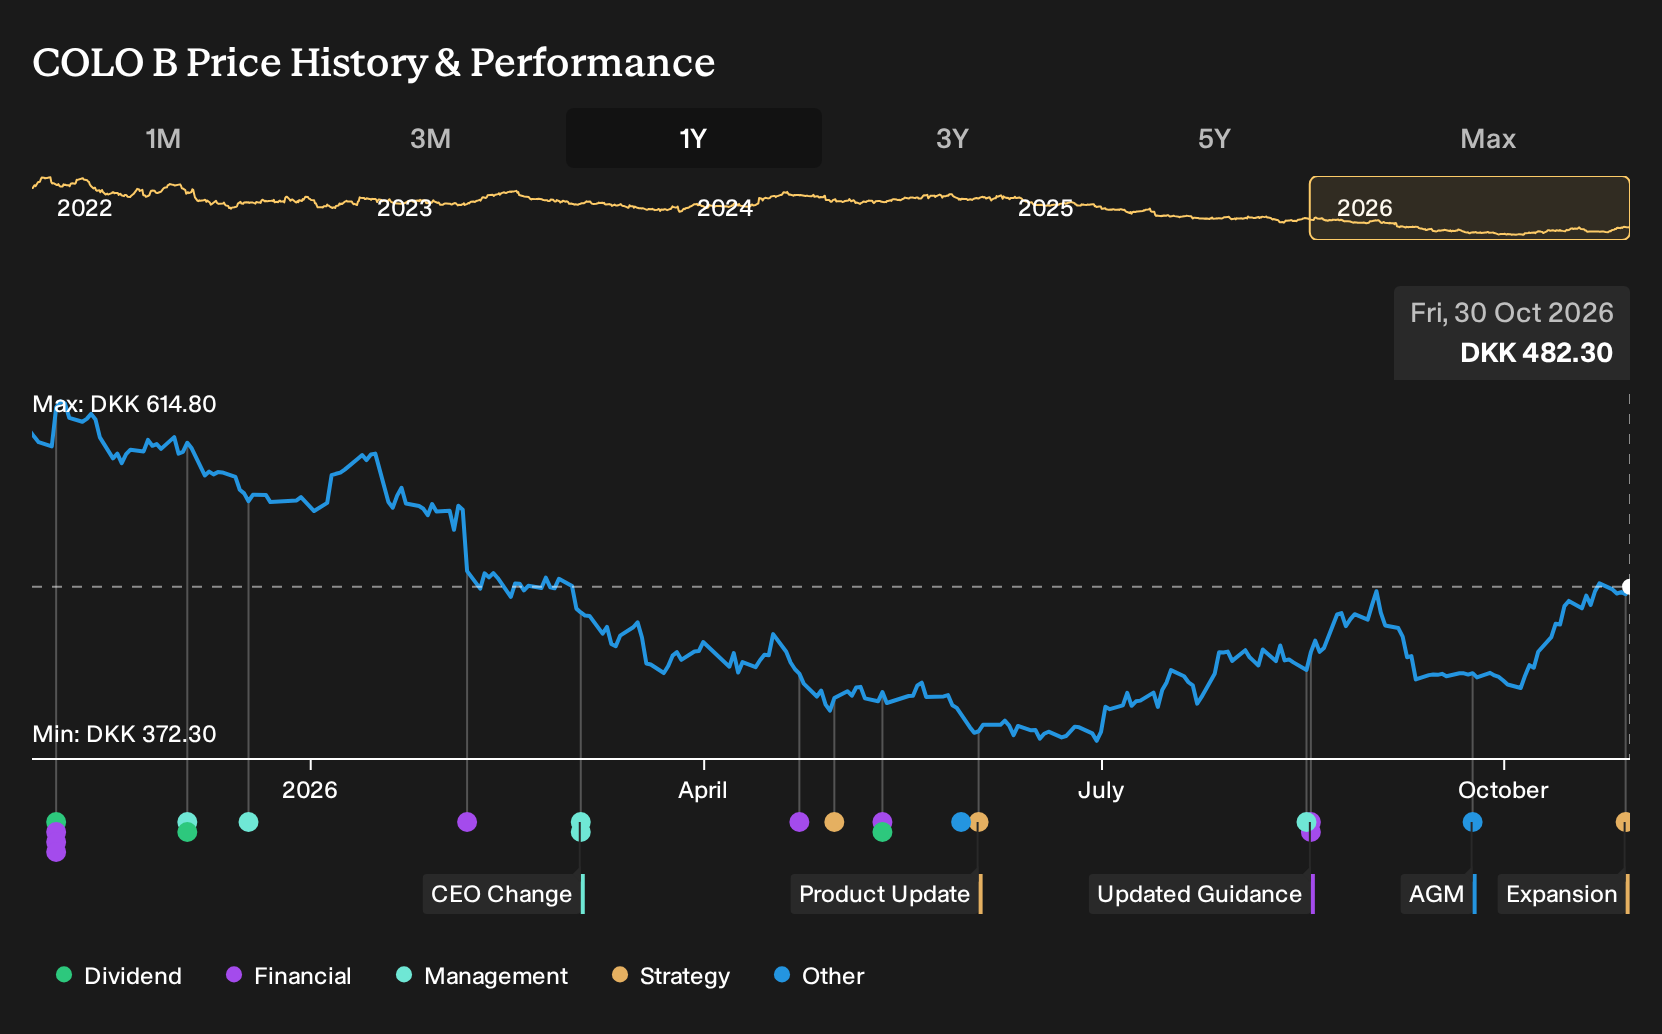
Exploring Other Perspectives
One alternative view says the real swing factor for Coloplast is not the Portuguese capacity at all, but raw material inflation squeezing that 26% EBIT margin. The most pessimistic analysts were already pencilling in DKK 33.6b revenue and DKK 5.8b earnings for 2029. You can treat this new plant as a fresh test of those earlier assumptions.
Explore 4 other Coloplast fair value estimates, including one that suggests it could be worth just DKK 461.62.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Coloplast research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Coloplast. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coloplast's overall financial health at a glance.
Looking for more investment ideas beyond Coloplast?
If the Coloplast story has sharpened your view on capacity, margins and balance sheets, use that same lens to scan a wider set of opportunities with the Simply Wall St Screener.
- If you want potential mispricing with quality in mind, start with companies flagged as 204 high quality undervalued stocks that already show solid fundamentals.
- For steadier cashflow profiles, consider businesses screened as 218 resilient stocks with low risk scores where balance sheets and volatility scores point to resilience first.
- If you prefer under followed ideas, widen your watchlist with a curated set of 614 high quality undiscovered gems that pair strong financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com