


Amentum Holdings (AMTM) just expanded its footprint at Colorado Springs' Catalyst Campus for Technology and Innovation, increasing its proximity to key defense and space programs and drawing investor attention to how this move relates to the stock’s recent performance.
Recent trading shows that Amentum Holdings has enjoyed a strong 30 day share price return of 20.56%, even though the year to date share price return is down 28.25% and the 1 year total shareholder return is down 2.41%. This may indicate that momentum is starting to rebuild after a weaker stretch.
Scan how Amentum Holdings compares with other contractors riding similar defense and space momentum by reviewing our curated set of 41 power grid technology and infrastructure stocks
Bulls see Amentum Holdings using the Colorado Springs expansion and recent momentum as a springboard, while bears point to the longer stretch of weaker returns. Which story do the current valuation numbers support?
Most Popular Narrative: 26.1% Undervalued
Amentum Holdings closed at $21.87, while the most widely followed narrative pegs fair value at about $29.58, so the story hinges on whether investors agree with the growth and profitability path baked into that gap.
Ramp up of large, long duration awards such as the U.S. Space Force Range contract, Sellafield remediation and NASA Cosmos is set to convert the current $47 billion backlog and $20 billion of pending bids into higher run rate revenues and improved operating leverage, supporting sustained earnings growth.
See why 11 investors see Amentum Holdings as 26% undervalued.
The narrative uses an 8.72% discount rate on those projected cash flows and assumes earnings can build from $204.0m today toward $532.2m by around 2029, with profit margins rising from 1.4% to about 3.5%. That mix of higher earnings power and a lower future P/E of roughly 17.6x is what underpins the fair value estimate near $29.58, compared with the current $21.87 share price.
Analysts behind this framework are effectively asking investors to decide whether relatively modest forecast revenue growth of about 2.2% a year, combined with margin improvement and a $47b backlog, is enough to justify that valuation, especially given Amentum Holdings’ recent share price underperformance versus both the US Professional Services industry and the broader US market. The discount to the narrative fair value suggests expectations are still cautious around execution risk, board turnover and interest coverage, even though earnings growth over the past year has been very strong and is forecast to remain high.
Result: Fair Value of $29.58 (UNDERVALUED)
Still, the narrative around Amentum Holdings only holds if large, complex contracts avoid cost overruns and if government funding disruptions do not delay that US$20b bid pipeline.
Find out about the key risks to this Amentum Holdings narrative.
Another View: What Amentum Holdings’ P/E Is Telling You
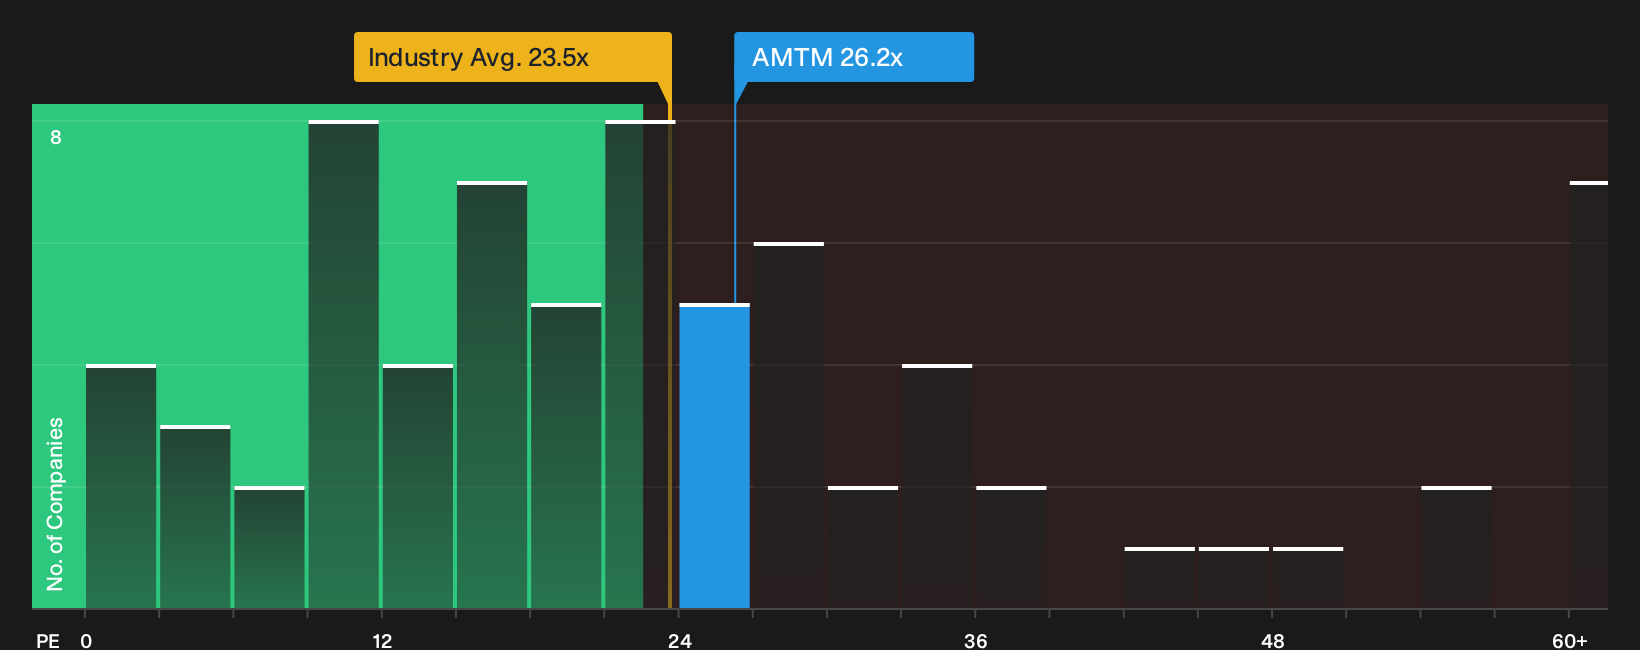
The first storyline paints Amentum Holdings as about 26% undervalued on future cash flows, yet the current 26.2x P/E is higher than both the US Professional Services industry at 23.5x and peers at 23x, while sitting almost exactly on a 26.4x fair ratio. That mix of premium pricing and near fair ratio means there is less of an obvious bargain and more debate about how much execution risk you are truly being paid for.
To see how this earnings based view stacks up against the cash flow narrative and whether the current P/E leaves room for error, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism and concern sit side by side in the Amentum Holdings story, so move quickly to test the data for yourself and weigh both sides using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Amentum Holdings?
If you only stop at Amentum Holdings, you risk missing other opportunities that align better with your goals, risk appetite, and time horizon.
- Target resilient balance sheets by scanning companies on our list of solid balance sheet and fundamentals (24 results) that pair financial strength with dependable fundamentals.
- Spot potential mispricing by reviewing the 33 high quality undervalued stocks that combine quality metrics with appealing valuations.
- Lock in reliable income streams by assessing payout opportunities across our 5 dividend fortresses that focus on higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com