


Dividend, earnings and M&A activity put Pool in focus
Pool (POOL) has attracted fresh attention after affirming a quarterly dividend of US$1.30 per share alongside third quarter results, full year 2026 earnings guidance and comments on a more active acquisition pipeline.
The confirmed payout, scheduled for November 25 with an ex date of November 10, sits alongside a mix of operating updates that provide more detail on how cash is being used and how management sees the rest of the year.
Pool shares have recently picked up momentum, with a 30 day share price return of 27.26% and a 90 day gain of 10.92%. However, the year to date share price is still down 10.33%, and the 5 year total shareholder return has declined 57.22%.
Scan beyond Pool to see how it compares with other companies showing strong momentum and cash generation in our hand picked 33 high quality undervalued stocks.
Pool has just delivered a sharp rebound in the share price while earnings guidance, dividends and M&A plans stay in focus. After this kind of swing, does the current valuation still tilt the risk reward toward buyers?
Most Popular Narrative: 2% Undervalued
Pool closed at $205.99 against a widely followed fair value estimate of $209.50, a small gap that still sparks debate over how much earnings power and cash returns are already in the price.
The main thing that has to go right is that Pool continues to drive higher POOL360 adoption and growth in proprietary and private label products so that efficiency gains and mix improvements can offset freight costs, customer mix headwinds and softness in Horizon.
The completion of this tranche means Pool has finished the full repurchase authorization tied to the 2012 buyback announcement. This may influence how you evaluate the company’s future capital return capacity.
See why 28 investors see Pool as 2% undervalued.
Result: Fair Value of $209.50 (UNDERVALUED)
Still, higher freight costs and weaker Horizon irrigation demand could pressure Pool if these margins and sales drags persist longer than analysts currently model.
Find out about the key risks to this Pool narrative.
Another view on Pool’s valuation
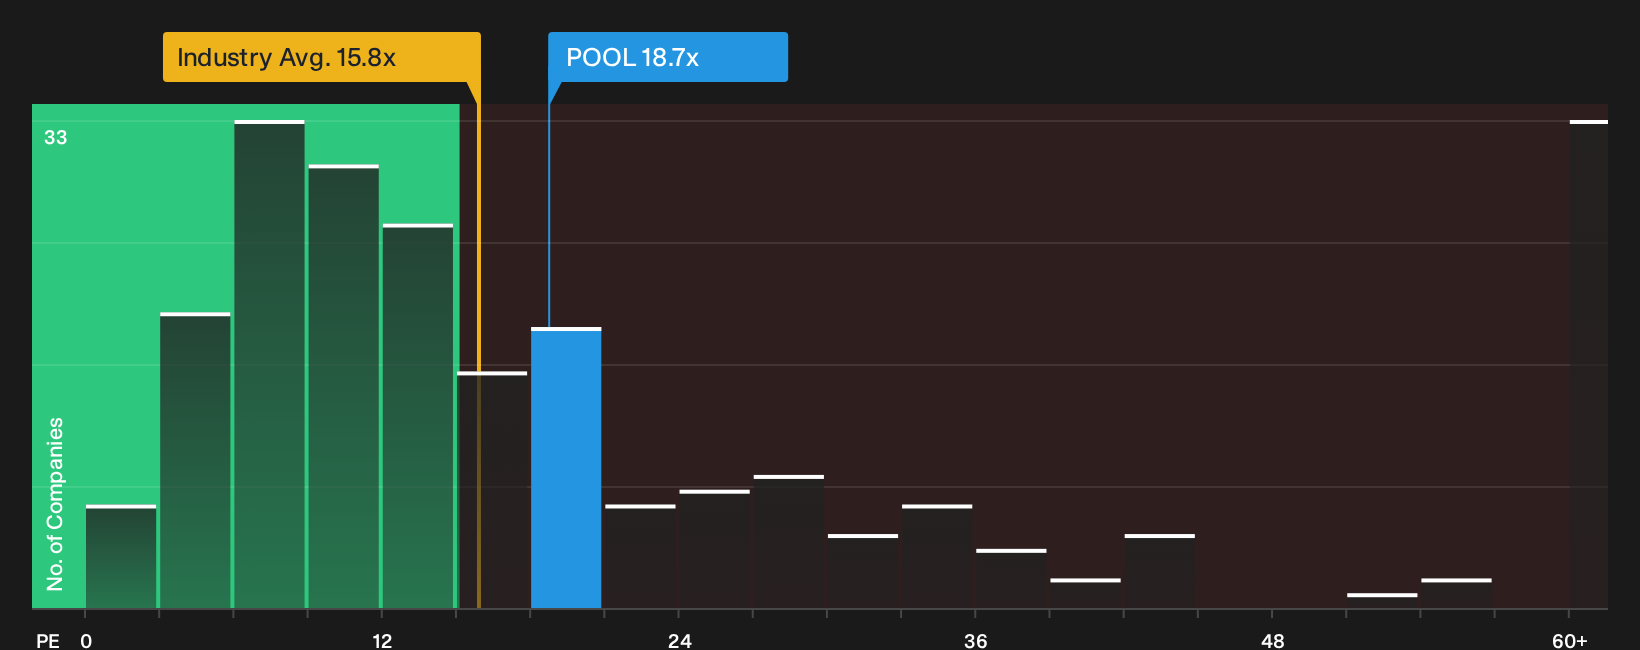
On cash flow math, Pool looks appealing. The SWS DCF model points to a fair value of $250.10, with the current $205.99 share price sitting below that estimate and implying a discount. Multiples tell a different story, with the stock on a P/E of 18.7x versus an industry average of 15.8x and a fair ratio of 13.7x, which suggests investors are already paying up. Which signal do you weigh more heavily?
See what the numbers say about this price in our valuation breakdown, then decide how comfortable you are with that P/E gap over time. See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how Pool’s valuation stacks up against peers, start with the relative P/E snapshot.
Next Steps
Mixed signals around Pool’s valuation and capital returns can feel messy, so move quickly to review the full picture and shape your own stance. The fastest way is to weigh both sides in our breakdown of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Pool?
Pool may be on your screen today, but your next opportunity could sit in a very different corner of the market. Do not leave that edge on the table.
- Start with resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) that highlight businesses built to handle tougher conditions.
- Hunt for overlooked potential by reviewing a focused list of 19 high quality undiscovered gems that pair strong financials with limited market attention.
- Stack your watchlist with quality at a sensible entry point by using a curated set of 33 high quality undervalued stocks that match solid cash generation with appealing pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com