


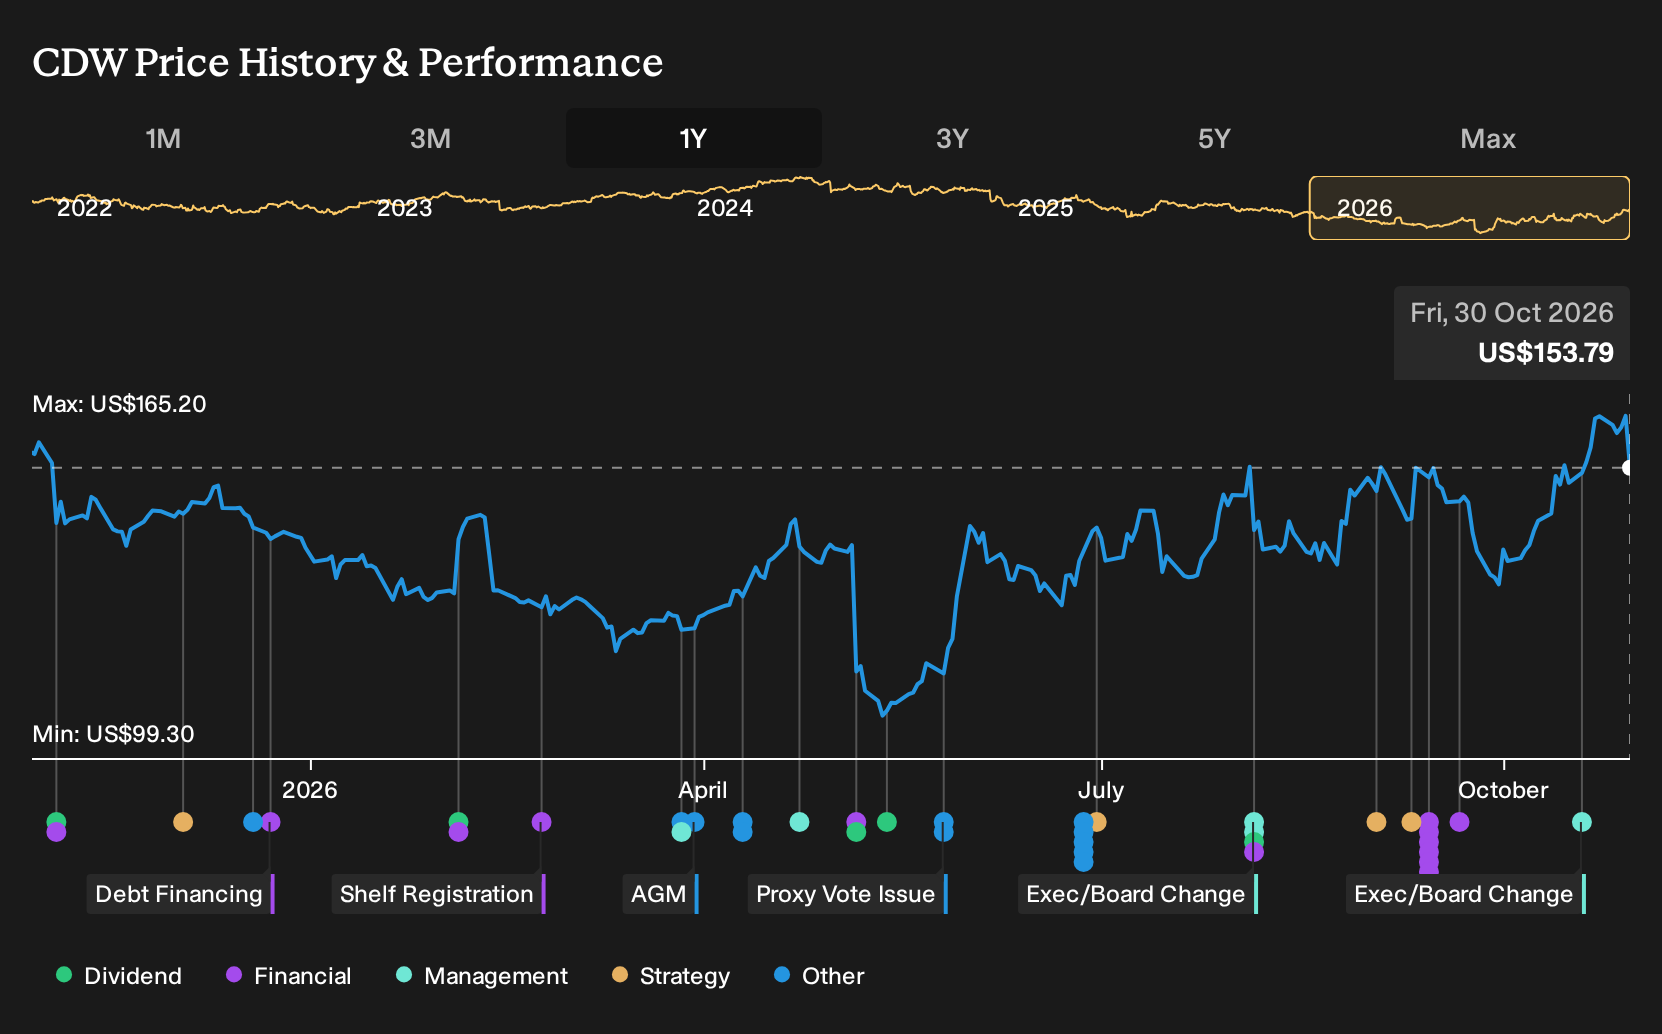
- CDW appointed Saranga (Sam) Balaji to its Board of Directors and Audit Committee in October 2026, adding decades of global technology, advisory, cybersecurity and governance experience from his tenure leading Deloitte’s consulting and advisory businesses.
- Investor interest is centering on CDW’s broad exposure to AI, cloud and cybersecurity infrastructure, where Balaji’s background in large scale digital transformation and complex partnerships aligns closely with the company’s full stack IT model.
- We will examine how CDW's investment narrative is influenced by its underowned IT infrastructure positioning and Balaji's deep AI and cloud leadership experience.
Compare CDW's AI, cloud and cybersecurity exposure with other potential infrastructure beneficiaries by scanning our curated list of 54 AI infrastructure stocks.
CDW Investment Narrative Recap
To own CDW, you need to believe the business can keep turning broad AI, cloud and security demand into steady infrastructure orders and, over time, a richer mix of software and services. The key near term swing factor is whether current hardware heavy activity and backlog convert cleanly into revenue without further pressure on gross margin or cash.
The biggest risk right now is that the shift toward higher value services remains slow, leaving margins and free cash flow below management’s targets while debt is still leaning on operating cash generation. The Balaji board appointment looks additive on oversight rather than a material short term catalyst.
The most relevant recent move alongside this board change is CDW’s Lovelytics data and AI acquisition, which brought in more than 600 specialists. That deal broadens CDW’s bench in analytics heavy projects where customers need help designing, deploying and then running AI workloads across hybrid infrastructure and multiple clouds.
Putting Lovelytics and Sam Balaji together provides a clearer view of where management is trying to lean. Bigger, more complex AI, cloud and cybersecurity projects could give CDW more opportunity to attach professional and managed services, which is important if hardware mix keeps pressuring gross margin and working capital and investors focus on cash conversion risk.
CDW Consensus Assumptions and Valuation Bridge
Analysts are effectively asking investors to underwrite a CDW path where revenue compounds at 4.0% a year, profit margins edge higher from 4.6% to 5.3%, and earnings move from US$1.1b today to US$1.4b by 2029. That profile leans on the idea that AI, cloud and cybersecurity demand can support steadier infrastructure spending, while a broader services mix and the Lovelytics acquisition help pull profitability higher even if hardware remains a heavy share of activity.
The earnings step up implied in those forecasts is not extreme in percentage terms, but it does assume cleaner cash conversion and better mix than CDW is showing in its recent numbers. Free cash flow conversion of 42% of non GAAP net income year to date in 2026 sits well below the 80% to 90% target range, largely because inventory has been built ahead of hardware projects. For the consensus path to hold, that working capital drag likely needs to ease so that higher earnings can translate more directly into cash that can fund debt reduction, buybacks and further AI focused capability build outs.
Valuation assumptions sit on top of that earnings and revenue bridge. At a consensus price target of US$158.67 and current price of US$128.16, the implied upside case uses US$26.5b of revenue and US$1.4b of earnings in 2029, paired with a P/E of 16.7x that is below the current US Electronic industry multiple of 30.3x. That framework effectively says investors are being asked to pay a lower multiple than the wider sector for a business that analysts think can grind out steady, if unspectacular, top line growth while lifting margins off a relatively low base.
CDW's narrative projects US$26.5b revenue and US$1.4b earnings by 2029. This framework assumes 4.0% yearly revenue growth and an earnings increase of about US$300m from the current US$1.1b base.
Uncover why CDW's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate story focuses on revenue risk if more IT budgets flow through cloud marketplaces instead of CDW. The most bearish analysts already pencilled in slower 3.2% annual revenue growth to about US$25.8b and a US$1.4b earnings figure by 2029 before this board appointment. Views clearly vary, so treat Balaji’s arrival as a fresh signal to compare several narratives rather than a final verdict.
Explore 4 other CDW fair value estimates, including one that suggests as much as 30% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CDW research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CDW. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CDW's overall financial health at a glance.
Looking for more investment ideas beyond CDW?
If CDW has sharpened your thinking about AI, infrastructure and cash generation, you can use that same lens to scan a wider set of opportunities with the Simply Wall St Screener.
- If capital preservation is near the top of your list, you could start with a basket of businesses that screen as more resilient by risk profile through the 29 resilient stocks with low risk scores.
- For investors who focus on balance sheet strength and steady fundamentals, you can filter for companies that pass stringent financial health checks using the list of solid balance sheet and fundamentals (24 results).
- If you are looking for potential mispricings backed by real cash generation, you may cast a wider net across quality companies trading below their estimated value via the 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com