


SK hynix has just come off a sharp share price swing, and the question now is whether the current valuation can be squared with what the business actually earns.
- The stock is down 23.5% over the past month, which puts fresh pressure on the idea that its present earnings power still justifies today's price.
- Recent reports of record revenue, very high operating margins and long term high bandwidth memory supply deals can all feed into how investors think about the durability and level of future profit streams.
- Your read on SK hynix is one view; the desks covering it have another. See what analysts think SK hynix's shares could be worth.
The issue now is whether the earnings that SK hynix is generating, and is expected to generate, are enough to support where the shares trade today.
Given how strongly AI and chip demand are shaping SK hynix's earnings story, it can help to compare this setup with other semiconductor plays by using the 54 AI infrastructure stocks.
Is SK hynix a Bargain on Earnings?
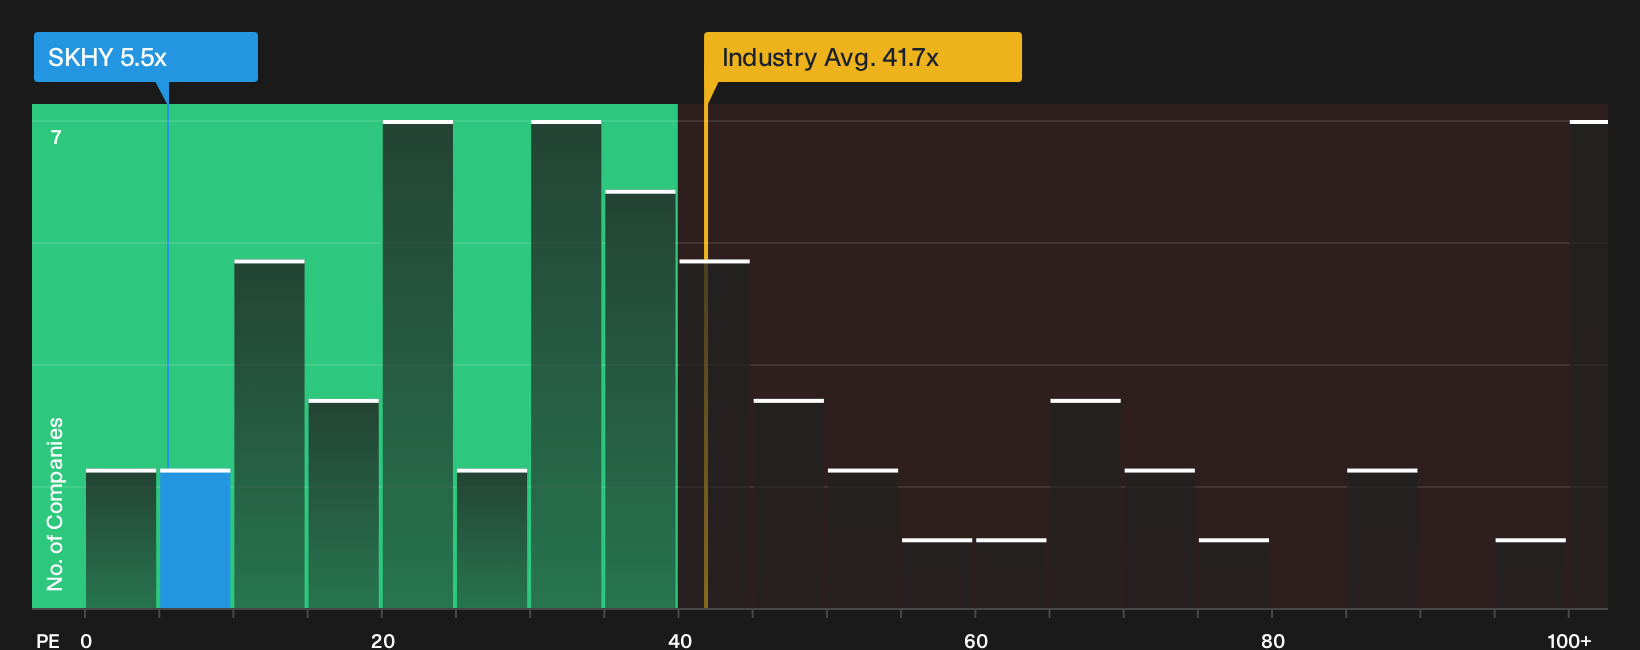
The P/E ratio suits SK hynix because recent earnings are the main driver of how investors are framing the story. On current numbers, the stock trades on a P/E of 5.5x, compared with about 41.7x for the wider semiconductor group and 51.4x across direct peers. That is a very wide gap, so the market is either heavily discounting the durability of the latest profit run or demanding a big margin of safety before paying up for those earnings.
Because SK hynix has just reported record Q3 revenue and very high operating margins, yet still changes hands at such a low multiple relative to chip peers, you need to decide whether those profits look repeatable enough to close some of that valuation gap or whether they belong to a single strong phase in a highly cyclical industry. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up exactly where the SK hynix valuation puzzle leaves off, by spelling out which future paths for revenue, margins and earnings would need to play out for the shares to be worth materially more or materially less than today, and they sit on Simply Wall St's Community page. Rather than a single multiple or model output, each narrative lays out its own fair value assumptions so you can compare those to SK hynix's reported numbers as they arrive.
One of the top community narratives on SK hynix: 60% undervalued
"CapEx will play a key factor over the next 5 years as the company attempts to scale to keep up with demand..."
Discover why this Narrative puts SK hynix at 60% undervalued.
One more piece of the SK hynix story investors often skip
Everything so far has focused on what SK hynix earns today, yet there is another lens that matters, which is how professional analysts currently map out this business a few years from now. Explore where analysts expect SK hynix to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com