


- Kinnevik now trades at a P/B of 0.7x versus an industry average of about 1.1x. This raises questions about how its private holdings and climate tech exposures are being reflected in the current market value.
- The gap between Kinnevik’s book value and its quoted equity price has sharpened focus on whether potential write downs in climate related investments and funding risks are fully captured in the current valuation.
- We will now look at how Kinnevik’s investment narrative is affected by the deepening discount to its reported net asset base.
Compare Kinnevik's deep discount to peers and pressure test your thesis against our hand picked list of 204 high quality undervalued stocks that also trade below what their balance sheets suggest.
Kinnevik Investment Narrative Recap
Kinnevik asks you to back a very specific idea. The group is essentially a listed portfolio of high growth, tech enabled assets in software, health care, fintech and climate transition. To stay invested, you need to believe those holdings can move toward profitable scale and that capital remains available to fund them without eroding value for existing shareholders.
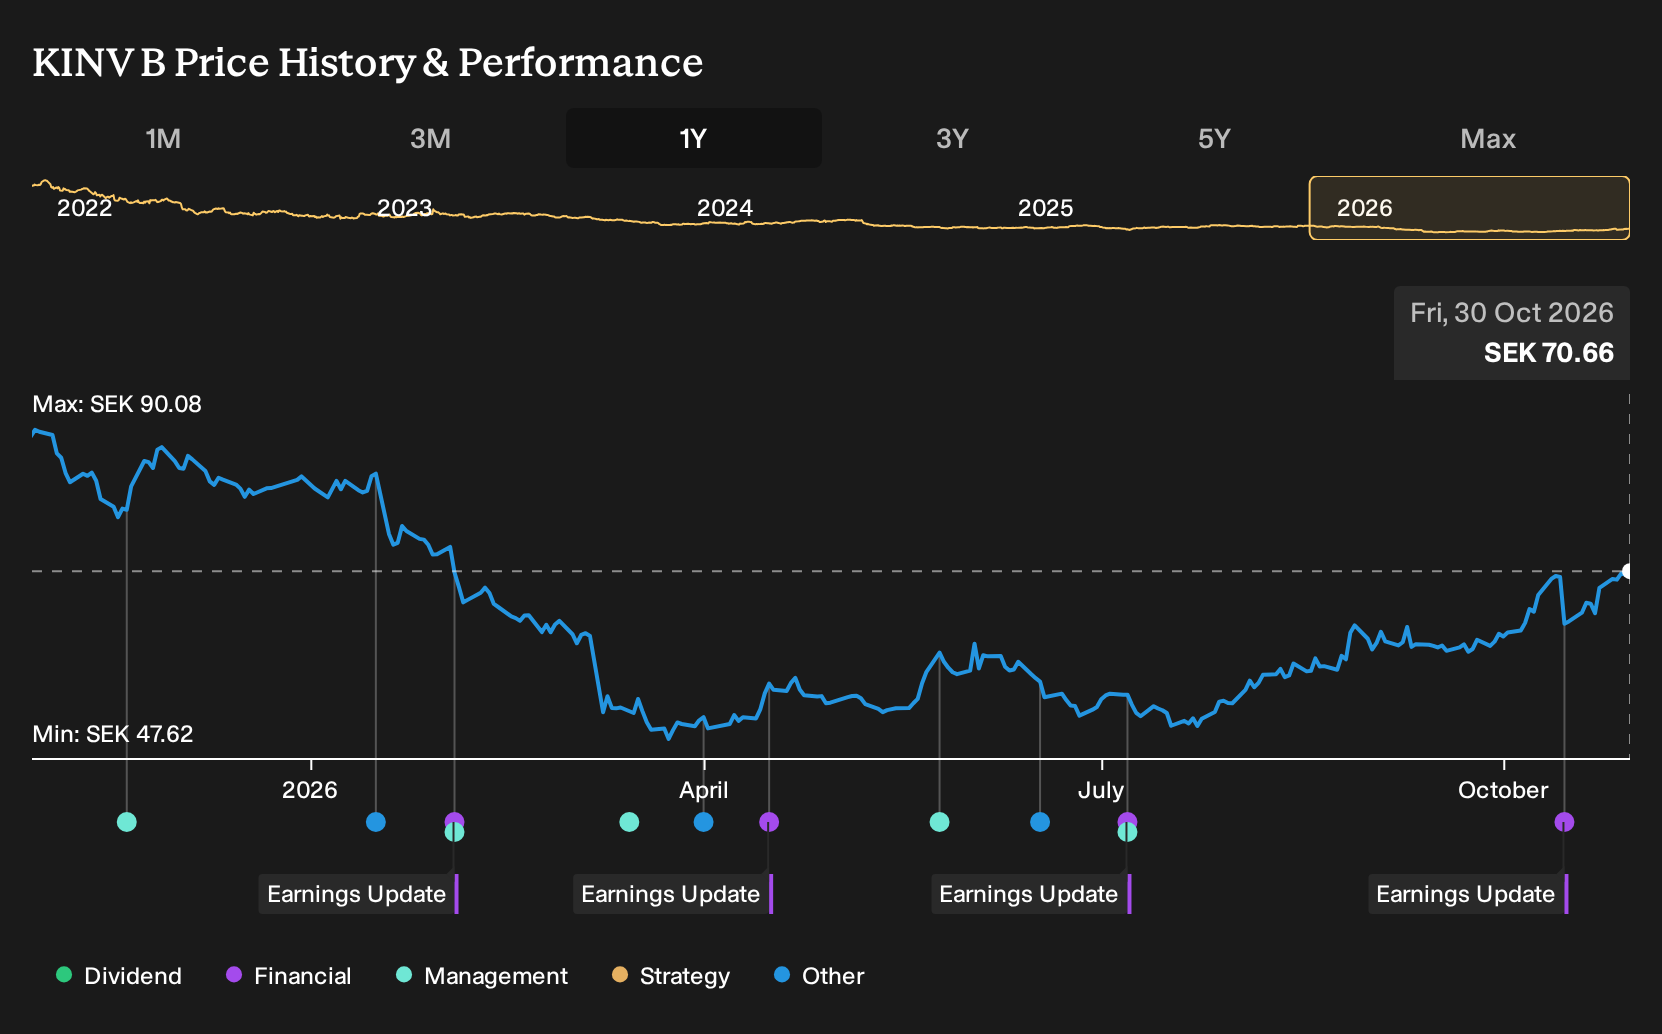
The sharp share price decline and 0.7x P/B ratio put the immediate spotlight on portfolio resilience and funding risk. The near term catalyst is progress in core assets such as Spring Health, Cityblock, Mews and TravelPerk that supports reported net asset value. The biggest current risk is further write downs in climate tech and other private holdings if funding or exit conditions weaken.
One of the most relevant data points around this debate is the forecast that Kinnevik’s earnings could grow about 87.4% per year and move into profitability within three years. That outlook ties directly into the discount to book value. The market is effectively testing whether those projections still hold for key unlisted investments.
If portfolio companies secure funding to breakeven and maintain contract momentum, especially in U.S. digital health and AI enabled software, Kinnevik has more room to let assets compound and potentially crystallise value through exits. If growth slows at Spring Health or Cityblock or execution slips at Mews, TravelPerk, Enveda or Aira, then the pressure on fair values and the share price discount can persist or deepen.
Kinnevik's current story rests on forecasts that revenues reach SEK 2.6b and earnings hit SEK 2.6b by 2028, off earnings today of SEK 124.0m. That setup assumes revenue expands at about 149.4% a year and requires an earnings increase of roughly SEK 2.5b from the current base.
Uncover why Kinnevik's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Kinnevik puts Oviva’s weight management rollout at the center of the story. The most optimistic analysts were pencilling in revenue growth of 153.8% a year and earnings of about SEK 2.7b by 2029 before this latest news. You can read that as a far more upbeat script that might shift as fresh information lands.
Explore 2 other Kinnevik fair value estimates, including one that suggests as much as 64% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your Kinnevik research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kinnevik. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kinnevik's overall financial health at a glance.
Looking For More Ideas Beyond Kinnevik?
Once you have a view on Kinnevik, it can help to set that against a wider watchlist of opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for very specific traits so you can build a shortlist that lines up with your own goals and tolerance for volatility.
- For income focused investors who want yield backed by resilient balance sheets, take a look at companies in our 221 dividend fortresses that aim to pair payouts with staying power.
- If capital preservation sits higher on your priority list than chasing every rally, compare Kinnevik with the businesses in our 218 resilient stocks with low risk scores and see how risk scores differ across the market.
- For readers hunting for earlier stage opportunities with robust fundamentals, the 614 high quality undiscovered gems can help surface smaller companies that are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com