


Why Greenbrier Companies earnings are drawing fresh attention
Greenbrier Companies (GBX) just posted full year results that showed revenue of US$2,461.1m and net income of US$79m, both lower than the prior year. This is putting the latest earnings firmly in focus for investors.
Recent trading shows that Greenbrier Companies’ share price has fallen 21.6% over the past 90 days and is down 17.49% year to date, even though the 3 year total shareholder return is still positive at 12.55%.
The weak full year earnings update appears to sit behind that fading momentum. At the same time, the maintained quarterly dividend and the addition of Emanuel R. Pearlman to the board give investors other factors to weigh as they assess whether current pricing reflects these risks.
Spot weak earnings trends early and compare Greenbrier Companies with a curated 33 high quality undervalued stocks that combine resilient cash flows with stronger balance sheets.After a 21.6% slide in three months and weaker full year earnings, Greenbrier Companies now sits at a crossroads. Has the recent drop already done the heavy lifting, or is most of the upside already in the rear-view mirror as valuation comes into focus next?
Most Popular Narrative: 18% Overvalued
Against a last close of $39.01, the most followed valuation narrative for Greenbrier Companies pegs fair value at $32.95, pointing to a meaningful gap that investors are now trying to explain.
The comparison management offered, fewer units delivered than the prior trough year but materially better margin, EBITDA, and earnings, is the frame Greenbrier wants investors to carry into a CEO transition. It holds up reasonably well on the metrics cited. It says nothing about why aggregate gross margin moved the wrong direction this specific period, given a backdrop that management otherwise described as the most constructive in two years.
See why 1 investors see Greenbrier Companies as 18% overvalued.
Result: Fair Value of $32.95 (OVERVALUED)
Still, the Greenbrier Companies narrative could be shaken if gross margin compression persists, or if tariff and trade disputes start to bite harder than management implies.
Find out about the key risks to this Greenbrier Companies narrative.
Another way to look at Greenbrier Companies’ valuation
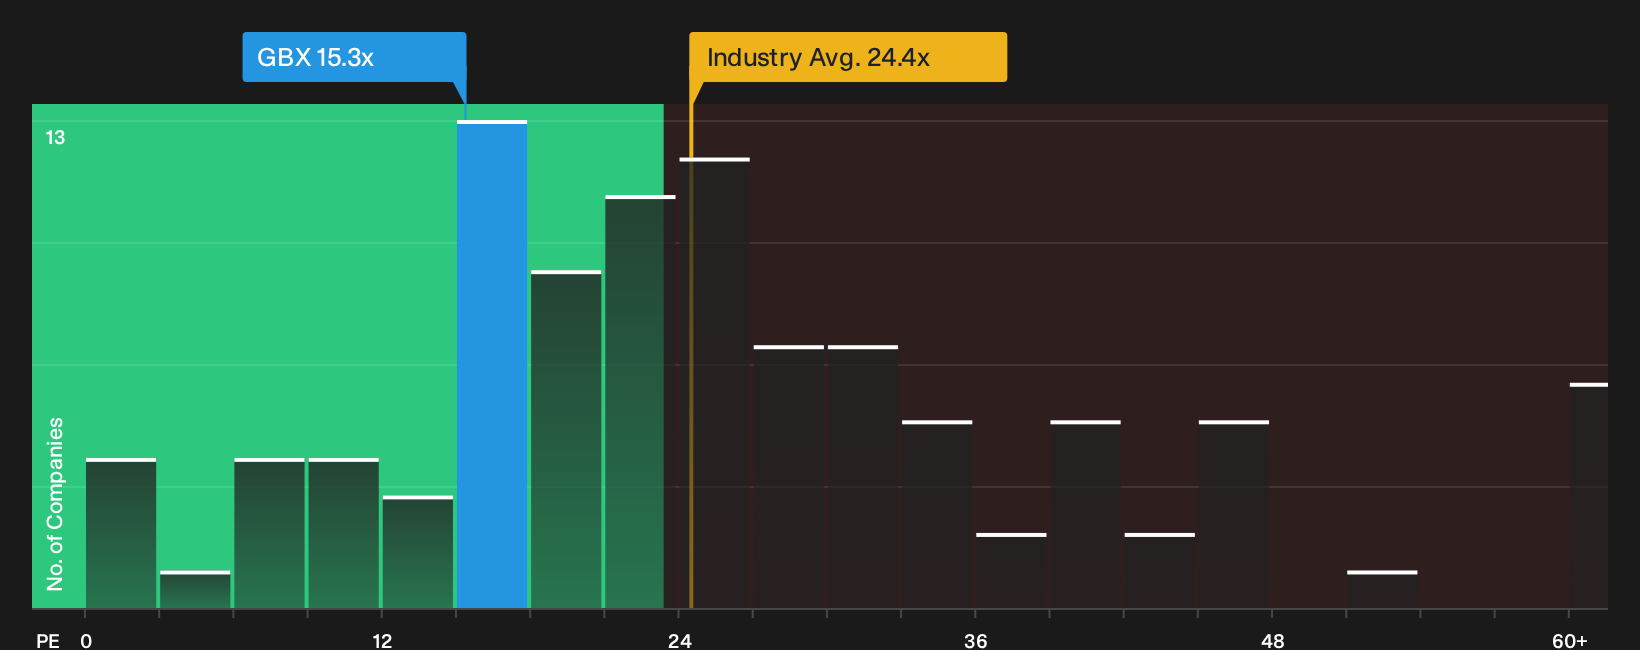
The first narrative hangs on a $32.95 fair value and calls Greenbrier Companies overvalued. A simple P/E lens tells a different story. GBX trades on 15.3x earnings, which is lower than both the US market at 18x and the US Machinery group at 24.4x, and also below a 33.9x peer average. If the share price ever moved closer to those richer multiples, the re-rating would be meaningful. The real question is whether current earnings quality and recent margin pressure justify that discount or keep it in place.
See what the numbers say about this price in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Greenbrier Companies can make the story feel messy, which is exactly why you should skim the data yourself and decide quickly where you stand. To weigh the trade off between the concerns and the potential upside, start with the 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Greenbrier Companies?
Do not stop your research with Greenbrier Companies. Fresh ideas often come from scanning wider, and missing them can be the real opportunity cost.
- Target potential mispriced opportunities by checking a curated set of companies that screen well on quality and value using the 33 high quality undervalued stocks.
- Prioritise financial resilience by running through a list of solid balance sheet and fundamentals (24 results) that can help you spot sturdier businesses when conditions get tougher.
- Hunt for future leaders early by scanning a focused group of 19 high quality undiscovered gems before the crowd starts paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com