


- Universal Health Services reported Q3 2026 revenue of US$4,733.35 million and net income of US$308.68 million, with diluted EPS from continuing operations of US$5.22. The company also outlined ongoing integration of the Talkspace acquisition and its behavioral health expansion.
- Universal Health Services is leaning on outpatient and virtual behavioral health, including Talkspace’s therapist network, to support its broader hospital portfolio. At the same time, regulatory changes and facility ramp timing present operational pressure points.
- We will now examine how Universal Health Services' Talkspace integration and behavioral health focus reshape the broader investment narrative around the business.
Compare Universal Health Services' behavioral health pivot with other hospital and mental health operators by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may better withstand regulatory and reimbursement pressure.
Universal Health Services Investment Narrative Recap
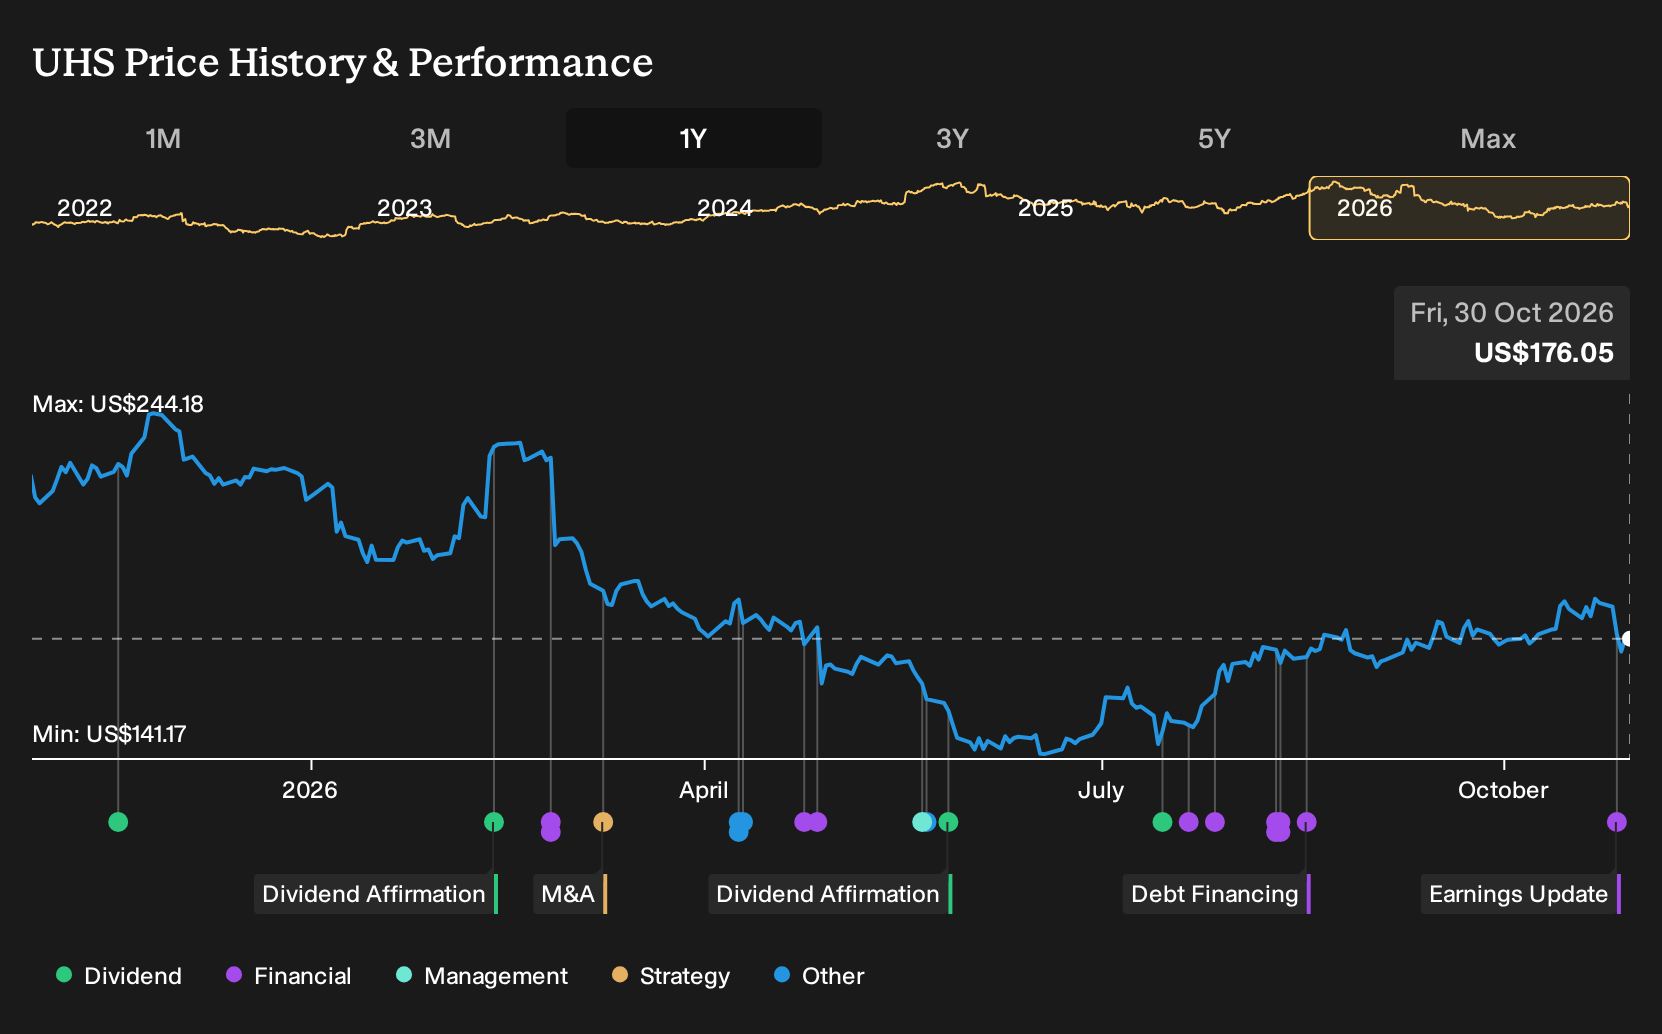
For Universal Health Services, the core belief is that the behavioral health and outpatient push, including Talkspace, can offset reimbursement and liability headwinds over time. The recent quarter shows this is not a straight line. Q3 2026 revenue of US$4,733.35 million grew from a year ago, but net income and diluted EPS from continuing operations both softened.
The near term catalyst is execution on behavioral integration and acute capacity ramps, without letting margins drift lower as Medicaid supplemental and coverage pressures build. The biggest risk is that reimbursement cuts and rising liability expenses outpace any efficiency gains or mix improvement. This quarter nudges that risk higher but does not fundamentally change the thesis.
The Q3 2026 earnings release is the key update to focus on. Universal Health Services posted nine month sales of US$13,866.55 million and net income of US$1,015.81 million, with diluted EPS from continuing operations of US$16.86. Sales over both the quarter and year to date period were higher than the prior year, while net income was lower.
That mix indicates where to look next. For investors watching catalysts, the central questions are whether Talkspace and other outpatient behavioral assets can support margins as revenue grows, and whether regulatory headwinds around Medicaid, ACA exchanges and liability costs erode that progress. Analyst tweaks to fair value and targets reflect that operational tug of war.
Universal Health Services' narrative projects US$21.0b revenue and US$1.3b earnings by 2029. This implies 5.1% yearly revenue growth and an earnings decrease of US$0.2b from US$1.5b today.
Uncover how Universal Health Services' fair value indicates a potential 8% upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Universal Health Services puts the Talkspace and Thousand Branches outpatient buildout at the center of the story. Those bullish analysts were penciling in revenue of about US$21.9b and earnings near US$1.5b by 2029. Q3’s softer net income could prompt those optimistic forecasts to shift, so explore both sets of assumptions before deciding what you believe.
Explore 4 other Universal Health Services fair value estimates, including one that suggests an upside potential of as much as 226% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Health Services research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Universal Health Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Health Services' overall financial health at a glance.
Looking for more investment ideas beyond Universal Health Services?
Once you have formed a view on Universal Health Services, you can broaden your watchlist by using the Simply Wall St Screener to surface other companies that match the type of risk, income, or balance sheet profile you prefer.
- If you want income to play a bigger role in your plan, consider stocks that show consistent payouts and high yields through 5 dividend fortresses.
- If you care most about resilience when conditions get tougher, start with companies that score well on debt and liquidity in the 29 resilient stocks with low risk scores.
- If your focus is on quality first and the price you pay second, look for businesses with strong fundamentals that the market may be overlooking in the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com