


- Delta Air Lines has seen sharp cuts to near term earnings estimates, reflecting concern about cost pressure, thinner industry margins and a tougher profit outlook than previously expected.
- The carrier is leaning more on third party maintenance, repair and overhaul revenue as a stabiliser. It is aiming to grow this cash flow stream while ticket revenue faces greater volatility.
- We will now look at how Delta Air Lines' investment narrative holds up against these fresh earnings downgrades and profit concerns.
Scan beyond Delta Air Lines and compare this reset earnings story with other carriers that screen as 33 high quality undervalued stocks on cash flows and balance sheet strength.
Delta Air Lines Investment Narrative Recap
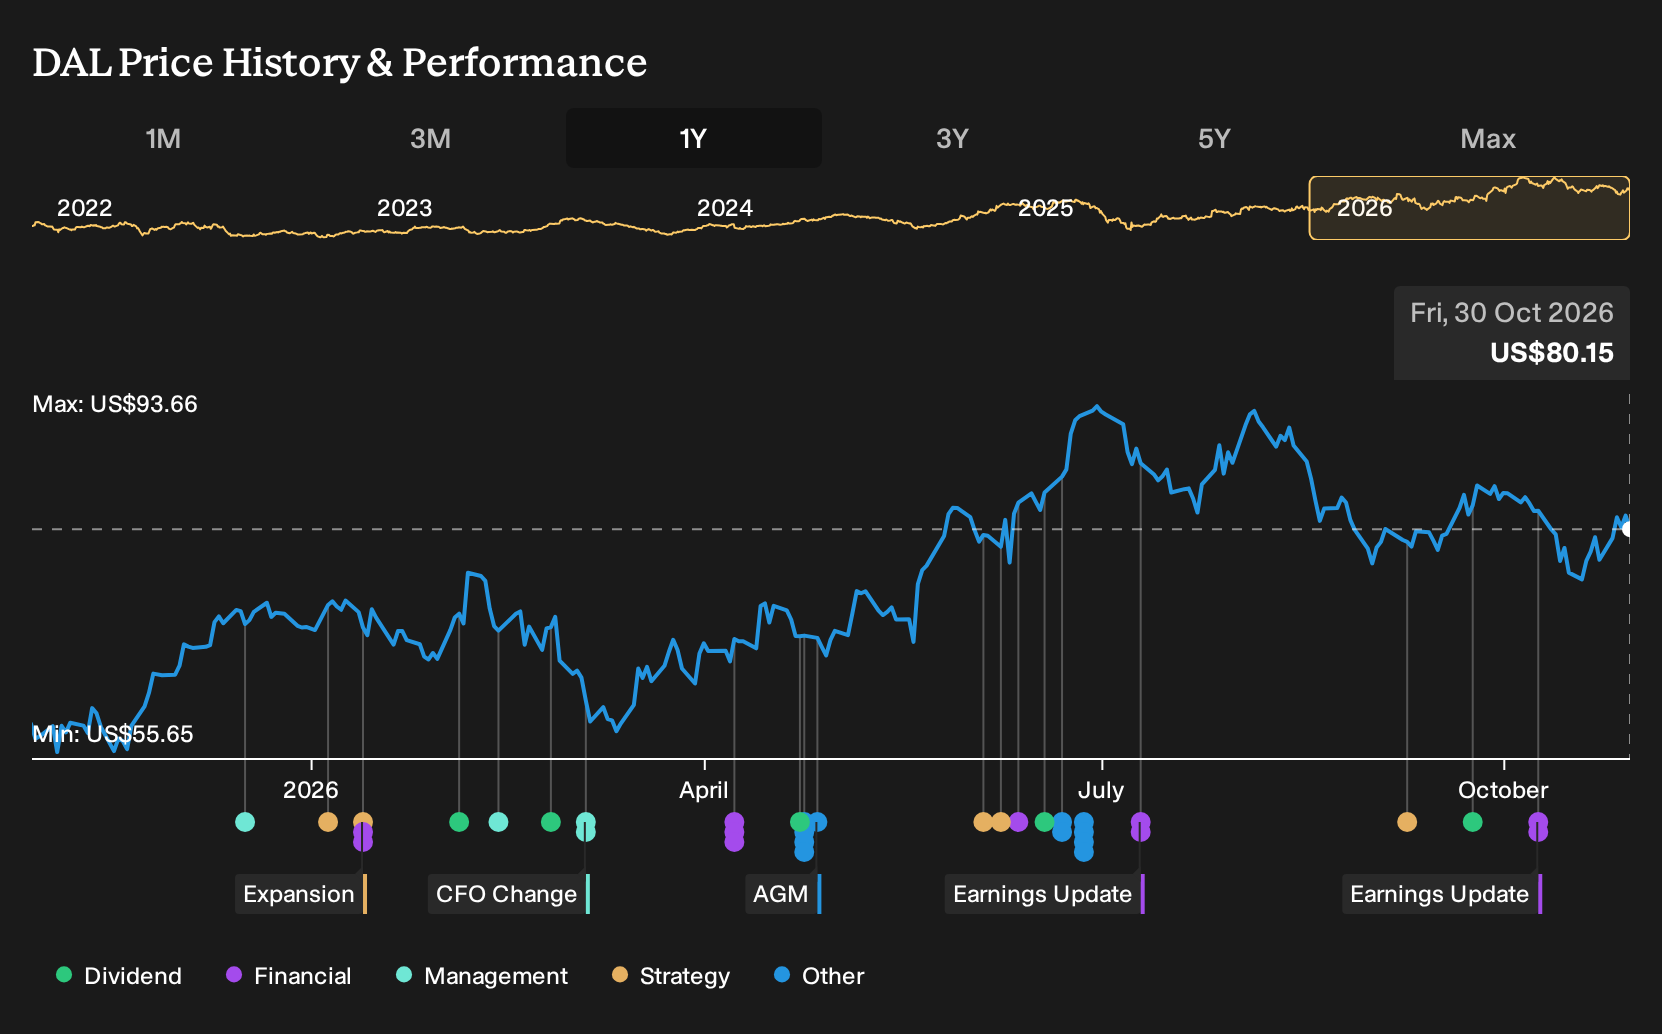
To own Delta Air Lines, you need to be comfortable with an airline that is trying to protect profitability through disciplined capacity, a heavier mix of premium and loyalty revenue, and growing third party maintenance work. The recent 24% cut to near term earnings estimates points to more near term profit pressure, rather than a change in that core playbook.
The key short term catalyst is whether Delta can hold unit revenue and cost discipline while industry margins stay under pressure. The biggest risk is a squeeze from high fuel costs and weaker main cabin demand hitting already thinner margins, especially with profit margins at 4.6%, lower than 7.4% last year.
The push to more than double third party maintenance, repair and overhaul revenue is the operational announcement that matters most right now. TechOps already generates about US$1.2b of MRO revenue in 2026 on low double digit margins. Management wants this to be a larger, more stable profit stream alongside ticket sales.
If Delta executes on that MRO expansion, including the 10 year UPS maintenance agreement, it adds a cash flow source that is less tied to day to day travel demand. For you as an investor, the question is whether this growing service business can meaningfully counter cost pressure, high debt levels, and a tougher near term profit outlook highlighted by the recent estimate cuts.
Delta Air Lines' outlook projects US$80.8b revenue and US$3.4b earnings by 2029. This is based on an assumption of 4.0% yearly revenue growth and a US$0.1b increase in earnings from US$3.3b today.
Discover why Delta Air Lines' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Delta Air Lines leans heavily on balance sheet progress as the key catalyst. Bullish analysts were working off revenue projections of about US$84.7b and earnings of roughly US$7.6b by 2029, far above consensus. With Zacks now flagging a Strong Sell, those upbeat narratives may be revisited, which is why comparing several viewpoints before making any decision can make sense.
Explore 7 other Delta Air Lines fair value estimates, including one that suggests as much as 205% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Delta Air Lines research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Delta Air Lines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Delta Air Lines' overall financial health at a glance.
Looking For More Investment Ideas Beyond Delta Air Lines?
Once you have formed a view on Delta Air Lines, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential mispricing combined with quality fundamentals, start with a focused set of companies that pass our value and quality filters through 33 high quality undervalued stocks.
- If steady income is a priority, scan for reliable cash generators offering higher yields and resilient payout histories using the 5 dividend fortresses.
- If balance sheet strength matters most to you, zero in on businesses that pair low leverage with solid fundamentals by running the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com