


- Antero Resources reported third quarter 2026 revenue of US$1,562.84 million and net income of US$367.14 million, with basic earnings per share from continuing operations of US$1.19, alongside record combined production of 390 Bcfe.
- The company paired higher output with lower impairment charges of US$1.56 million and pointed to planned fourth quarter production curtailments, highlighting how regional pricing and transportation terms affect Antero Resources operating choices.
- The next area of attention will be how Antero Resources investment narrative incorporates strong earnings, record production and the impact of planned curtailments.
Scan how Antero Resources stacks up on capital efficiency and production scale against a curated group of US-listed producers by reviewing the list of solid balance sheet and fundamentals (24 results).
Antero Resources Investment Narrative Recap
Antero Resources is still an efficiency story at its core. To stay a shareholder, you need to believe the company can keep pairing high volumes with tight cost control while living with volatile regional gas prices. The Q3 print, with higher revenue and earnings across both the quarter and first nine months of 2026, supports that operating narrative rather than changing it.
The near term swing factor now is how quickly margin gains can flow through while management deliberately curtails some output in the fourth quarter due to weak local pricing. That decision keeps pricing risk front and center. The larger risk remains long term gas and NGL demand if decarbonization policies tighten further.
The most relevant fresh data point for that thesis is Antero Resources updated fourth quarter 2026 guidance. The company expects about 4.3 Bcfe/d of output after 15 to 20 Bcfe of planned curtailments tied to low regional prices. That choice shows management is willing to protect economics rather than chase absolute volume.
For you as an investor, that guidance sits directly beside the strong Q3 and year to date earnings figures and record 390 Bcfe third quarter production. Execution now hinges on using transport agreements and cost reductions to support margins while some barrels and molecules stay in the ground. Pricing pressure in Appalachia remains the immediate operational risk to watch.
Antero Resources' narrative projects US$7.1b revenue and US$1.4b earnings by 2029. That profile is based on analysts using a 7.0% yearly revenue growth rate and indicates an earnings increase of about US$300m from the current US$1.1b level.
Uncover why Antero Resources' fair value indicates a 19% potential upside to its current price before enthusiasm around Antero Resources closes that discount.
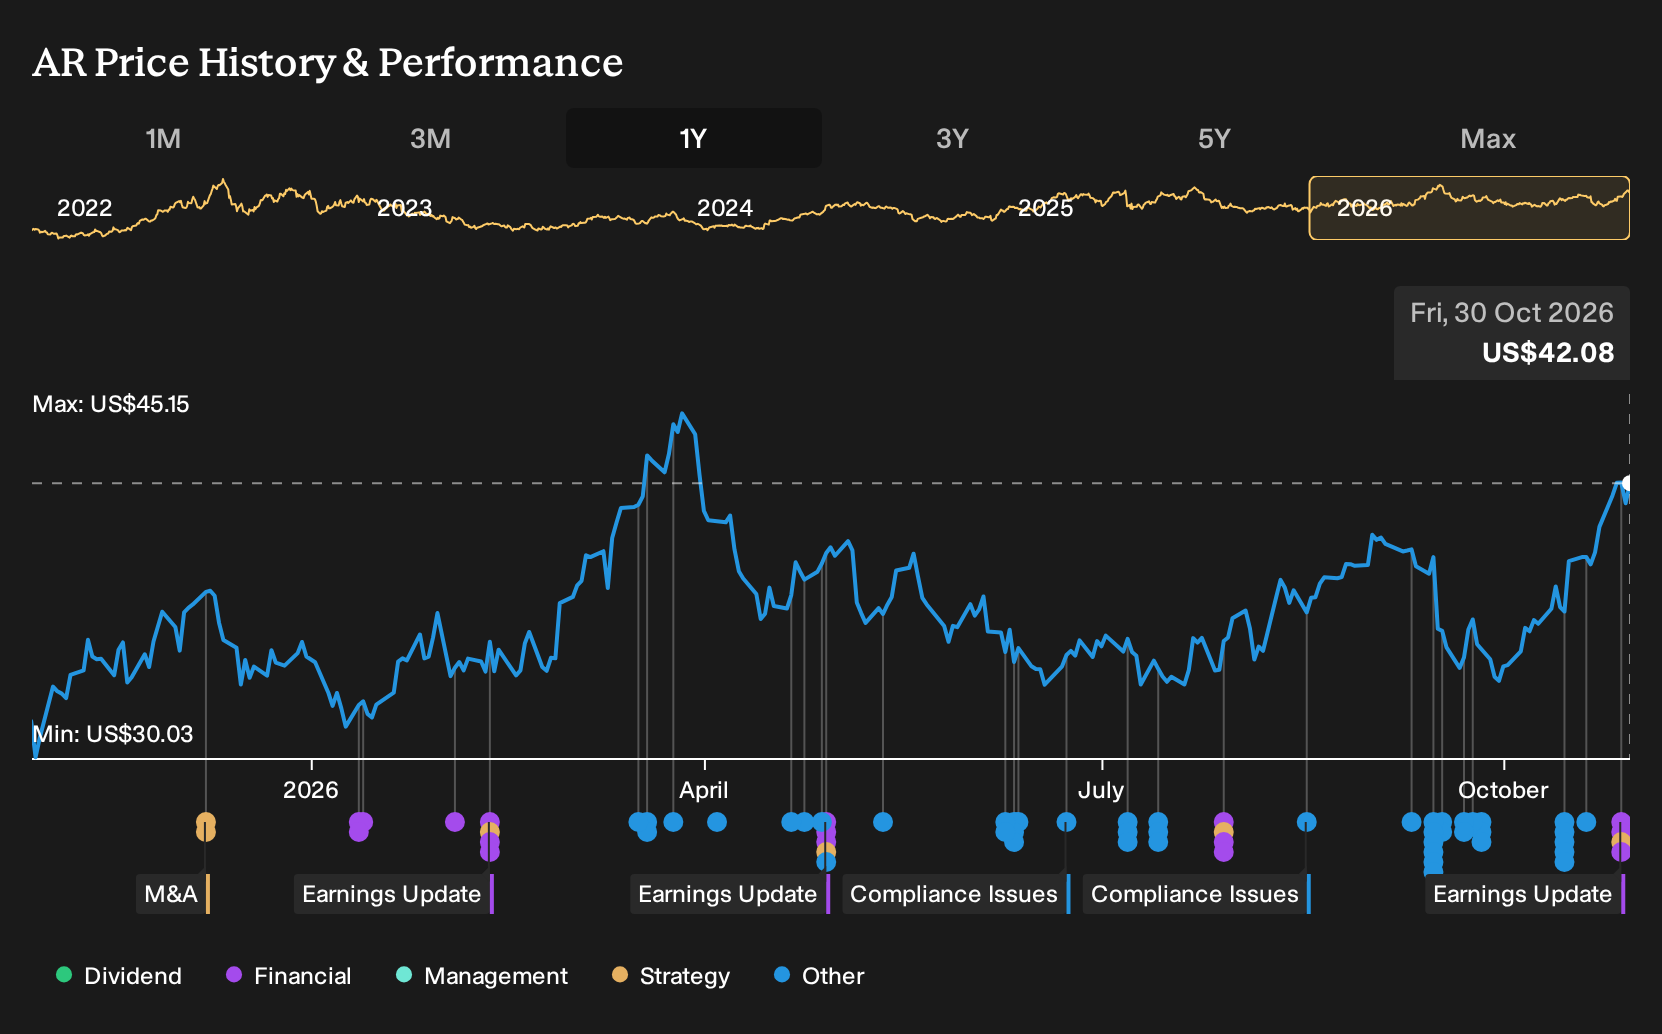
Exploring Other Perspectives
One alternate view on Antero Resources leans heavily on decarbonization risk. Bearish analysts already modeled only about US$7.1b of revenue and roughly US$1.4b of earnings by 2029 before this Q3 surprise and apply a lower 10.6x P/E. That cohort effectively prices in weaker long term demand, so use this earnings beat as a prompt to compare both narratives for yourself.
Explore 3 other Antero Resources fair value estimates, including one that suggests it could be worth just $50.19.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Antero Resources research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Antero Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Antero Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Antero Resources?
If Antero Resources has sharpened your thinking on capital discipline and earnings power, use that same lens to scan other potential holdings with the Simply Wall St Screener before deciding where your next dollar goes.
- For investors hunting for mispriced quality, start with a focused shortlist built from 33 high quality undervalued stocks and compare fundamentals side by side.
- If capital preservation and steadier return profiles sit higher on your priority list, narrow your universe using the 29 resilient stocks with low risk scores as a filter on business resilience.
- When balance sheet strength is non negotiable, build your watchlist around companies drawn from the list of solid balance sheet and fundamentals (24 results) so you are only spending time on financially sound candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com