


- Sunbelt Rentals Holdings reported that long serving Executive Vice President, General Counsel and Corporate Secretary Lynne Fuller-Andrews stepped down from her executive roles on October 23, 2026, ahead of a planned retirement on November 1, 2027, and will remain in a non executive capacity while the business searches for her successor.
- The transition keeps legal and governance continuity in place while management focuses on free cash flow guidance, capital allocation under Sunbelt 4.0, and ongoing share repurchases funded by the equipment rental platform's cash generation.
- We will now look at how Sunbelt Rentals Holdings' reaffirmed free cash flow guidance and buybacks could reshape the broader investment narrative.
Sunbelt Rentals Holdings Investment Narrative Recap
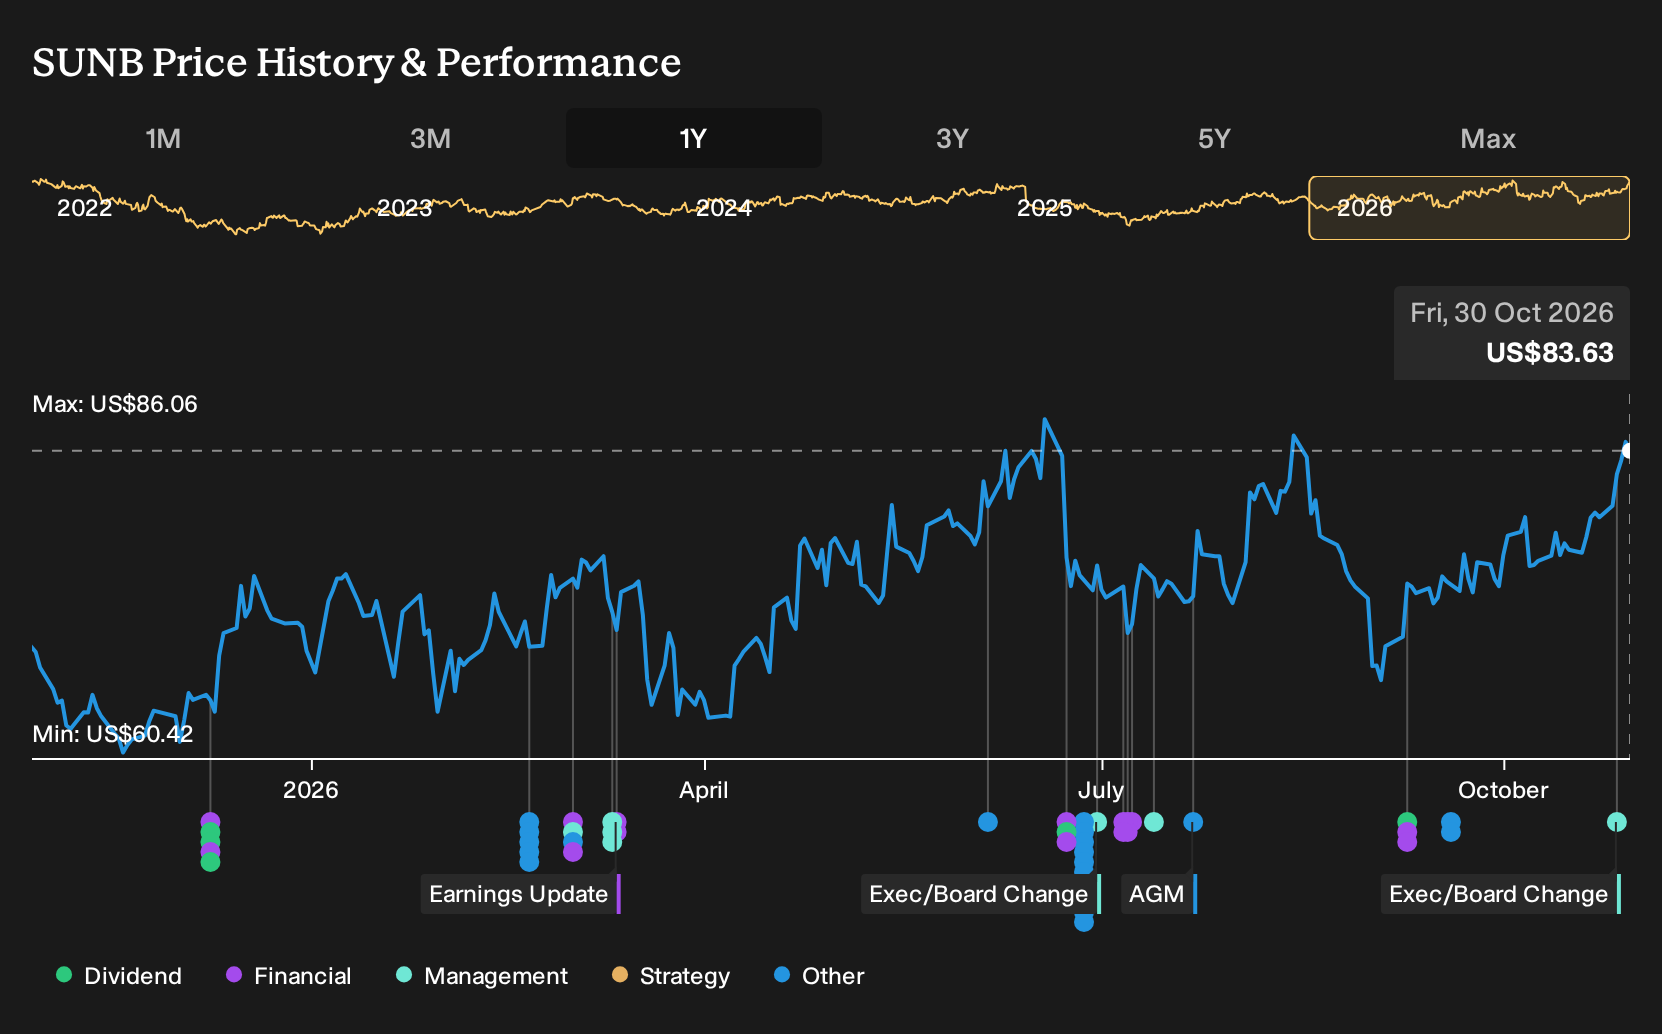
To own Sunbelt Rentals Holdings, you need to be comfortable with a construction-linked rental platform that relies heavily on free cash flow from a large, capital intensive fleet. The short term story still turns on how effectively Sunbelt 4.0 initiatives, Specialty growth and mega project work translate into utilization, pricing discipline and cash generation, especially after a strong recent share price run.
The biggest current risk is execution, given high leverage, a relatively new management bench and heavy investment demands. Lynne Fuller Andrews stepping back into a non executive role should not materially change near term catalysts. Legal continuity remains in place while operational teams focus on fleet efficiency, greenfield openings and ongoing buybacks funded by internal cash.
The reaffirmed free cash flow guidance of US$2.2b to US$2.5b for fiscal 2026 is the key recent announcement that ties directly to this leadership change. For you as a shareholder, the question is whether Sunbelt Rentals Holdings can keep converting rental revenue into cash at that level while still funding CapEx, bolt on deals and a sizeable repurchase program.
If that cash conversion holds, fewer shares combined with steady earnings could lift earnings per share even without aggressive top line expansion. The flip side is that high debt and negative earnings growth over the past year leave less room for operational missteps. That puts extra weight on clean execution of Sunbelt 4.0 and stable governance through the General Counsel transition.
Sunbelt Rentals Holdings' narrative projects US$14.0b revenue and US$2.2b earnings by 2029, based on analysts assuming 6.9% yearly revenue growth and an earnings increase of about US$800m from US$1.4b today.
Uncover how Sunbelt Rentals Holdings' fair value indicates a 6% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternate view on Sunbelt Rentals Holdings puts mega project demand front and center. The most optimistic analysts were penciling in US$14.3b revenue and US$2.5b earnings by 2029, versus US$14.0b and US$2.2b in the baseline, before this General Counsel transition, so their story could shift as governance questions come into focus.
Explore 2 other Sunbelt Rentals Holdings fair value estimates, including one that suggests up to 16% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sunbelt Rentals Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sunbelt Rentals Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sunbelt Rentals Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sunbelt Rentals Holdings?
Once you have a view on Sunbelt Rentals Holdings, it helps to compare that thesis with other opportunities that match your preference for quality, value or resilience. The Simply Wall St Screener can narrow a large market into a short list that fits the type of portfolio you want to build.
- If you care most about valuation and fundamentals, start with a curated set of what our filters flag as potential quality-at-a-discount ideas through 33 high quality undervalued stocks.
- If capital strength and staying power matter more to you than rapid expansion, focus on companies with sturdier finances by scanning the list of solid balance sheet and fundamentals (24 results).
- If you want ideas that the market might not be paying close attention to yet, look for underfollowed opportunities screened by the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com