


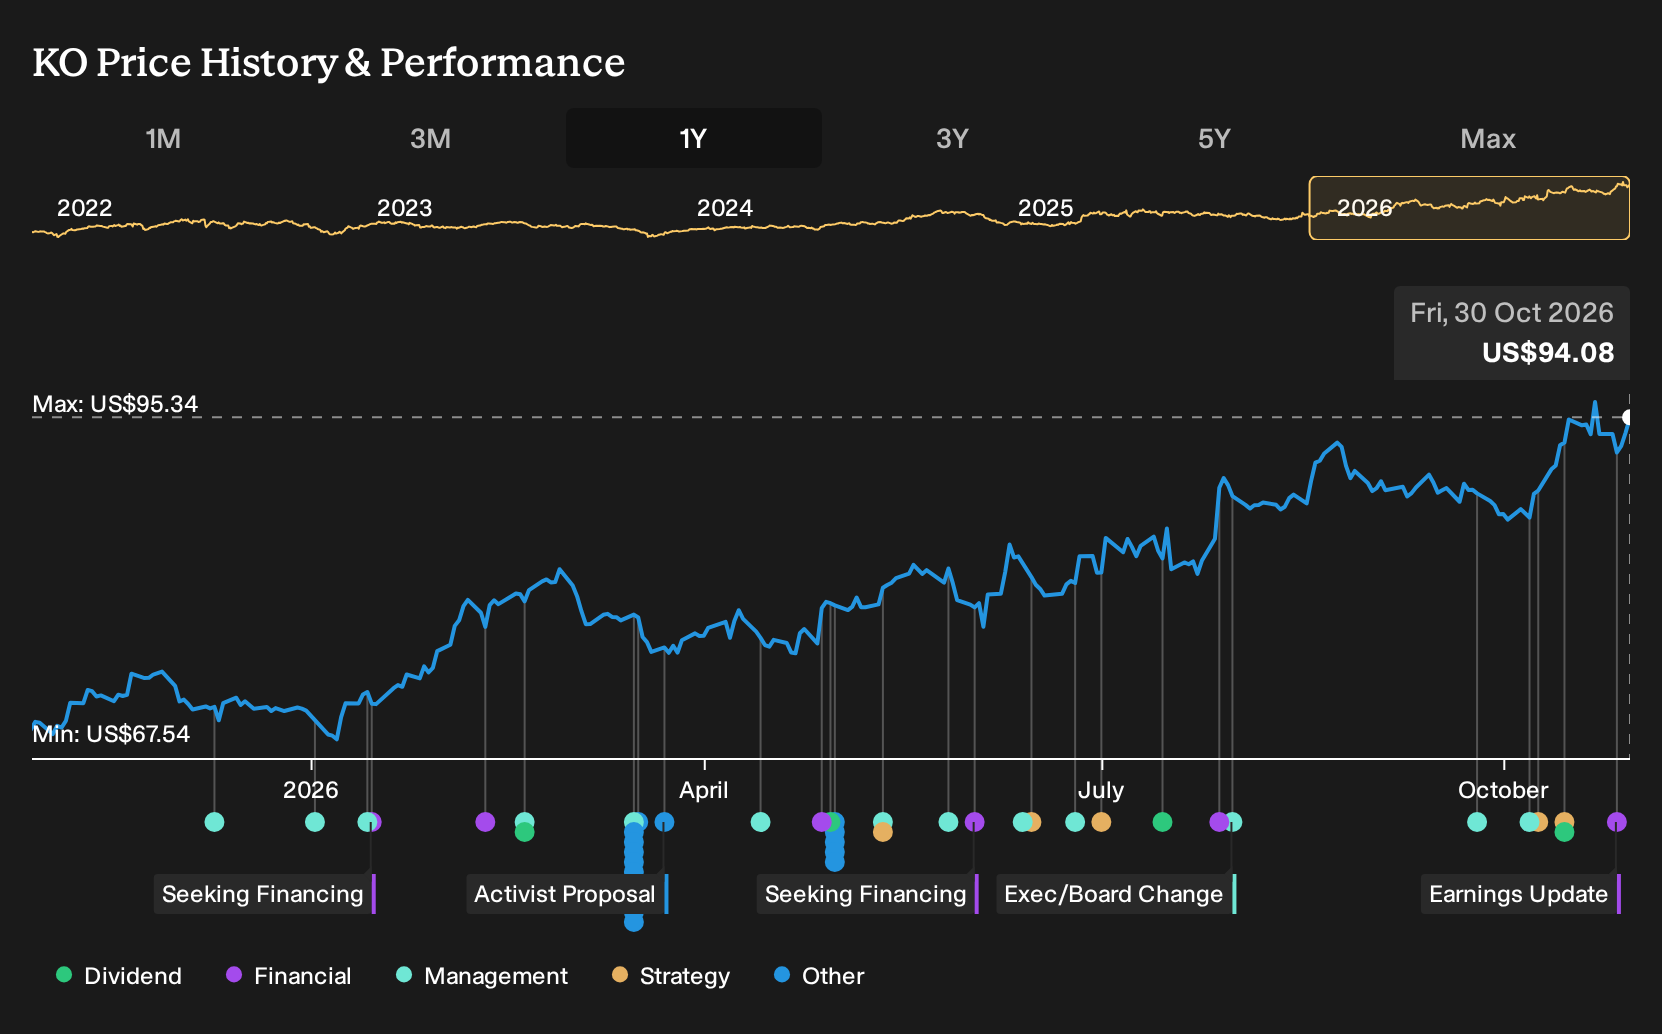
- Coca-Cola reported Q3 2026 sales of US$13,380 million and net income of US$4,009 million, with raised full year guidance following stronger earnings and volume trends.
- The upcoming switch to supply beverages to roughly 3,600 KFC restaurants across the U.S. from 2027 points to expanding food service reach beyond classic sodas.
- We now consider how Coca-Cola’s investment narrative could shift in light of stronger earnings and the KFC beverage win.
Scan how Coca-Cola’s Q3 momentum and the KFC win compare with other branded consumer giants by reviewing the hand picked 33 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
Coca-Cola Investment Narrative Recap
To own Coca-Cola, you need to believe this beverage group can keep turning a global brand portfolio into steady cash flow, even as consumers focus more on health and regulators scrutinise sugar. The short term story hinges on the firm converting Q3 momentum, including higher revenue and net income, into consistent volume and price mix execution.
The biggest operational risk right now sits with cost pressure and changing consumption patterns. Rising logistics expenses, GLP 1 driven shifts in calorie intake and divestiture related revenue drags could all squeeze earnings if not offset by mix, packaging and marketing choices. Recent results improve confidence but do not remove those pressures.
The KFC fountain win is the clearest link between the recent earnings beat and future catalysts. Supplying drinks to about 3,600 U.S. KFC restaurants from 2027 extends Coca-Cola’s reach in quick service channels and supports its push beyond classic sodas into a broader nonalcoholic line up served with meals.
Operationally, that agreement can work alongside emerging market expansion, fairlife capacity growth and digital tools that help tailor pricing and packaging. The key execution test will be whether this extra food service volume and the wider portfolio help offset health, regulatory and cost risks, while still supporting the dividend and the current P/E multiple.
Coca-Cola's narrative projects US$53.6b revenue and US$16.6b earnings by 2029. This aligns with analyst expectations of 1.7% yearly revenue growth and approximately a US$2.0b increase in earnings from US$14.6b today.
Uncover why Coca-Cola's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Across 10 fair value estimates from the Simply Wall St Community, Coca-Cola’s range from about US$66 to just under US$98 per share shows how far opinions can stretch. Some see strong cash generation, dividend history and the KFC win as powerful supports, while others focus on sugar regulation and GLP 1 risks. Use that spread as a prompt to explore several alternative viewpoints before deciding how Coca-Cola fits your own portfolio goals.
Explore 9 other Coca-Cola fair value estimates, including one estimate that suggests it could be worth as much as $97.54.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Coca-Cola research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Coca-Cola. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola's overall financial health at a glance.
Looking for more Coca-Cola style investment ideas?
Once you have a view on Coca-Cola, it can help to line it up against other opportunities that match your risk appetite and income needs. The Simply Wall St Screener lets you filter for fundamentals, balance sheet strength and income potential so you can build a watchlist that fits how you like to invest.
- If you want income to do more of the heavy lifting in your returns, review a curated set of 5 dividend fortresses that combine higher yields with fundamental checks on payout strength.
- If your priority is capital preservation and steadier business profiles, narrow your search to a 29 resilient stocks with low risk scores that screen for more resilient operations and cleaner balance sheets.
- If you prefer businesses with headroom for growth that are not yet heavily followed, focus on a 19 high quality undiscovered gems that flags strong fundamentals hiding behind quieter tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com