


- Cohu reported third quarter 2026 sales of US$172.96 million versus US$126.25 million a year earlier, with net income of US$12.13 million compared with a prior net loss and diluted earnings per share from continuing operations of US$0.22 versus a diluted loss per share of US$0.09.
- For the first nine months of 2026, Cohu recorded sales of US$447.08 million against US$330.73 million a year earlier, while the net result moved close to break-even at a loss of US$0.098 million. This reflects a combination of cost discipline and higher demand for AI and high-performance computing related test equipment that is beginning to reshape operating performance.
- We will now explore how Cohu's investment narrative could shift as profitability returns, supported by AI and high-performance computing demand.
Scan how Cohu's AI test exposure compares with hand picked peers by reviewing the 54 AI infrastructure stocks, which are also leaning into high-performance computing demand.
Cohu Investment Narrative Recap
Cohu appeals to investors who buy into a simple idea. Test equipment tied to AI, high performance computing and more complex chips could steadily absorb a larger share of industry capital spending, while cost controls keep the model tight. The latest quarter, with sales at US$172.96 million and a return to profit, supports that thesis rather than changing it.
The short-term hinge remains how quickly recent AI and high performance computing orders convert into sustained shipment volume. The biggest risk is still cyclicality and customer concentration. A slower ramp or a pause in orders from a few large buyers could hit utilization and undo some of the recent operating momentum.
The most relevant data point here is Cohu’s nine-month performance to late September 2026. Sales of US$447.08 million and a net loss that has moved close to break even show a business that is already absorbing higher AI test demand while still carrying the scars of earlier downturn conditions. That context matters when weighing today’s optimism.
For catalysts, this near break-even result tightens the link between execution on AI and high performance computing programs and the path to more durable profitability. It also underlines key risks. Any delay in qualifying next-generation handlers, disruption from the manufacturing shift to Asia, or a pullback in end markets like automotive and industrial semiconductors would feed through quickly to earnings quality.
Cohu's narrative references analyst expectations for revenue of US$1.2b and earnings of US$215.2 million by 2029. This implies forecast revenue growth of 27.6% a year and an earnings increase of about US$237.8 million from current earnings of a US$22.6 million loss.
Uncover why Cohu's fair value indicates a 47% potential upside to its current price, which could narrow quickly.
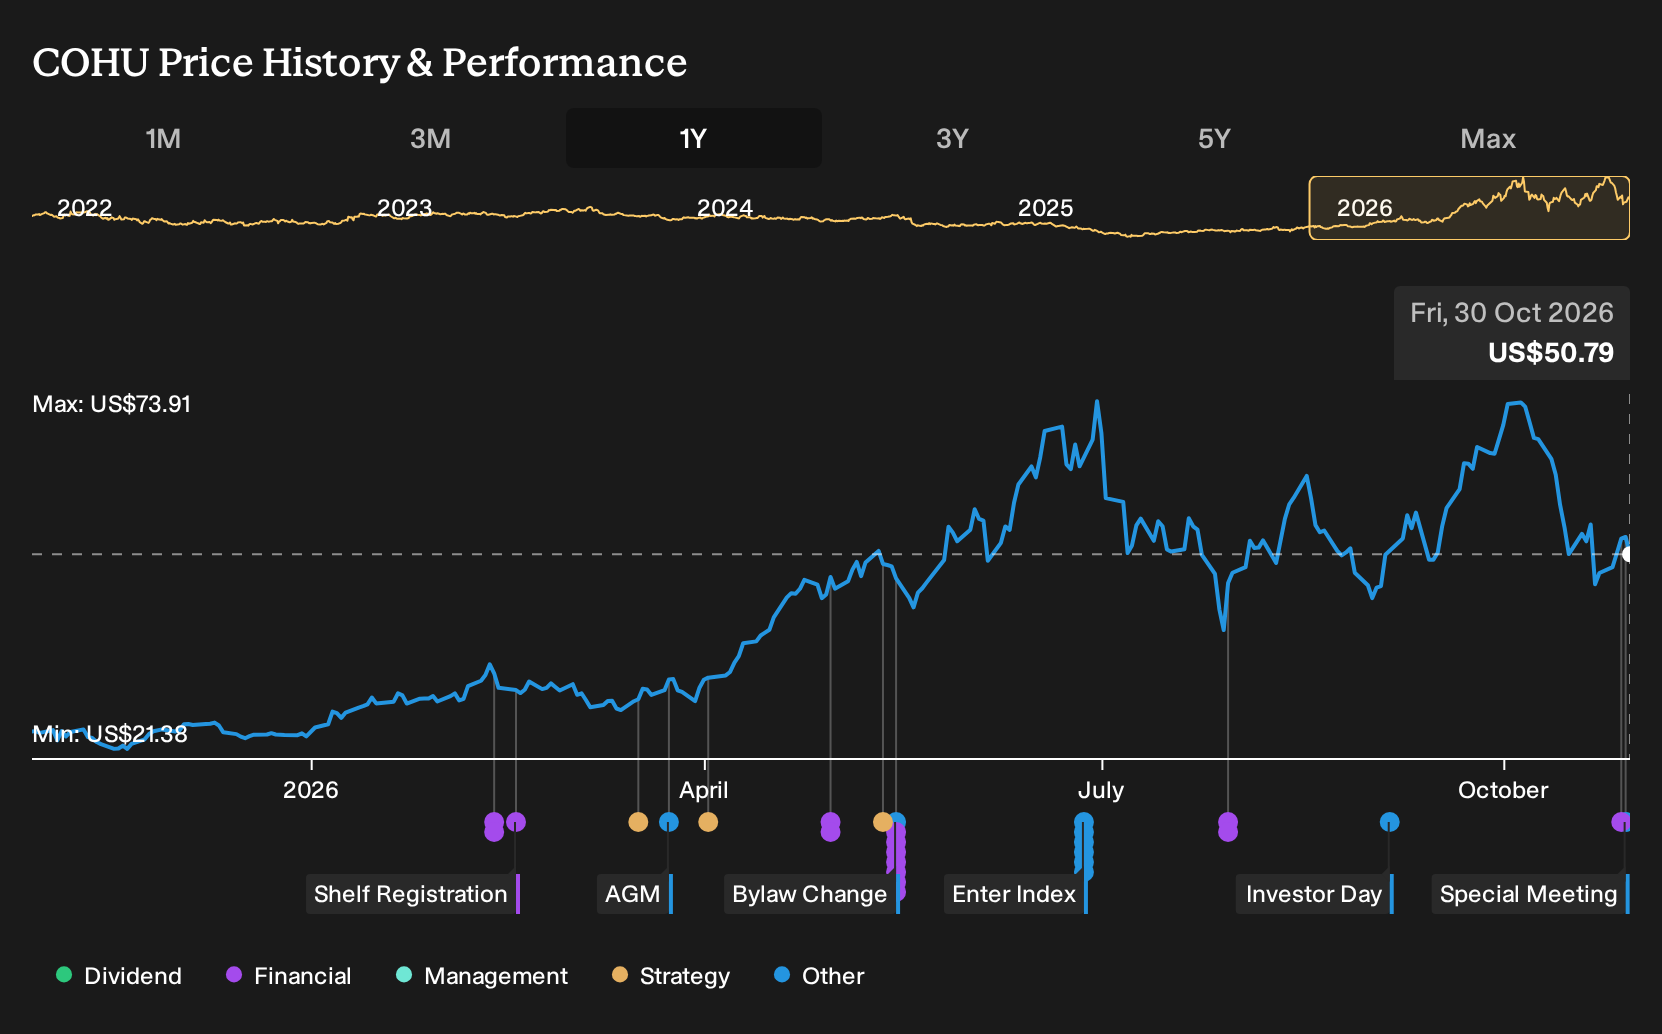
Exploring Other Perspectives
One alternate read on Cohu leans hard into AI handler concentration risk. Those bearish analysts saw tighter outcomes, with revenue reaching about US$893.1 million and earnings of roughly US$104.1 million by 2029. That is far below the consensus profile. Treat this Q3 earnings jump as fresh information that could push those narratives to evolve.
Explore 3 other Cohu fair value estimates, including one that suggests it could be worth just $73.15!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cohu research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cohu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cohu's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cohu?
If the Cohu story has sharpened your thinking but you want a wider menu of possibilities, the Simply Wall St screener can help you quickly surface other businesses that line up with your priorities on quality, value, or resilience.
- If capital preservation is near the top of your list, start with a focus on resilience and review 29 resilient stocks with low risk scores to see which companies align with that profile.
- When you want income on top of potential price moves, take a look at steady payers and examine 5 dividend fortresses that might suit a yield focused approach.
- For investors hunting for overlooked stories with solid fundamentals, scan through 19 high quality undiscovered gems and see which businesses deserve a spot on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com