


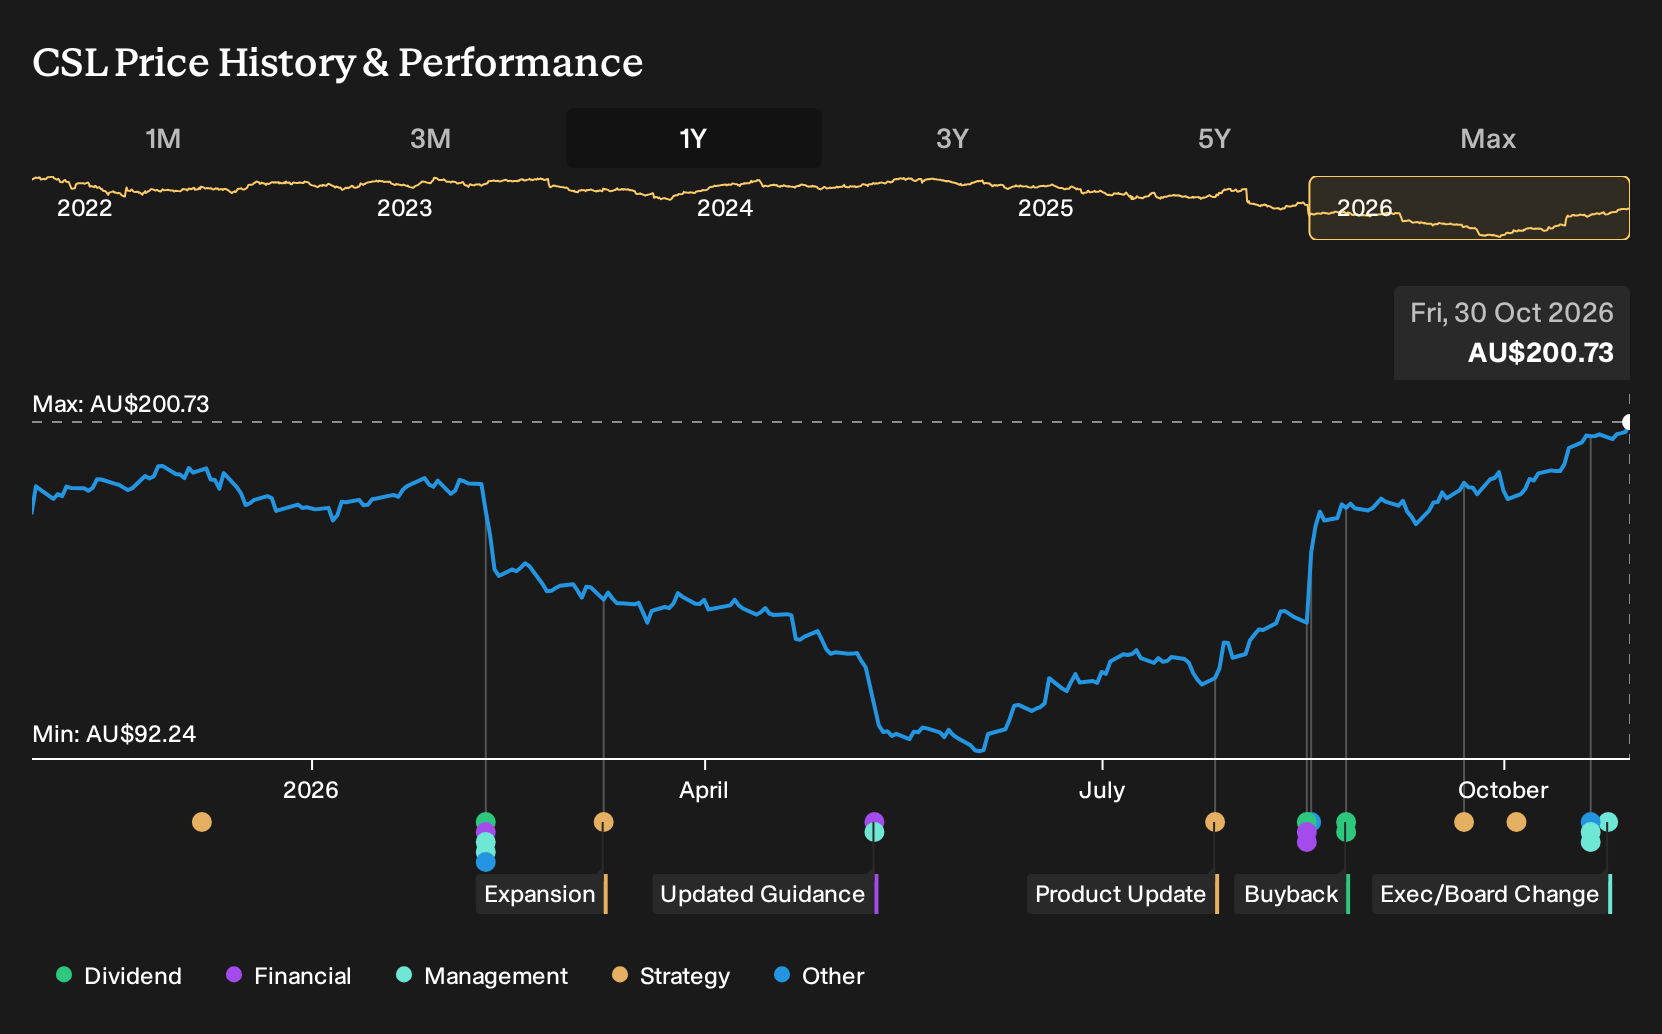
- CSL announced that Deborah Waterhouse will become CEO and Managing Director from 1 February 2027, alongside a wider board refresh including Gordon Naylor as future Chair and Carolyn Hewson as Senior Independent Director from 31 March 2027.
- The leadership shift brings an executive with deep HIV and vaccines experience into CSL at the same time the group is managing legal proceedings over historic disclosure and performance representations. This combination could reshape how the business sets and communicates its medium term priorities.
- The focus now turns to how CSL's investment narrative could be influenced by Deborah Waterhouse's appointment and the broader board transition.
CSL Investment Narrative Recap
To own CSL, you need to believe its plasma, vaccines and iron nephrology operations can keep funding reinvestment while the cost out program and capital discipline do their job. The short term swing factor is still execution on immunoglobulin and vaccines volumes and margins, because those segments anchor the broader earnings recovery story.
Right now the biggest risk sits in operational and regulatory pressure around Vifor and China albumin, plus the new group proceeding over disclosure and FY26 performance representations. The leadership and board refresh, while significant in governance terms, does not change these near term business pressure points in a material way.
The legal action filed in the Supreme Court of Victoria is the announcement that matters most for the CSL story around these board changes. It directly challenges prior disclosure and performance commentary, which pulls investor attention toward governance, risk controls and how the future CEO and incoming Chair handle capital allocation against that backdrop.
For catalysts, the key question is whether ongoing transformation savings, plasma process upgrades and the vaccines mix shift can absorb any extra legal, remediation or compliance costs. Execution on those projects, plus careful balance sheet management given CSL's high debt level, will shape how much room the business has to keep funding growth initiatives if legal risks persist.
CSL's consensus scenario points to forecast revenues of $17.0b and earnings of $3.3b by 2029, based on analysts assuming 2.5% yearly revenue growth and a move from a current earnings loss of $2.6b to that $3.3b profit. This represents a swing of about $5.9b in earnings by the 2029 forecast year.
Uncover why CSL's fair value indicates a 7% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate angle focuses less on the lawsuits and more on how CSL uses the multiyear US$0.5b cost saving plan. The most pessimistic analysts already assumed only 1.8% annual revenue growth to about $16.7b and earnings of roughly $3.5b by 2029, before this governance shake up, so you may want to see how those expectations shift as the new leaders settle in.
Explore 9 other CSL fair value estimates, including one that suggests as much as 30% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CSL research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CSL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CSL's overall financial health at a glance.
Looking for more CSL‑style investment ideas?
If you want to stress test your thesis on CSL and widen your opportunity set, the Simply Wall St Screener can help you filter for companies with the financial traits you care about most.
- Prioritise resilience and capital preservation by scanning for businesses that score well on risk metrics using the 6 resilient stocks with low risk scores.
- If balance sheet strength is top of your checklist, you can focus on companies with robust finances through the list of solid balance sheet and fundamentals (12 results).
- For investors looking for potentially mispriced opportunities with quality fundamentals, you can broaden your search with the 15 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com