


Uber’s €41.50 per share cash offer for Delivery Hero put a hard number on what this platform was worth to a larger rival. Holding Delivery Hero from the start of the year would have returned 63.5%, including dividends. If you were weighing a purchase back on 1 January, you had to decide whether a capital intensive food delivery operator under regulatory scrutiny could attract exactly this kind of bidder interest. What needed to appear credible at that time for that decision to seem reasonable?
The easy part of this move is behind Delivery Hero. Zero in on 203 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Delivery Hero Investors Had To Weigh
The shares cost €22.72 at the start of the period, and anyone looking at Delivery Hero then was really choosing between two very different stories.
On the upbeat side, the bull narrative suggested the stock could be worth a fair value of €34.07, effectively a price implied by assumptions of 10.0% annual revenue growth and profit margins rising to 1.7%, helped by AI-driven cost efficiencies and Q-commerce expansion.
The bear narrative pointed to a fair value of €21, based on revenue rising 6.6% a year and margins reaching 1.8% while EU employment rules, legal payouts and tougher competition pushed structural costs higher.
What The Results Changed For Delivery Hero
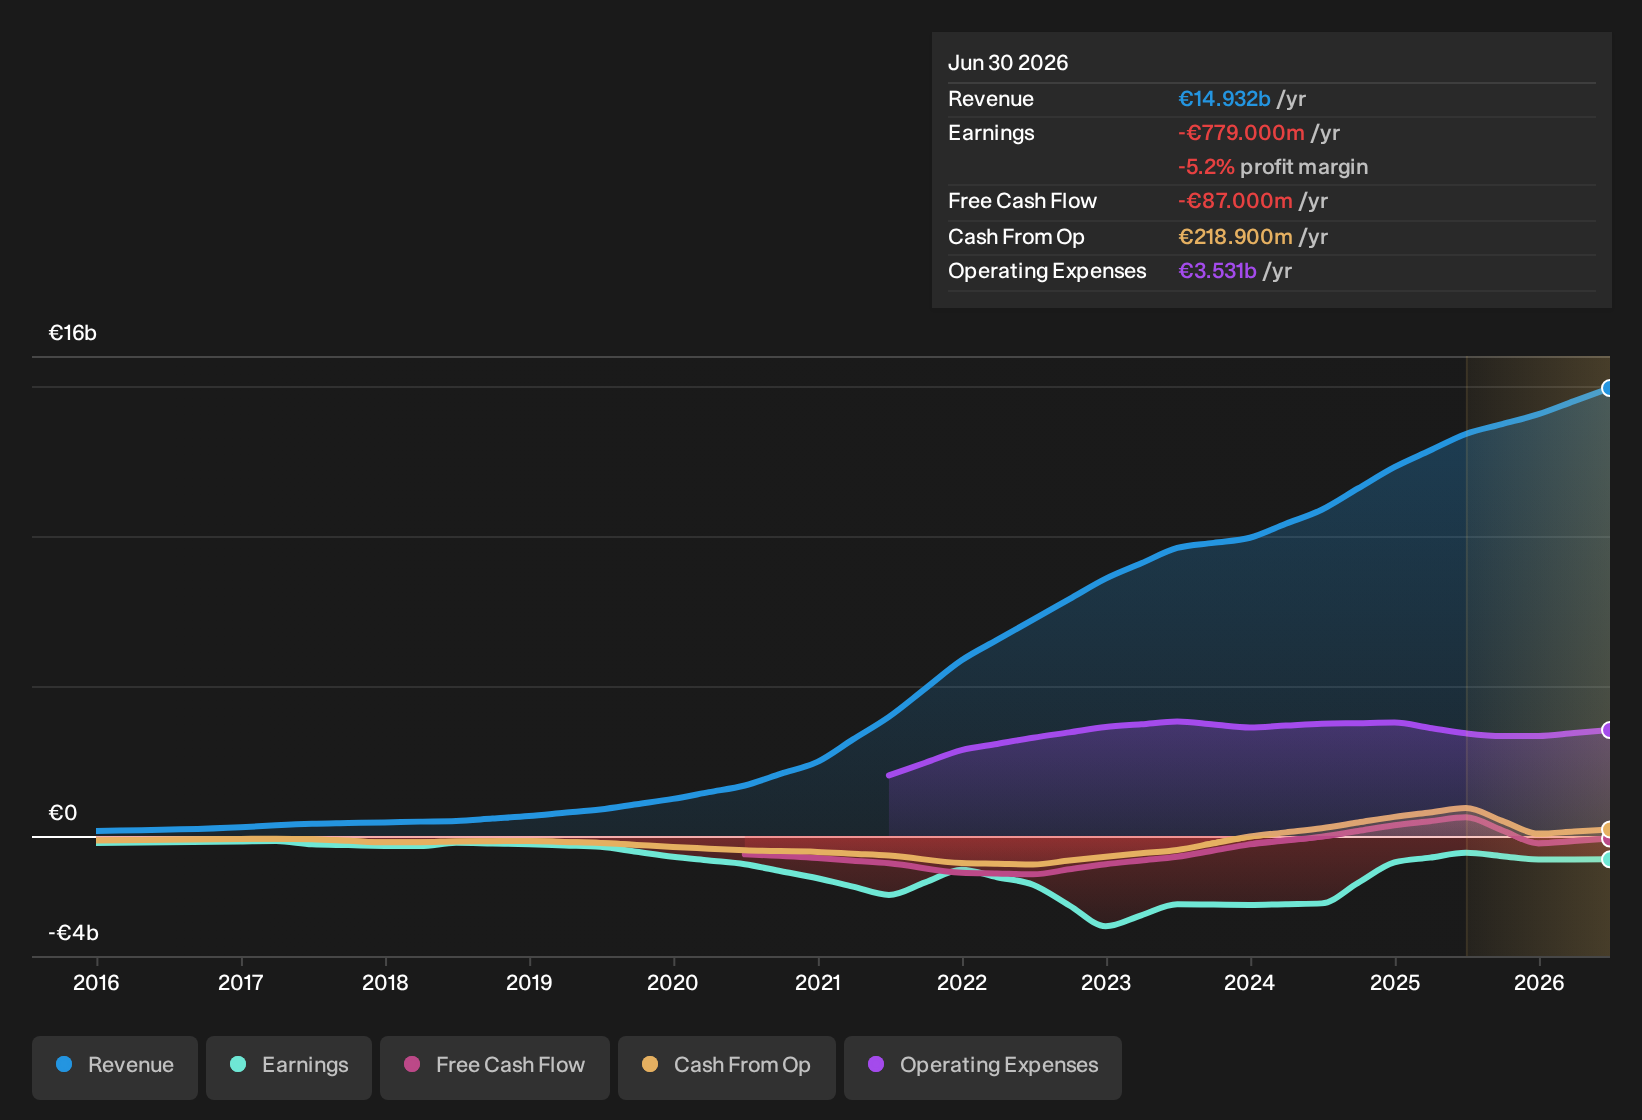
Uber’s agreed €41.50 per share takeover of Delivery Hero, backed by management and key shareholders, supported the optimistic case that a larger platform might pay up for its network. H1 2026 results pointed the other way on profitability, with the group still reporting a loss of €392.4 million even as revenue reached €7.8b and net margin stayed negative at 5.1%. The evidence cut both ways.
The useful lesson is simple. When a thesis leans on a premium takeover or rerating, treat that as upside, not the core assumption. Anchor on what you can track each half year, such as the direction of net margin and absolute profit. Then test any later bid or multiple against that operational record at another company.
What Delivery Hero’s Run Now Asks You To Believe
Delivery Hero now trades at €37.3 from the start of the year, with this Narrative’s Fair Value sitting below that quote rather than above it. The argument turns on how much of Uber’s €41.50 cash offer and recent operational progress are already embedded in today’s valuation.
The selected Narrative stresses that current pricing leans on Everyday App usage, subscriptions, AdTech and multi vertical services converting into dependable cash while legal provisions and working capital swings persist. A buyer at €37.3 is effectively assuming that future cash generation comfortably outpaces those ongoing competition and antitrust costs. The question is how much room those charges leave.
"Subscriber penetration at 47% of GMV and rapid AdTech growth in Europe suggest higher margin levers in theory, yet the €194m of management adjustments in the first half of 2026, including €173m tied to competition and antitrust risks, point to a scenario where any mix and AI efficiency benefits are absorbed by recurring regulatory costs and leave limited room for sustained improvement in net margins."
One Narrative disagrees with today's price. → See where this Narrative says Delivery Hero should trade
Looking Beyond Delivery Hero
Delivery Hero depends on frequent repeat orders that must clear cleanly every time.
Your experience only works when payments, confirmations and courier timing align without friction.
Travel platforms face a similar coordination problem, often taking your money long before you travel or dine.
One large operator there holds and routes those prepayments, sitting between guests, hotels and restaurants.
If you are studying Delivery Hero’s working capital swings, this parallel in how float behaves might deserve closer attention.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 118% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com