


Stanley Black & Decker (SWK) has reaffirmed its regular fourth-quarter cash dividend at $0.84 per share, a decision that keeps income investors focused on the stock’s cash flow support.
Recent performance has given income holders more to think about. Stanley Black & Decker’s share price has climbed strongly with a year to date share price return of 35.27%. The 1 year total shareholder return of 59.30% points to meaningful gains once dividends are included. However, the 5 year total shareholder return is still down 32.36%, which hints at momentum rebuilding after a weaker multi year patch.
Capitalize on the renewed momentum in Stanley Black & Decker by scanning a curated list of industrial peers with resilient earnings profiles through 29 resilient stocks with low risk scores.After a 59.30% total return over the past year yet a 32.36% decline over five years, Stanley Black & Decker now sits near analyst value estimates. Is it worth committing capital here, or does patience win on entry price timing?
Most Popular Narrative: 4% Overvalued
Analysts see Stanley Black & Decker trading modestly above their fair value estimate of about $99.36, compared with the last close at $103.44. The current debate is whether recent execution justifies that premium or not.
The multi-year supply chain transformation nearing its final phase is delivering substantial recurring cost reductions, improved operational flexibility, and resilience to trade/tariff shocks. Management expects these initiatives to drive gross margin back to 35%+ by late 2026, supporting sustained improvements in net margins and earnings.
See why 37 investors see Stanley Black & Decker as 4% overvalued.
Result: Fair Value of $99.36 (OVERVALUED)
Still, soft DIY demand and volume pushback on higher prices could pressure Stanley Black & Decker if cost savings and premium tool investments do not offset these factors.
Find out about the key risks to this Stanley Black & Decker narrative.
Another View: What Stanley Black & Decker’s P/E Is Really Saying
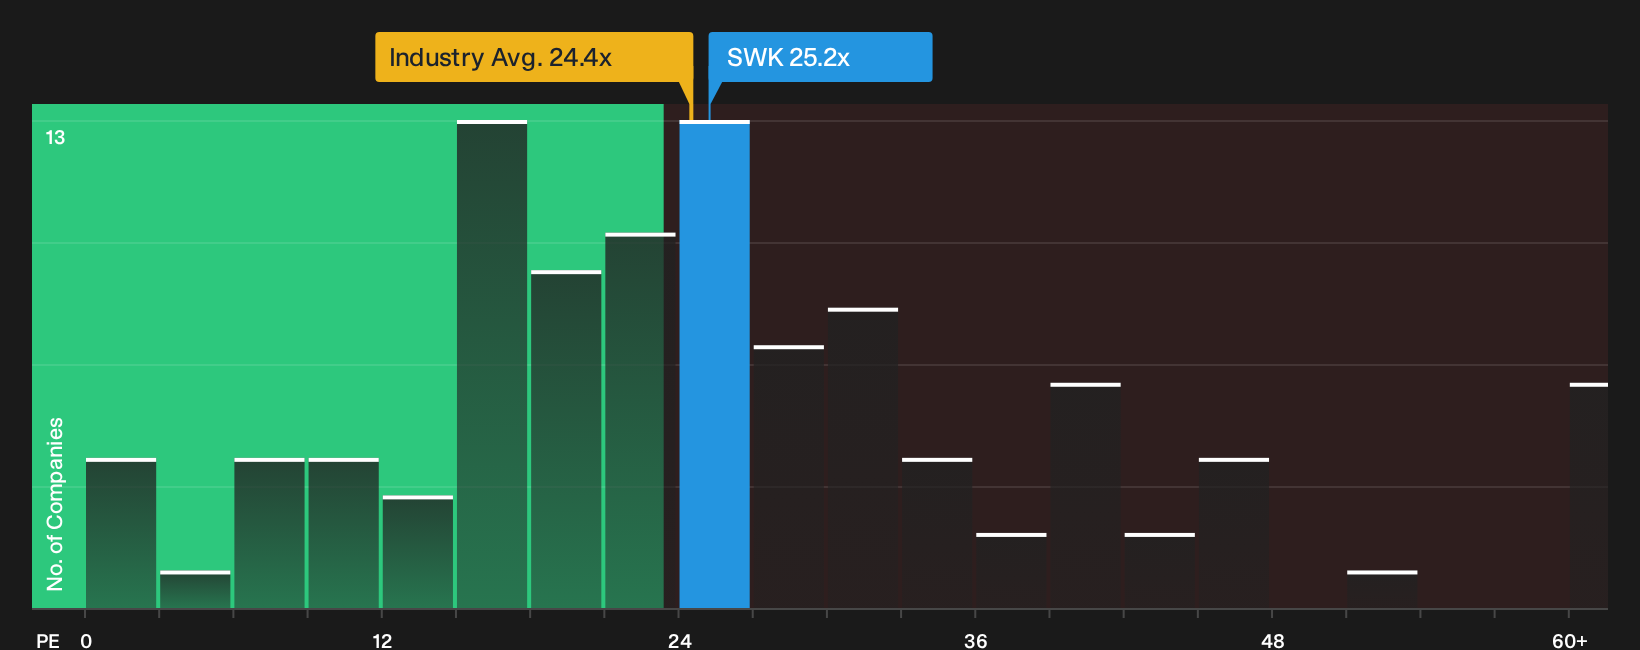
On pure valuation multiples, Stanley Black & Decker sends a mixed message. The stock trades on a P/E of 25.2x, slightly above the US Machinery industry at 24.2x, yet almost exactly in line with a fair ratio of 25.3x. So is that a slim margin of error or a narrow window of opportunity for new money?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Stanley Black & Decker’s value and momentum can be confusing. Move quickly, review the full data set, and weigh both the risks and the upside in the 4 key rewards and 1 important warning sign.
Ready for more investment ideas beyond Stanley Black & Decker?
If Stanley Black & Decker has sharpened your focus on quality, do not stop here. Broader opportunity sits in how you allocate your next dollar.
- Target dependable income by reviewing companies that screen as potential 5 dividend fortresses that can help anchor the yield side of your portfolio.
- Hunt for mispriced strength through a curated 33 high quality undervalued stocks that highlights candidates with earnings support and room for a stronger market view.
- Strengthen your downside protection by running a list of solid balance sheet and fundamentals (24 results) so you are not caught out by weak finances when conditions turn.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com