


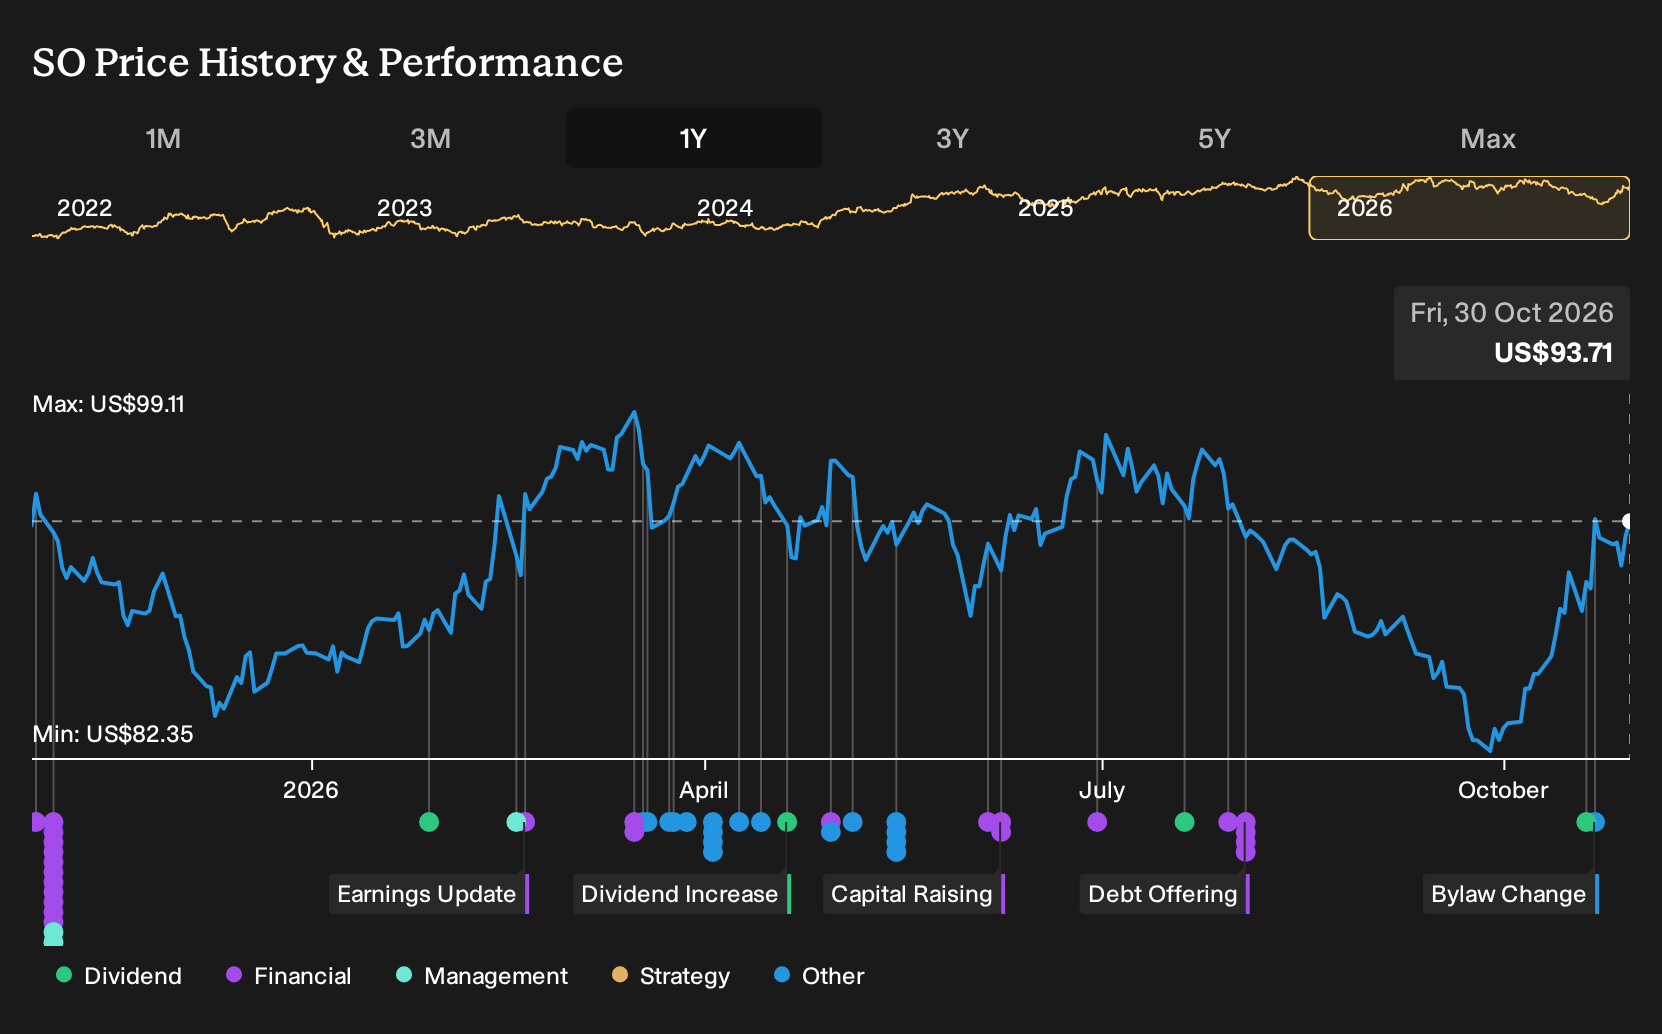
- Southern Company recently overhauled its by-laws, tightening rules around special meetings, director nominations, voting standards and legal forums, while affirming a regular quarterly dividend of US$0.76 per share payable in December 2026.
- Fresh governance rules and new leadership roles for Kim Greene and Stan Connally align corporate control, capital planning and grid build decisions more tightly with Southern’s large-load and infrastructure ambitions.
- The next area of focus will be how Southern’s refreshed bylaws reshape its investment narrative through tighter shareholder procedures and governance.
Scan how Southern’s governance reset compares with peers by checking which utilities and infrastructure stocks also pass the governance and balance sheet filters in our curated list of solid balance sheet and fundamentals (24 results).
Southern Investment Narrative Recap
To own Southern, you need to be comfortable with a regulated utility leaning into very large capital programs tied to data centers, long duration power contracts and grid upgrades. The near term story still hinges on executing that build schedule without putting excessive strain on customer bills or credit metrics, which are already in focus given interest coverage and funding mix.
The most important short term catalyst remains visible progress on generation and storage projects tied to contracted large loads. The biggest risk is that heavy use of debt and equity linked financing pressures earnings per share and free cash flow. The bylaw reset itself looks more like plumbing than a material change to these near term business drivers.
The fresh bylaw package is the operationally relevant headline. It tightens how special meetings are called, how directors are nominated and how voting standards work. It also specifies Delaware Chancery Court and US federal courts as exclusive forums for certain disputes. For you, that mostly affects how quickly governance questions can be raised and resolved.
Clearer shareholder procedures can reduce friction around Southern’s capital plan, large load contracts and long term funding decisions because management and the board have more defined rules of engagement. That can cut distraction risk when the business is trying to deliver 10 GW of new generation, manage sizeable DOE loan facilities and balance ongoing equity issuance against dilution concerns.
Southern’s Earnings Bar for 2029
Southern's narrative projects US$36.2b revenue and US$6.5b earnings by 2029. That profile lines up with analysts assuming 6.3% yearly revenue growth and an earnings increase of about US$1.8b from US$4.7b today.
Uncover why Southern's fair value indicates a 4% potential upside to its current price before that discount to Southern’s story potentially closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$3.84 to US$97.08 per share, so views on Southern Company’s worth are all over the map. That divergence aligns with real execution risk around dilution and large capital projects, which can reshape returns. Explore these contrasting viewpoints before firming up your own stance.
Explore 2 other Southern fair value estimates, including one that suggests as much as 96% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Southern research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Southern. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Southern's overall financial health at a glance.
Looking for more Southern Company style investment ideas?
If Southern’s mix of regulated cash flows, heavy capital plans and grid exposure appeals to you, it can help to line it up against other businesses with similar or contrasting traits using the Simply Wall St Screener.
Here are a few focused starting points that can broaden your watchlist without sending you down an endless rabbit hole of tickers:
- If you want potential mispricing combined with quality fundamentals, compare Southern with a curated group of candidates in the 33 high quality undervalued stocks.
- For investors who care most about income resilience, balance Southern’s dividend profile against companies in the 5 dividend fortresses.
- If capital preservation and steadier risk profiles matter to you, round out your research by scanning the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com