


WeRide (NasdaqGM:WRD) is back in focus after launching a global insurance partnership program with Allianz Insurance Singapore and Ping An Property & Casualty Insurance, aimed at supporting its autonomous driving rollout across multiple regions.
The insurance partnership arrives after a tough stretch for WeRide’s shareholders, with the 1-year total shareholder return down 61.2% and the year-to-date share price return down 55.9% at a latest share price of US$4.14.
Compare WeRide’s insurance-backed push into autonomous driving with other robotics and automation players by screening for 95 robotics and automation stocks that are already drawing market attention.
WeRide’s shares have dropped hard while both analyst targets and intrinsic value estimates sit far above the current US$4.14 price. Does that gap indicate potential mispricing, or could it simply reflect optimistic spreadsheets?
Most Popular Narrative: 68% Undervalued
Analysts following WeRide see a fair value of $13.02, well above the recent $4.14 share price. This valuation places significant emphasis on its international rollout and eventual profitability under a 9.32% discount rate.
The global shortage of professional drivers in regions such as Europe and parts of the Middle East, combined with relatively high taxi fares, positions WeRide’s L4 robotaxi and robobus offerings as a possible substitute for human driven fleets. This may support recurring service revenue and improve earnings stability over a 5 to 7 year vehicle life.
See why 9 investors see WeRide as 68% undervalued.
Result: Fair Value of $13.02 (UNDERVALUED)
Still, WeRide’s story leans heavily on regulators continuing to grant and renew permits, while high R&D spending and ongoing losses leave little room for execution missteps.
Find out about the key risks to this WeRide narrative.
Another View On WeRide’s Valuation
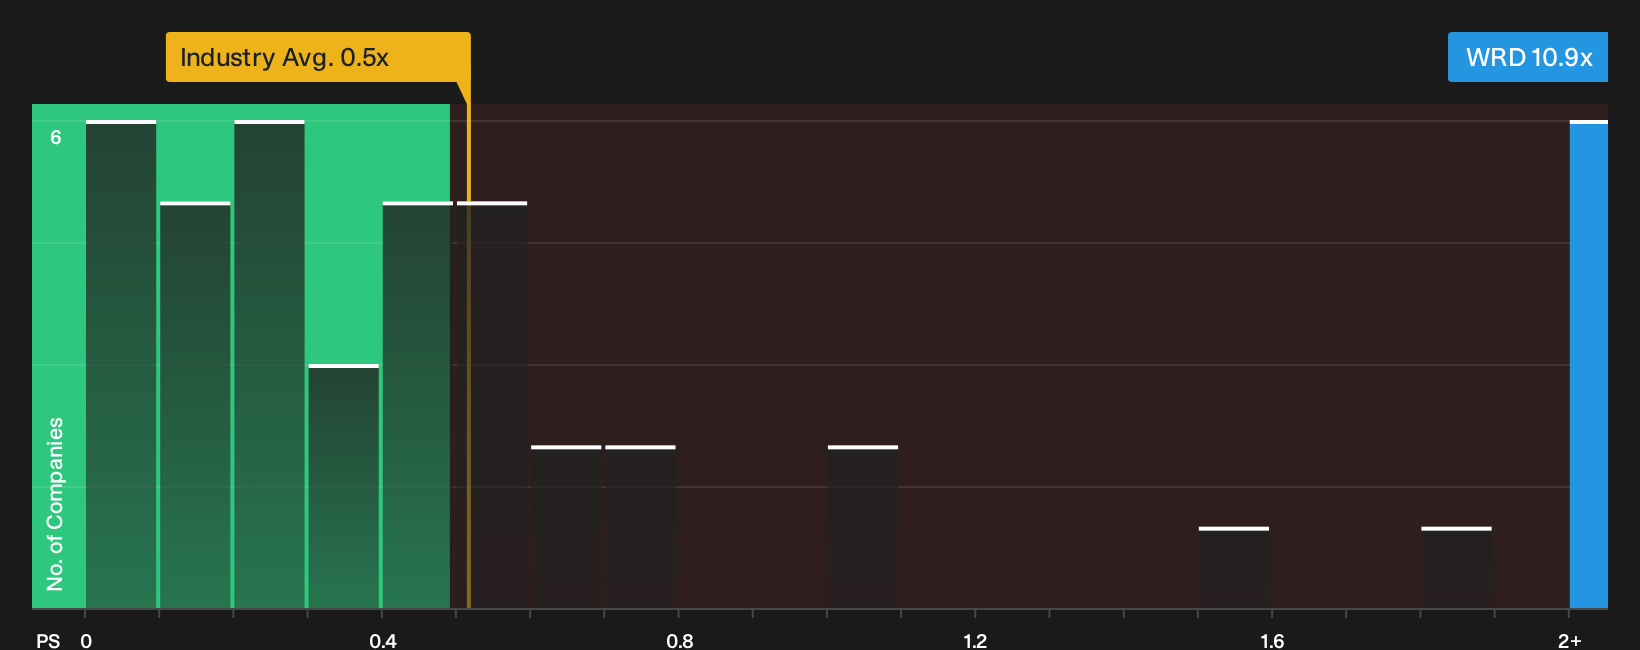
Analysts lean on earnings forecasts to argue WeRide is undervalued at $4.14, yet the P/S ratio tells a very different story. The stock trades on 10.9x sales compared with 0.5x for the US Auto Components sector and 1.7x for peers, while the fair ratio is 3x.
That puts WeRide at more than double the peer average and well above the fair ratio that the market could move towards. This points to real valuation risk if high growth and margin assumptions are not met. Which version of value do you trust more when the signals point in opposite directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the WeRide story so far. If you want to move fast and build your own stance, start by weighing up the 2 key rewards.
Looking For More Investment Ideas Beyond WeRide?
WeRide raises big questions about pricing and growth. Do not stop there. Broaden your watchlist now so you are not relying on a single story.
- Target potential mispriced opportunities by scanning a curated pool of 33 high quality undervalued stocks that pair solid fundamentals with more reasonable expectations.
- Strengthen your capital base by filtering for companies with resilient finances using a focused list of solid balance sheet and fundamentals (24 results).
- Spot early-stage potential by reviewing a tight 8 elite penny stocks with strong financials that already shows stronger financial quality than many bigger peers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com