


Hokkaido Electric Power Company stock closed at ¥1,079 on 30 October, roughly flat over the past month and only modestly higher over the last quarter. The market reaction looks muted. The earnings story is not. For Q2 2027 the utility delivered revenue of ¥226,854m but net income of ¥5,792m, which points straight at the real issue. Profitability is being squeezed. Margins matter more than headlines here, especially for a capital heavy power operator with weak interest coverage and a dividend that already leans on thin free cash flow.
Concerned that Hokkaido Electric Power Company is squeezing thin profits out of heavy assets while its dividend leans on fragile cash generation? Compare it with utilities that pair steadier cash flow with stronger balance sheets in our list of solid balance sheet and fundamentals stocks (22 results)
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥226,854m vs. ¥209,454m (top line higher year on year)
- Net Income (Q2 2027 vs Q2 2026): ¥5,792m vs. ¥13,351m (profit roughly halved compared with the prior year quarter)
- Basic EPS (Q2 2027 vs Q2 2026): ¥28.20 per share vs. ¥65.01 per share (earnings per share materially lower year on year)
- Net Profit Margin (TTM, latest year vs prior year): 2.1% vs. 6.3% (trailing margin compressed sharply, indicating weaker profitability for Hokkaido Electric Power Company)
Earnings tell part of Hokkaido Electric Power Company's story, but investors who care about what they are really paying tend to focus on the cash flowing through the business. From a cash flow perspective alone, the stock could be a slight 8% overvalued.
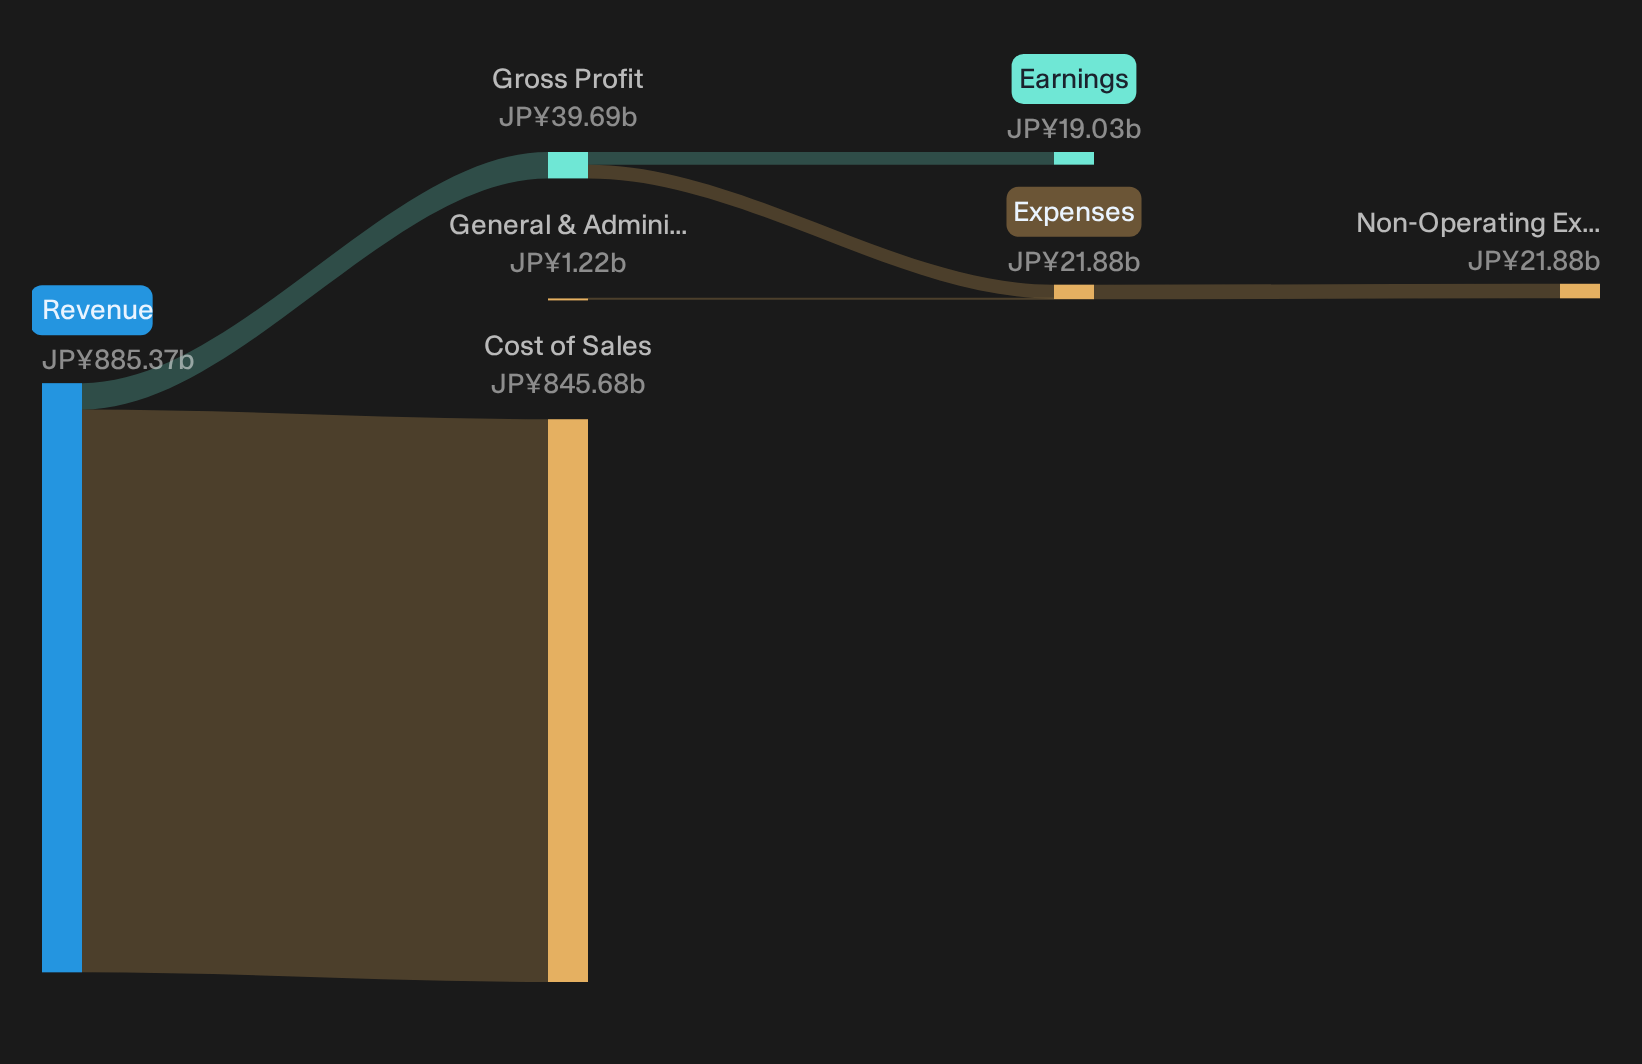
Revenue resilience keeps the bullish story alive
For a bullish view on Hokkaido Electric Power Company, the key support is that revenue sits at ¥226,854m compared with ¥209,454m a year earlier. The top line is at least holding its ground while the stock has barely moved over the last month. For a regulated utility facing heavy capital needs, including the ¥125.5b Tomari seawall project, that matters. It suggests customers are still paying the bills even as earnings per share and trailing net margin look weaker.
Profit squeeze strengthens concerns around the bear case
On the cautious side, the latest income line does much of the talking. Net income of ¥5,792m, roughly half the ¥13,351m level from the prior Q2, sits uneasily beside a trailing margin that has compressed to 2.1% from 6.3%. EPS has moved in the same direction. For Hokkaido Electric Power Company, that combination of tight profitability, muted share performance and a heavy Tomari seawall budget reinforces concerns about thin coverage of dividends and interest costs rather than easing them.
After a year where profit margins fell from 6.3% to 2.1% and interest costs look thinly covered, it is fair to ask whether Hokkaido Electric Power Company is dealing with a temporary squeeze or a deeper structural issue around its capital intensity, pricing power and dividend policy. Before assuming this is just a rough patch, Review the full risk analysis for Hokkaido Electric Power Company which shows 3 important warning signsHunt For Cleaner Balance Sheets
Hokkaido Electric Power Company shows how fragile profits can look when heavy assets and thin margins collide. The real opportunity is finding stocks that could be low debt before the market corrects them.
- Company 1 - 35% below our estimate - build AI driven hiring and local services engines that turn job matching into recurring software style revenue.
- Company 2 - 45% below our estimate - push an AI native security platform where subscription contracts convert heavier product spending into recurring protection fees.
- Company 3 - 18% below our estimate - expand maintenance focused elevator services by hiring sales staff to win contracts that deepen route density.
That is three of the list. See every one of the 22 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com