


NTN has just posted its Q2 2027 results, and the real story is profit momentum, not price drift. The stock closed today at ¥359.1, roughly flat over the past week and weaker over the past quarter, which signals a market still unsure about the turnaround narrative.
The earnings print tells a different story. Net income reached ¥3,533m for the quarter, with basic earnings per share at ¥5.94, further backing up the shift to profitability over the last year. Short term caution in the share price now stands in contrast to a cleaner income statement and a firmer earnings base.
Like NTN’s profit turnaround but unsure about a share price that has not followed yet? Explore a curated group of companies with cleaner earnings profiles and healthier sentiment using our list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥201,300m vs. ¥203,217m (broadly stable top line year on year)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥3,533m vs. ¥1,910m (sharp improvement in quarterly profit level)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥5.94 vs. ¥3.61 (meaningfully higher earnings per share for the quarter)
- Trailing 12M Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥15,232m vs. a loss of ¥18,576m (swing from loss to a positive earnings base over the last year)
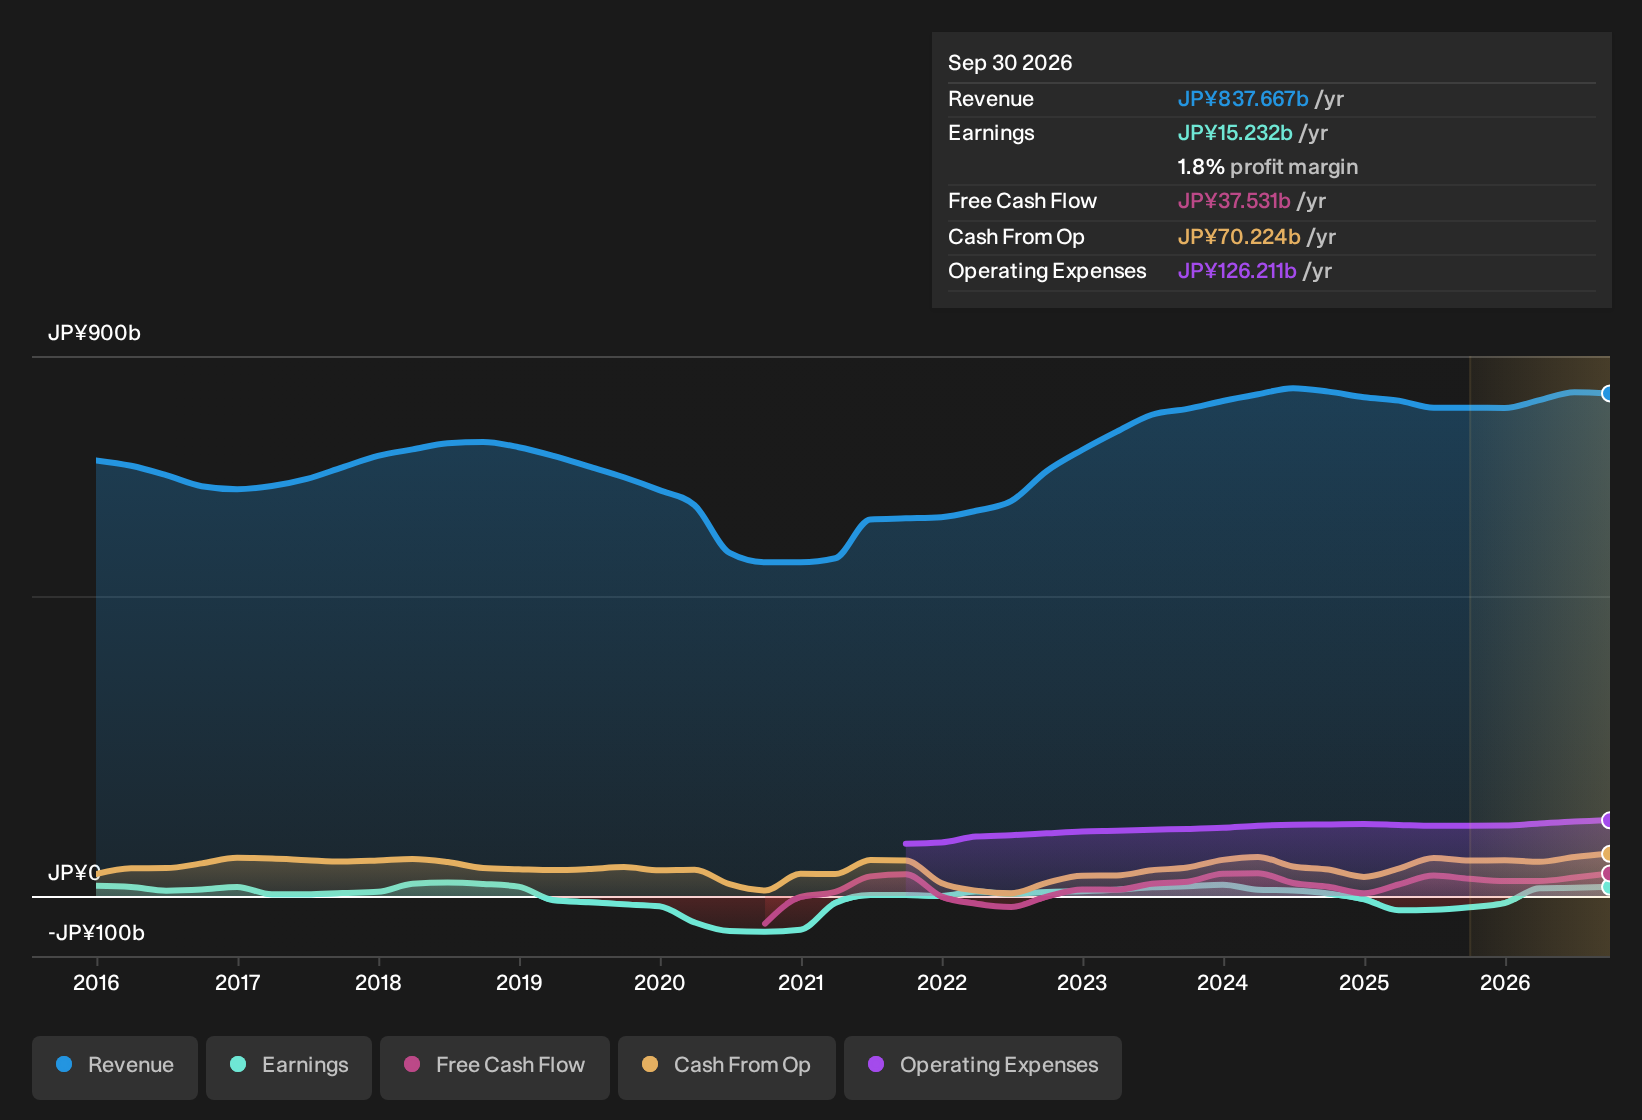
NTN earnings momentum supports cautious optimism
Profit is where the bullish story on NTN really has some backing. Revenue is broadly steady year on year, yet quarterly net income and basic EPS are higher than a year ago. The bigger shift is at the trailing 12 month level, which has moved from a loss to a profit of ¥15,232m. That points to a business that is not just having a one quarter rebound but has built a more solid earnings base for now.
Soft top line keeps NTN risk debate alive
There is still fuel for a more cautious view. Sales are effectively flat, so the current profit run leans heavily on efficiency and clean up rather than evident growth. The share price is also down over the past 3 and 12 months, which suggests investors are not fully convinced this earnings profile is durable. If revenue momentum does not eventually follow the margin repair, the improvement in NTN’s income statement could prove sensitive to any pressure on volumes or pricing.
Are analysts buying the idea that NTN’s cleaner earnings base is finally ahead of the cautious share price reaction, or still on the fence? See the consensus price target analysis for NTN.Hunt For Quiet Balance Sheet Wins
NTN’s earnings shift and muted share price show how accounting progress and market hesitation can coexist. The real opportunity is finding stocks that could be low debt before the market responds.
- Company 1 - 18% below our estimate - builds a larger maintenance-focused sales force so recurring service contracts deepen as customer density rises.
- Company 2 - 35% below our estimate - uses AI tools to shift hiring and local service matching onto automated, higher margin digital processes.
- Company 3 - 45% below our estimate - ties heavier AI and cloud spending directly to subscription security platforms that grow with each additional protected device.
Those are three of them. See all 22 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com