


When a single country’s benchmark turns into a leveraged memory chip trade and erases about $1.1b in value in weeks, investors often look for quieter corners of the market that still tap into the same long-term themes without the same concentration risk. That is where a handful of non Korean advanced packaging and substrate suppliers come in. This article unpacks 3 stocks exposed to that story, and why their link to this news event matters to you now.
The stocks covered below are just a first cut, and the full screen surfaced 52 more non Korean advanced packaging and substrate suppliers with equally compelling stories that do not fit into a short article. To identify and analyze the highest conviction ideas straight away, head into the Non-Korean Advanced Packaging and Substrate Suppliers screener.
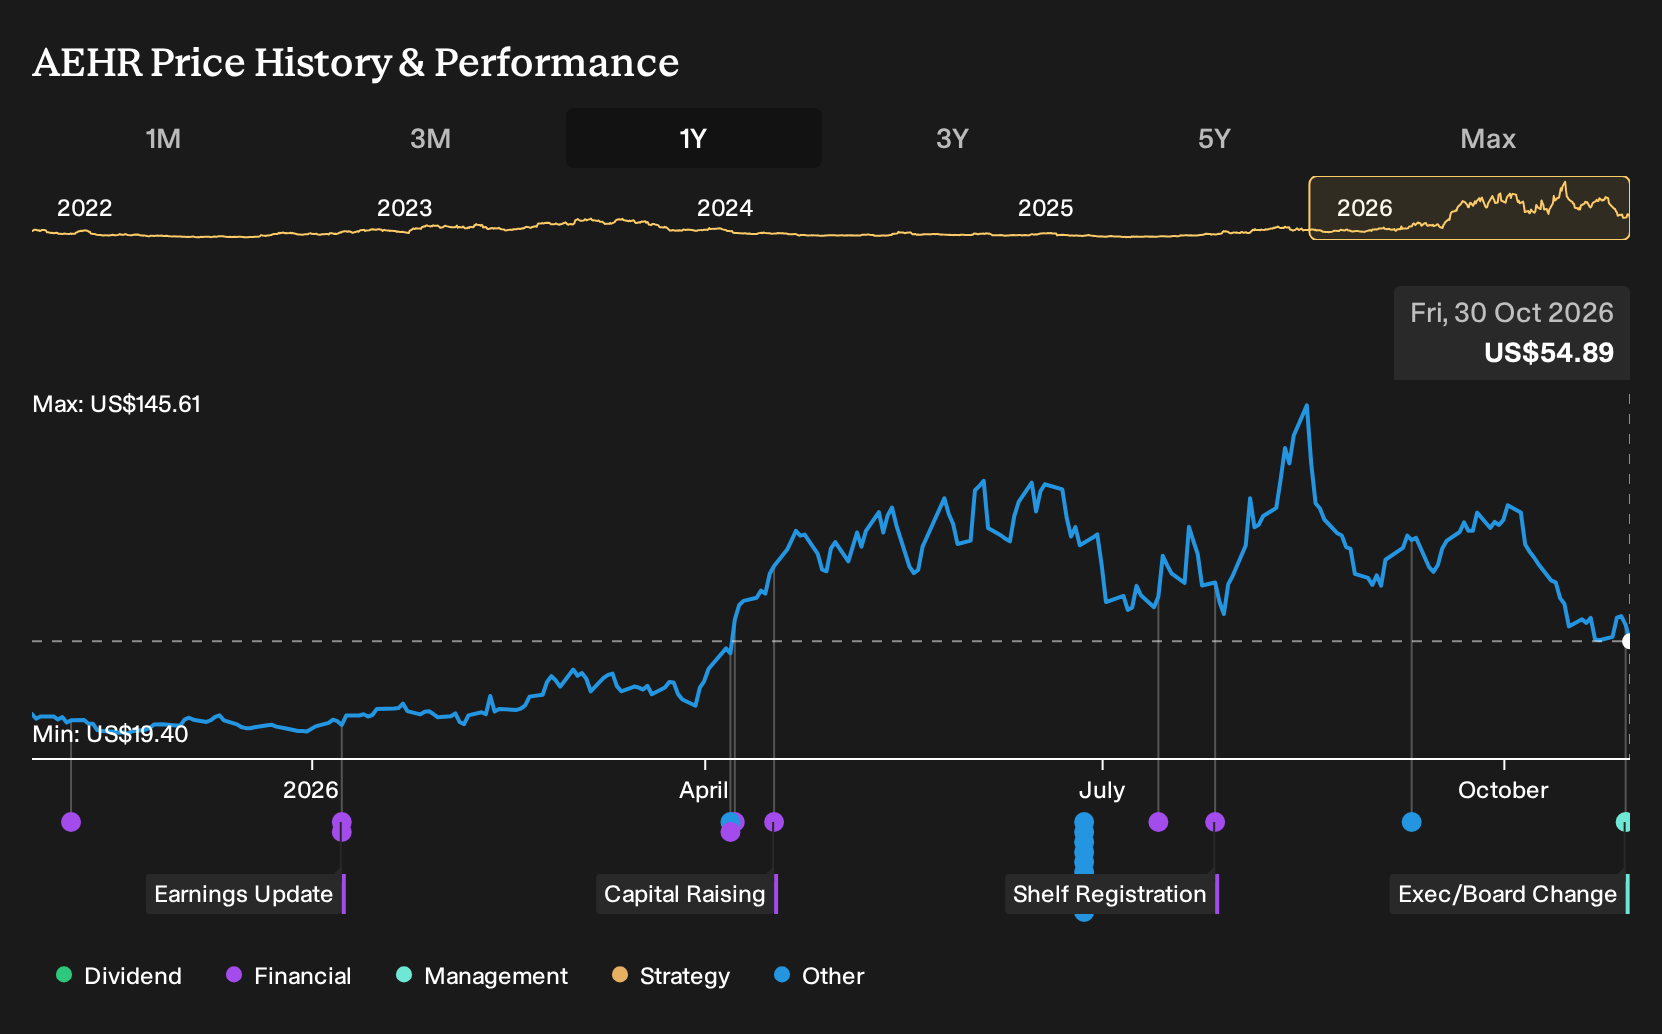
Aehr Test Systems (AEHR)
Overview: Aehr Test Systems supplies wafer and package level burn in and test equipment that screens advanced semiconductors used in AI and data centers.
Operations: Aehr Test Systems generates about US$50 million from advanced test and burn in products, with revenue mainly from Asia, the United States and Europe.
Market Cap: US$1.8b
For investors looking beyond Korean memory giants, Aehr Test Systems provides exposure to the testing gear that supports reliability in advanced AI chips.
"Rising AI processor and data center demand is feeding into Aehr Test Systems' FOX wafer-level and Sonoma package-level platforms."
A key consideration now is how one concentrated exposure shapes the durability of that demand and the margins attached to it.
That concentration question is exactly what the full narrative for Aehr Test Systems unpacks, showing where Aehr Test Systems' AI burn in story could be accelerating or quietly stalling.
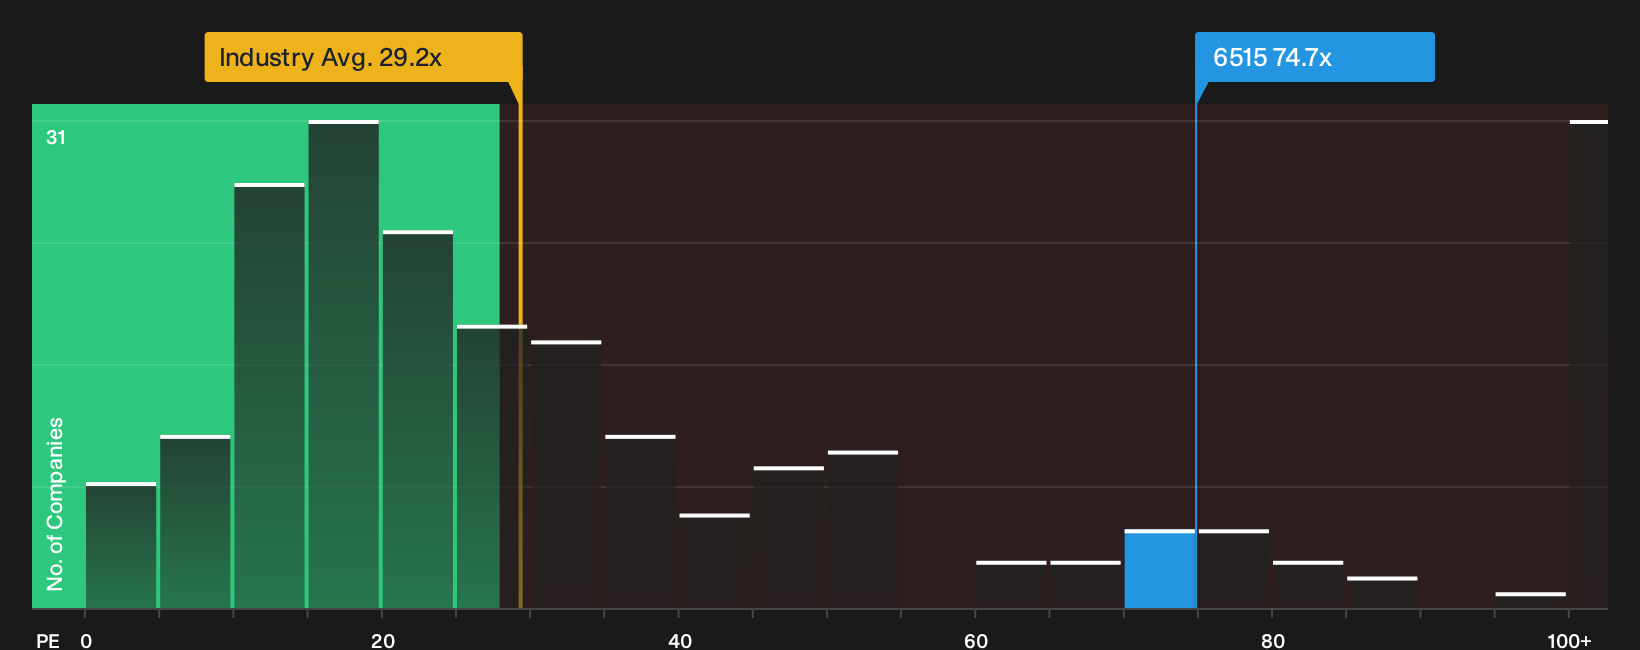
WinWay Technology (TWSE:6515)
Overview: WinWay Technology designs and sells semiconductor test sockets, probe cards and thermal control gear that support advanced chip and package testing worldwide.
Operations: WinWay Technology generates NT$10.5 billion from photoelectric product testing tools, with major revenue from the USA, China, Taiwan and wider Asia.
Market Cap: NT$166.4 billion
For investors looking at the Non Korean Advanced Packaging and Substrate Suppliers theme, WinWay Technology sits in the test interface layer that every high end chip must pass through. It reports strong ROE, rapid earnings expansion and a high P/E that all hinge on what happens when AI and data center test demand meets one unresolved pressure in its funding and earnings quality mix.
That funding and earnings quality mix makes it worth seeing the full 3 key rewards and 2 important warning signs (1 is major!) before AI testing, momentum and valuation potentially pull in different directions.
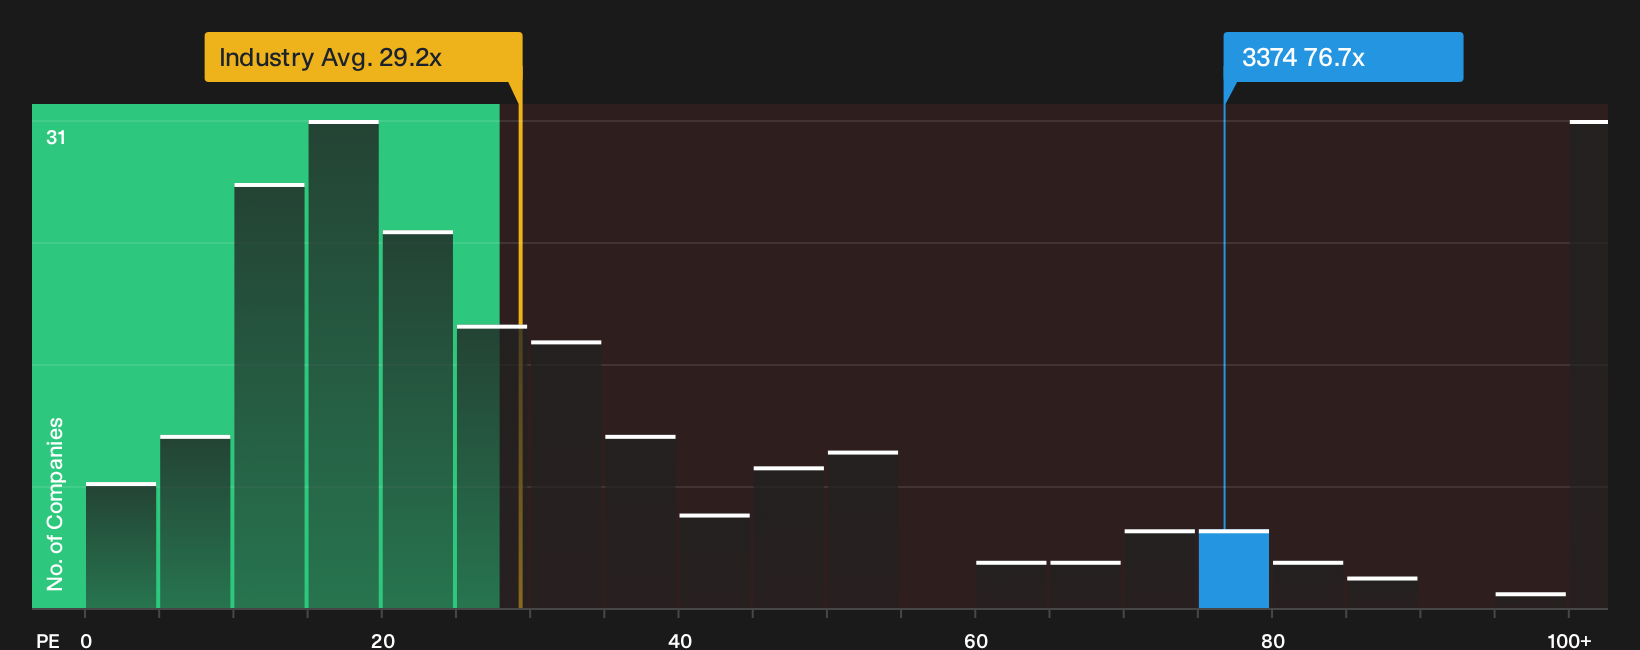
Xintec (TPEX:3374)
Overview: Xintec provides wafer level chip scale packaging and testing for advanced semiconductors used in AI, HBM, sensors and high end logic.
Operations: Xintec generates about NT$8.3 billion from semiconductor equipment and services, with revenue concentrated in Asia and modest sales in Europe and America.
Market Cap: NT$132.4 billion
Xintec offers focused exposure to non Korean advanced packaging for AI and high end chips, supported by earnings and revenue forecasts that are described as being ahead of the broader Taiwan market. The stock may appeal to investors seeking a liquid OSAT style name tied to AI packaging, while future returns could depend on how its premium P/E interacts with a balance sheet that requires significant ongoing funding.
That funding load and premium P/E make the 1 key reward and 2 important warning signs (2 are major!) the quickest way to see whether Xintec’s AI packaging story is accelerating or quietly decoupling.
Seeking Alternatives Before Momentum Flies
Fresh opportunities do not wait around. Breakout stories move fast, sentiment flips, and under the radar for now ideas get caught quickly. Screen new candidates before the crowd and act now.
- Spot smaller companies before momentum headlines catch them. Scan the curated 8 elite penny stocks with strong financials and see which stories still look early rather than already crowded.
- Target resilient payers while yields remain elevated and sentiment is mixed. Use the focused 5 dividend fortresses to sift for businesses aiming to keep distributions flowing.
- Track the build out behind AI instead of only chasing front page tickers. Filter infrastructure exposure with the tailored 54 AI infrastructure stocks and find supporting roles powering that theme.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com