


Why Lakeland Financial’s latest quarter caught the market’s attention
Lakeland Financial (LKFN) just reported third quarter results that combined higher net interest income and net income with a sharp jump in credit costs tied to a single commercial loan workout.
The latest results dropped into a share price that has drifted over the last quarter, with the stock down about 4.5% on a 90 day share price return even as the year to date share price return is up 6.4% and the 1 year total shareholder return is 9%. At around $60.09, recent gains over the past week suggest some momentum is returning after that softer three month patch. At the same time, the mix of stronger earnings and higher net charge offs looks to be reshaping how investors weigh Lakeland Financial’s growth potential against credit risk.
Compare Lakeland Financial’s mix of earnings strength and credit risk with a curated set of banks that screen for resilient balance sheets and fundamentals in our list of solid balance sheet and fundamentals (24 results).
Bulls see Lakeland Financial’s earnings power and balance sheet fundamentals. Bears point to credit costs and a drifting five year return. Which side does the current valuation reward?
Preferred P/E of 13.1x for Lakeland Financial: Is it justified?
Lakeland Financial trades on a P/E of 13.1x, against a last close of $60.09, while our model-based view of fair value suggests a sizable discount to intrinsic worth.
P/E compares what investors pay today for each dollar of earnings. This is a key reference point for a profitable regional bank like Lakeland Financial. At 13.1x, buyers are paying more than the sector average for the company’s current profit stream, despite forecasts that earnings growth of 3.1% per year and revenue growth of 6.3% per year are slower than the wider US market.
The market is assigning a richer tag than the US Banks industry average P/E of 11.3x. This implies investors are accepting a premium valuation for Lakeland Financial. That contrasts with an estimated fair P/E of 10.7x, which suggests the current multiple is higher than a level the market could move toward if sentiment cools or growth expectations stay restrained.
Explore the SWS fair ratio for Lakeland Financial.
Result: Price-to-earnings of 13.1x (OVERVALUED)
Still, the recent uptick in credit costs tied to a single commercial loan, along with a five year total shareholder return that trails shorter term performance, both leave room for the Lakeland Financial narrative to be challenged if credit issues broaden or investor patience shortens.
Find out about the key risks to this Lakeland Financial narrative.
Another view on Lakeland Financial’s value
The P/E discussion presents Lakeland Financial as expensive at 13.1x compared with a fair ratio of 10.7x and an industry average of 11.3x. Our DCF model presents a different perspective. On that view, LKFN at $60.09 trades at a large discount to an estimated future cash flow value of $101.57. Which lens should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
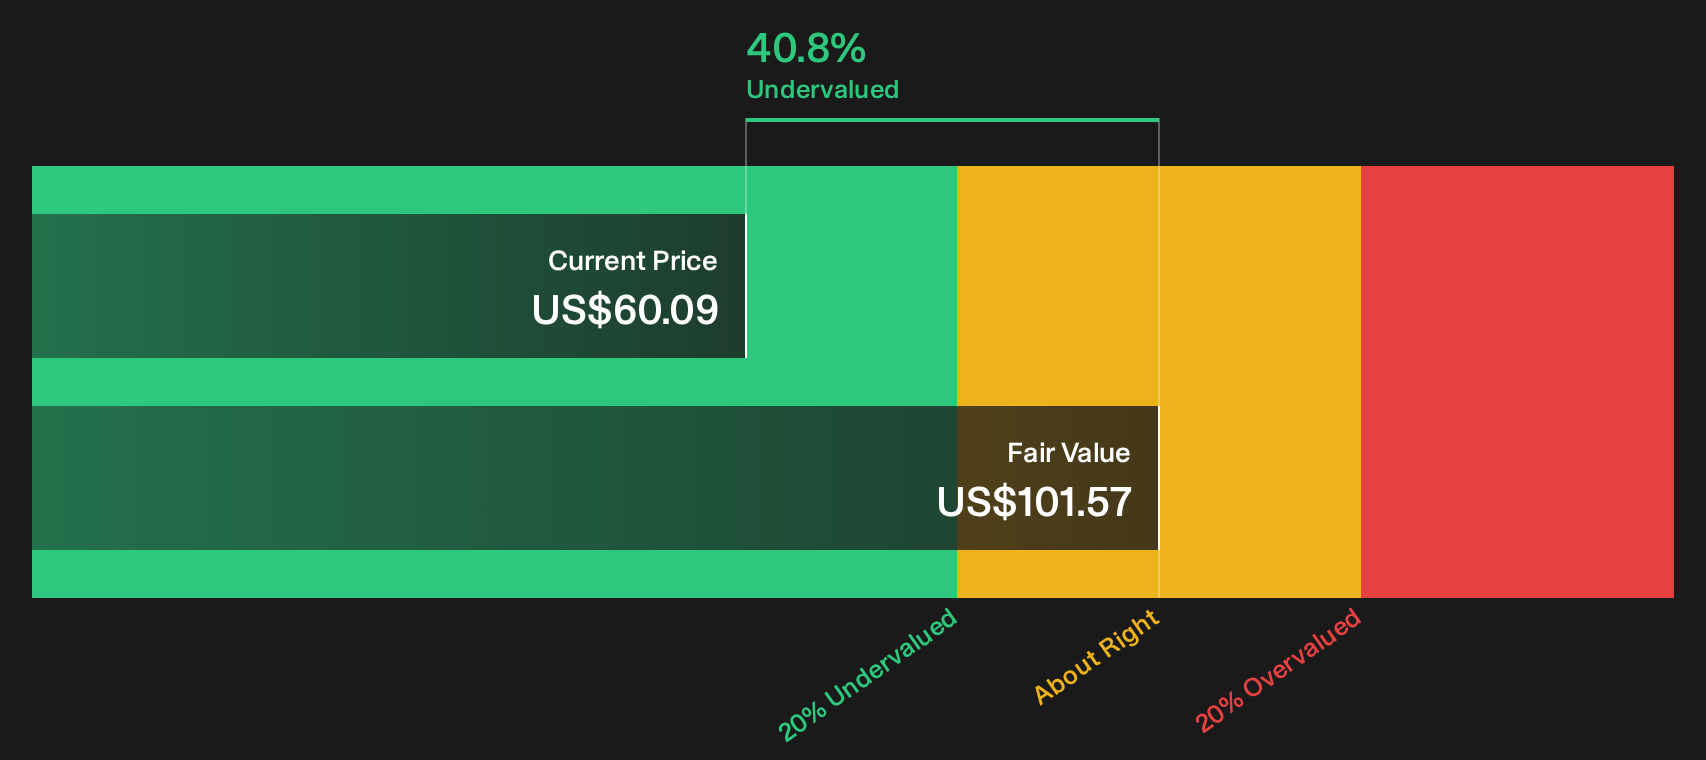
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lakeland Financial for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Lakeland Financial leave you undecided, consider focusing on the available data and acting promptly while market sentiment is still developing. To understand why some investors remain optimistic about its upside potential, review the 3 key rewards
Looking for more Lakeland Financial sized ideas?
If Lakeland Financial has sharpened your focus, do not stop here. Broaden your watchlist with a few targeted sets of ideas that many investors overlook.
- Target potential value opportunities by scanning a focused group of companies that combine quality fundamentals with modest pricing through the 33 high quality undervalued stocks.
- Lock in income ideas by reviewing a concentrated pool of stocks that currently offer sturdy yields and consistent payouts within the 5 dividend fortresses.
- Prioritise resilience by checking companies with stronger balance sheets and fundamentals using the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com