


Why the latest ServisFirst Bancshares earnings matter
ServisFirst Bancshares (SFBS) just posted third quarter results that featured higher net interest income, higher net income and lower net charge offs, a combination that puts profitability and asset quality in clear focus for shareholders.
ServisFirst Bancshares shares closed at US$40.28 after a small pullback on the earnings day, with the 90 day share price return down 10.49% even as the year to date share price return is up 12.17% and the 3 year total shareholder return is 62.64%. This points to longer term momentum contrasting with the softer recent tone as investors reassess risk and growth potential after a strong run.
Scan how ServisFirst Bancshares compares with other financially solid banks by reviewing a hand picked list of solid balance sheet and fundamentals (24 results) that share similar balance sheet strength and fundamentals.
ServisFirst Bancshares has given holders a strong multi year gain, then cooled off over the past quarter, so the real puzzle now is whether most of the upside is already gone or if value still lies ahead.
Most Popular Narrative: 7.8% Overvalued
ServisFirst Bancshares closed at $40.28, while the most followed narrative pegs fair value at $37.37. The story centers on a modest premium that invites closer scrutiny of how management messages performance versus what it actually delivers.
The tone shift is instructive less for what changed than for what did not. Broughton opened July calling the bank “generally pleased with the results,” then circled back in his closing remarks to sharpen that into something less comfortable (“certainly were pleased with the quarter, not satisfied”), reaching for “eight cylinders” as a self-rating device and landing somewhere just under it. October drops the self-assessment language almost entirely. There is no cylinder count, no letter grade, no explicit satisfaction rating. The quarter is described through its outputs, EPS growth, margin, efficiency ratio. Management narrates the business; it stops narrating its own performance relative to potential.
See why 1 investors see ServisFirst Bancshares as 8% overvalued.
Result: Fair Value of $37.37 (OVERVALUED)
Still, two things could quickly flip the ServisFirst Bancshares story: a sharper slowdown in loan demand, or renewed concern around commercial real estate concentration.
Find out about the key risks to this ServisFirst Bancshares narrative.
Another View: ServisFirst Bancshares through a cash flow lens
The narrative community tags ServisFirst Bancshares as 7.8% overvalued at a fair value of $37.37, yet our DCF model points in the opposite direction. Using future cash flows, the SWS DCF model estimates fair value at $66.22, which is well above the current $40.28 share price. That gap raises a simple question for investors. Is sentiment anchoring on recent loan growth commentary while the cash flow math tells a different story?
For a closer look at the mechanics behind that cash flow estimate, Look into how the SWS DCF model arrives at its fair value.
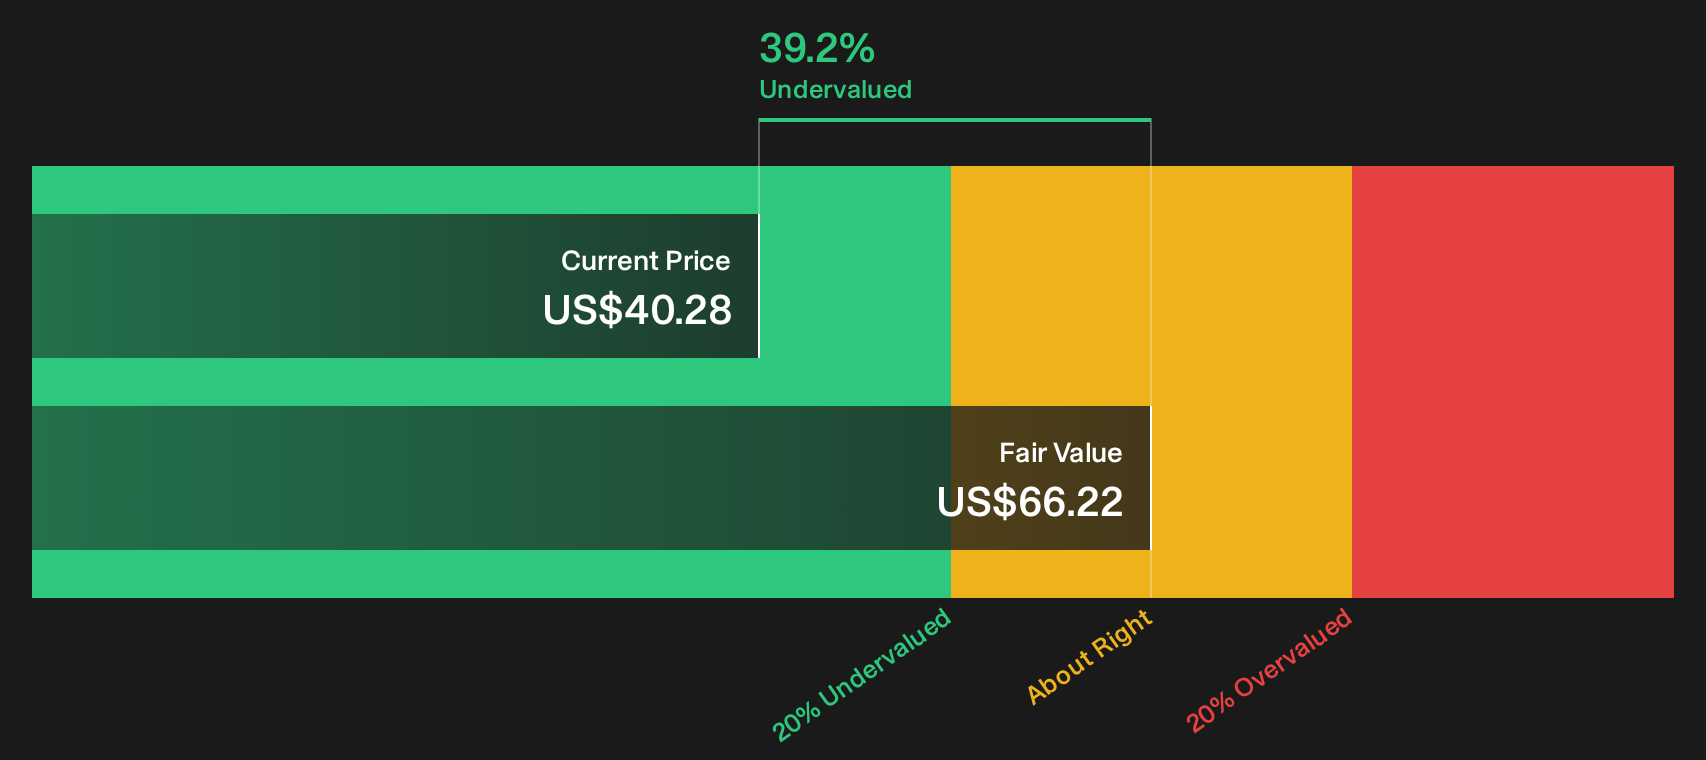
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ServisFirst Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals on ServisFirst Bancshares leave you torn between caution and curiosity, pull up the numbers yourself and pressure test every narrative. Start with the 4 key rewards
Looking for more ServisFirst Bancshares sized opportunities?
You have seen how one bank can split opinion. Now use that same curiosity to hunt for other ideas before the next move passes you by.
- Target potential mispricings by scanning a 33 high quality undervalued stocks that filters for quality businesses trading below estimated worth.
- Build a steadier income stream by reviewing 5 dividend fortresses that combine higher yields with durable balance sheets.
- Reduce portfolio stress by focusing on resilience first using a 29 resilient stocks with low risk scores built around companies with stronger risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com