


- Live Nation Entertainment reported a strong Q2, with revenue rising 9.4% year on year and topping analyst forecasts, supported by nearly 49 million fans attending shows and higher Ticketmaster adjusted operating income.
- Management pointed to all time high deferred revenue linked to upcoming events, which indicates a sizable pipeline of already booked future attendance and ticketing activity.
- We will now assess how Live Nation Entertainment's strong Ticketmaster adjusted operating income in this quarter could influence the broader investment narrative.
Scan how other ticketing and live events stocks are pricing strong attendance trends against expectations by running the hand picked 19 high quality undiscovered gems alongside Live Nation Entertainment.
Live Nation Entertainment Investment Narrative Recap
To own Live Nation Entertainment, you need to be comfortable tying your thesis to physical attendance, Ticketmaster throughput, and sponsorship income. The recent Q2 update supports that story in the near term, with high fan counts and Ticketmaster adjusted operating income helping to fund venue projects and tech spend. The short term swing factor is whether strong deferred revenue converts cleanly into on the day profitability without cost surprises.
The biggest risk still sits with regulation around Ticketmaster. A US$450 million legal accrual, the extended consent decree, and nonexclusive ticketing requirements all create uncertainty. Even with strong Q2 trading, any future remedies or structural changes could affect fee bearing ticket volume, margins, and the economics of new venue and product investments.
Recent disclosure around the extended consent decree and the requirement to support rival ticketing distributors feels most relevant against this quarter. The Q2 Ticketmaster performance shows what the model looks like with current rules. Your call is whether that earnings power is durable if more venues use alternative platforms or demand different economics.
The separate remedies trial with state plaintiffs and the possibility of additional structural measures now sits in the background of every strong quarter. For investors, that puts execution on venue expansion, sponsorship growth, and international ticketing into sharper focus. Strong operational delivery can offset some regulatory friction, but it does not remove that risk.
What The Current Forecasts Assume For Live Nation Entertainment
Live Nation Entertainment's current analyst framework leans heavily on what the next few years of ticketing and venue throughput look like, so it helps to translate the headline projections into plain numbers. Analysts are building their models on revenue growth of 9.4% a year over the next three years, alongside a shift from a loss making margin position of 1.0% today to a positive margin of 2.9% in three years. On the earnings line, the consensus view points to profit of US$996.6 million by 2029 compared with a loss of US$258.0 million today, which is an earnings swing of about US$1.25b. The same set of assumptions underpins a 2029 revenue figure of US$34.4b and implies that by that year Live Nation Entertainment would be on a P/E multiple of 63x those earnings, with analysts working off a discount rate close to 9.8% and modest share count growth of 0.32% a year.
Live Nation Entertainment is effectively being modelled as a business that grows into its current ticketing and venue footprint while lifting profitability. Higher forecast margins rest on live events, Ticketmaster and sponsorship scale showing up in earnings rather than just in top line volume. Any shortfall in fan demand, sponsorship appetite or cost control would make that 2.9% margin target harder to reach and would leave the projected 2029 earnings power exposed to disappointment.
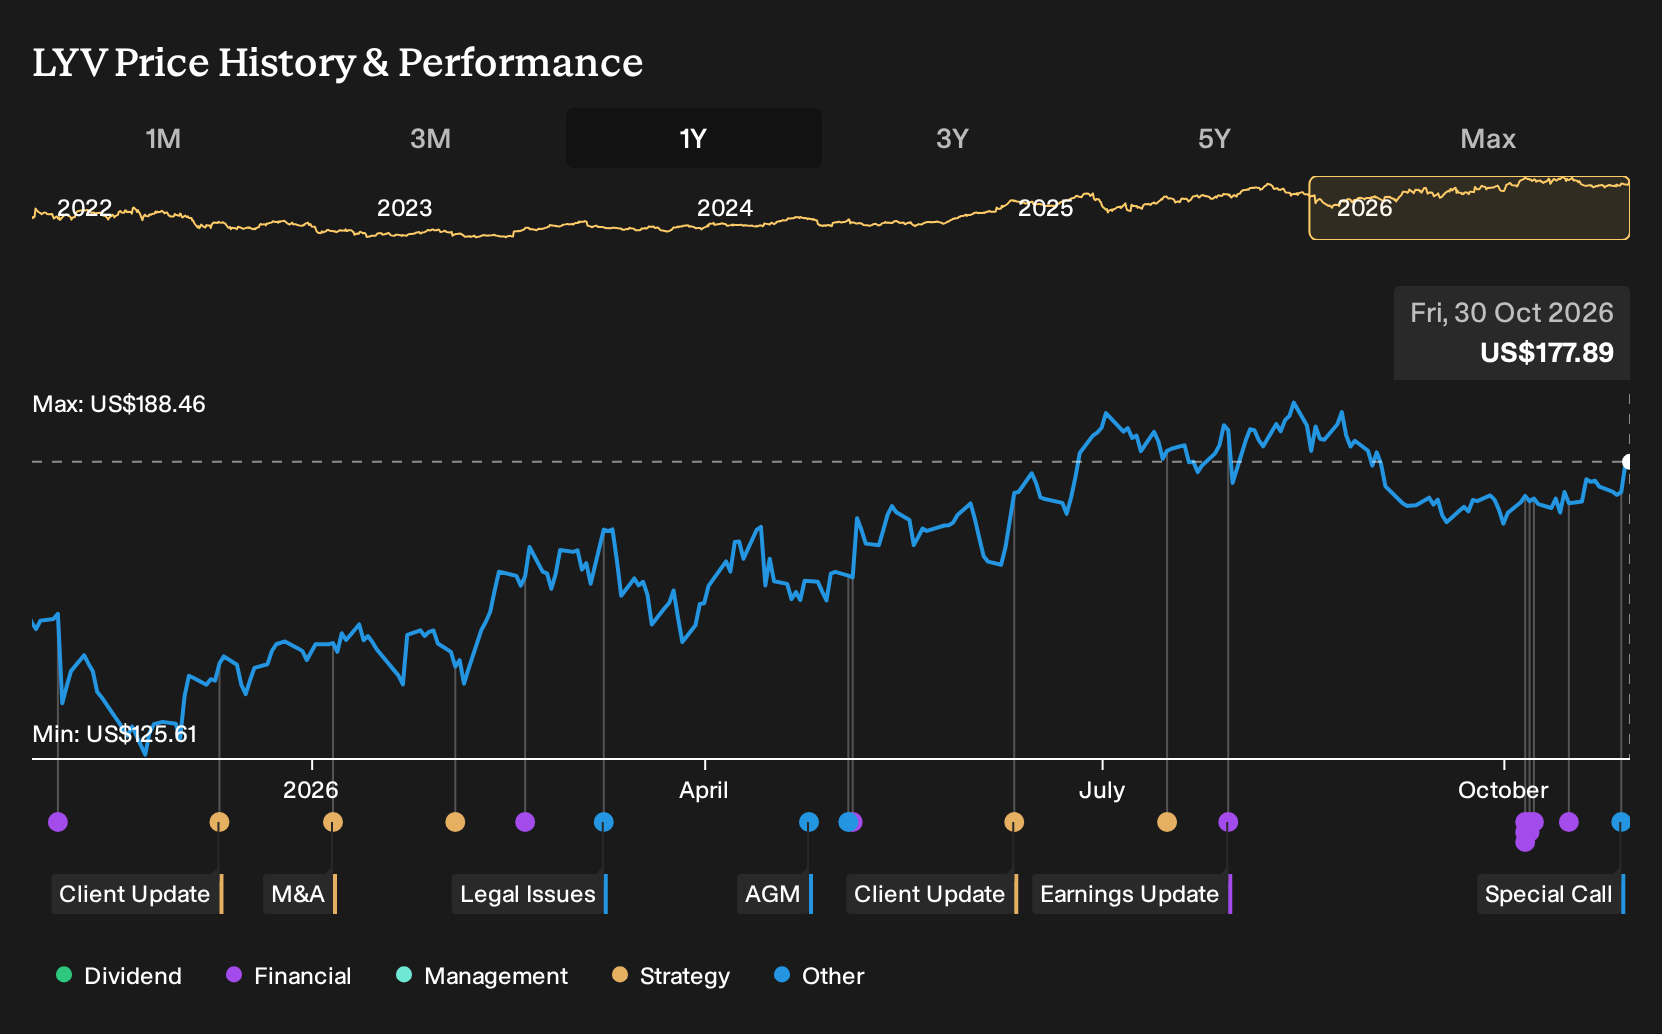
On valuation, the consensus price target of US$201.96, with a bullish end of US$222.0 and a bearish case of US$145.0, maps back to those 2029 revenue and profit expectations. That range indicates the market is still debating how much of the regulatory and legal overhang ultimately bites into Ticketmaster fees, venue economics and sponsorship. The current share price of US$167.12 sits below the average target. The key question for you is whether US$34.4b of revenue and just under US$1.0b of earnings in 2029 feel realistic given your own view of fan attendance, venue mix and regulatory outcomes.
Live Nation Entertainment's narrative projects revenue of US$34.4b and earnings of US$996.6 million by 2029. This setup assumes revenue growth of 9.4% a year and an earnings swing of about US$1.25b from a loss of US$258.0 million today.
Uncover why Live Nation Entertainment's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Community fair values for Live Nation Entertainment from the Simply Wall St Community span roughly US$171.94 to US$201.96 across 2 separate views, so you are seeing a tight cluster rather than wild outliers. Set those opinions against the open regulatory questions around Ticketmaster and you get a reminder that private investors can disagree sharply. Explore several of these alternative viewpoints before leaning on any single narrative.
Explore another Live Nation Entertainment fair value estimate, including one that suggests it could be worth just $171.94.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Live Nation Entertainment research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Live Nation Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Live Nation Entertainment's overall financial health at a glance.
Looking For More Investment Ideas Beyond Live Nation Entertainment?
Once you have a view on Live Nation Entertainment, it can help to widen the lens and compare it with other opportunities that match your risk profile and return goals. The Simply Wall St Screener lets you filter the market by financial strength, income potential, or mispriced quality so you are not relying on a single story.
- If capital preservation ranks high for you, start with companies that score well on stability and financial risk through the 29 resilient stocks with low risk scores.
- For investors focused on durable balance sheets and cleaner fundamentals, scan the list of solid balance sheet and fundamentals (24 results) to see which businesses pass stricter financial health filters.
- If you want to hunt for quality that the wider market might be overlooking, line up potential opportunities with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com