


Pacira BioSciences (PCRX) has drawn attention after a strong recent run, with the share price around $36.40 and returns over the past month and past 3 months both firmly in positive territory.
That recent surge fits into a mixed longer record for Pacira BioSciences, with a 30 day share price return of 45.31% and a year to date gain of 48.81%, while the 1 year total shareholder return of 70.25% contrasts with a 5 year total shareholder return that is still down 37.34%.
Scan Pacira BioSciences alongside other potential breakout opportunities with a curated list of 19 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
Pacira BioSciences has sprinted higher in a short window, which leaves a practical dilemma for new money. Is this a sensible entry point, or does patience for a cheaper setup make more sense once valuation is on the table?
Most Popular Narrative: 8% Overvalued
Pacira BioSciences is trading at $36.40 against a narrative fair value of about $33.57, so the market price is sitting above that modeled estimate while analysts also anchor expectations to the agreed $36.50 Viatris cash offer.
Expansion of the EXPAREL patent estate to 21 listed patents, together with a volume-limited generic settlement that defers significant competition until at least 2030, provides a longer window to convert current utilization into sustained revenue and cash flow.
See why 11 investors see Pacira BioSciences as 8% overvalued.
Result: Fair Value of $33.57 (OVERVALUED)
Still, Pacira BioSciences leans heavily on EXPAREL and ZILRETTA, and any weaker product uptake or less favorable reimbursement after the NOPAIN Act expiry could quickly challenge this narrative.
Find out about the key risks to this Pacira BioSciences narrative.
Another View: Pacira BioSciences Through A P/E Lens
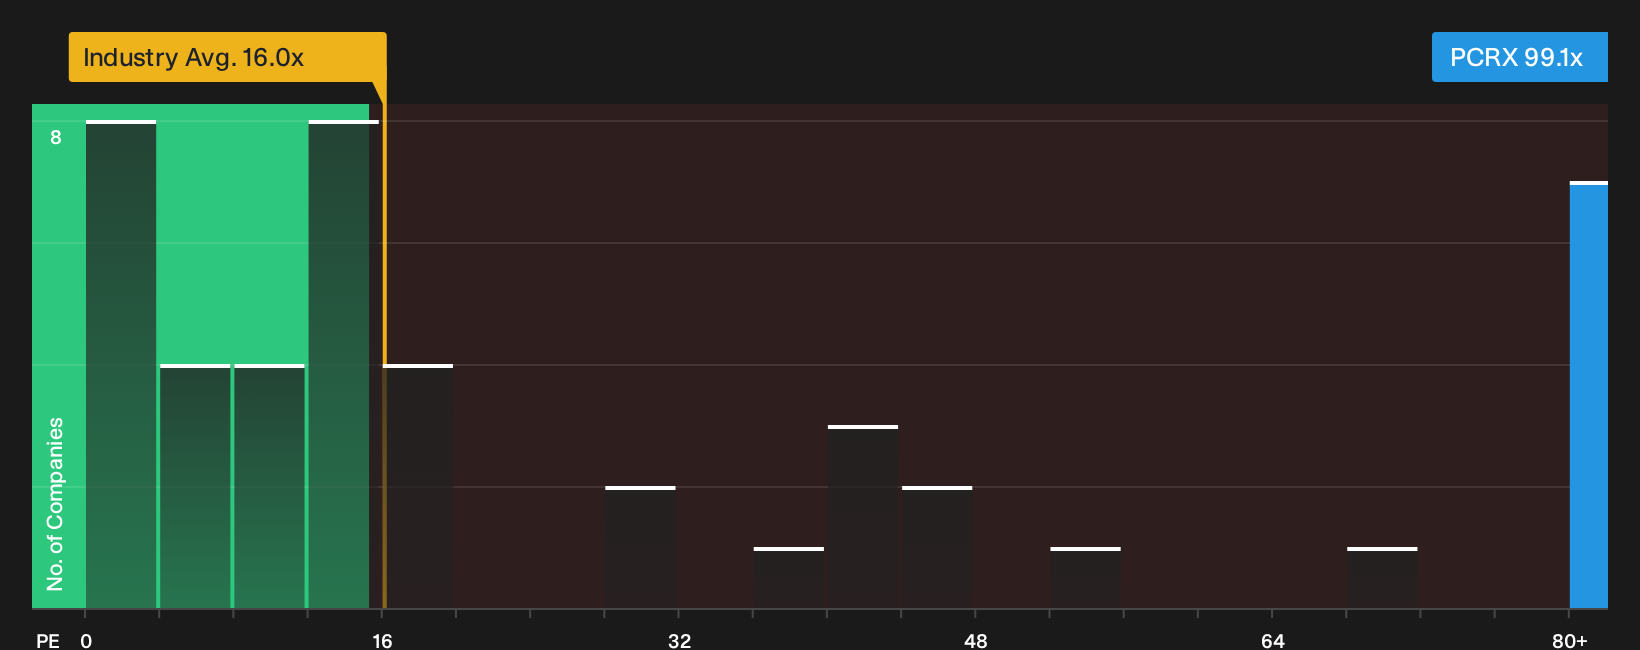
The share price for Pacira BioSciences screens as expensive on earnings. The current P/E of 99.1x sits far above the US Pharmaceuticals average of 15.8x, the peer average of 12.2x and even an estimated fair ratio of 22.7x, which points to meaningful valuation risk if sentiment cools.
That kind of gap can close in more than one way, through stronger profits or through a lower price. Which outcome do you think the market is more likely to lean toward from here, given your own expectations for Pacira BioSciences?
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Pacira BioSciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in Pacira BioSciences so far. With both concerns and bright spots in view, review the data quickly and weigh the 3 key rewards and 3 important warning signs.
Looking for more Pacira BioSciences sized opportunities?
If Pacira BioSciences has sharpened your sense for risk and reward, do not stop here. Broaden your watchlist with ideas that fit your own rules.
- Target stronger value potential by scanning companies that pass tight quality filters and still trade below intrinsic worth through the 33 high quality undervalued stocks.
- Build a steadier income base by hunting for reliable high-yield payers that combine cash returns with resilience using the 5 dividend fortresses.
- Limit unwelcome surprises by focusing on businesses with robust balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com