


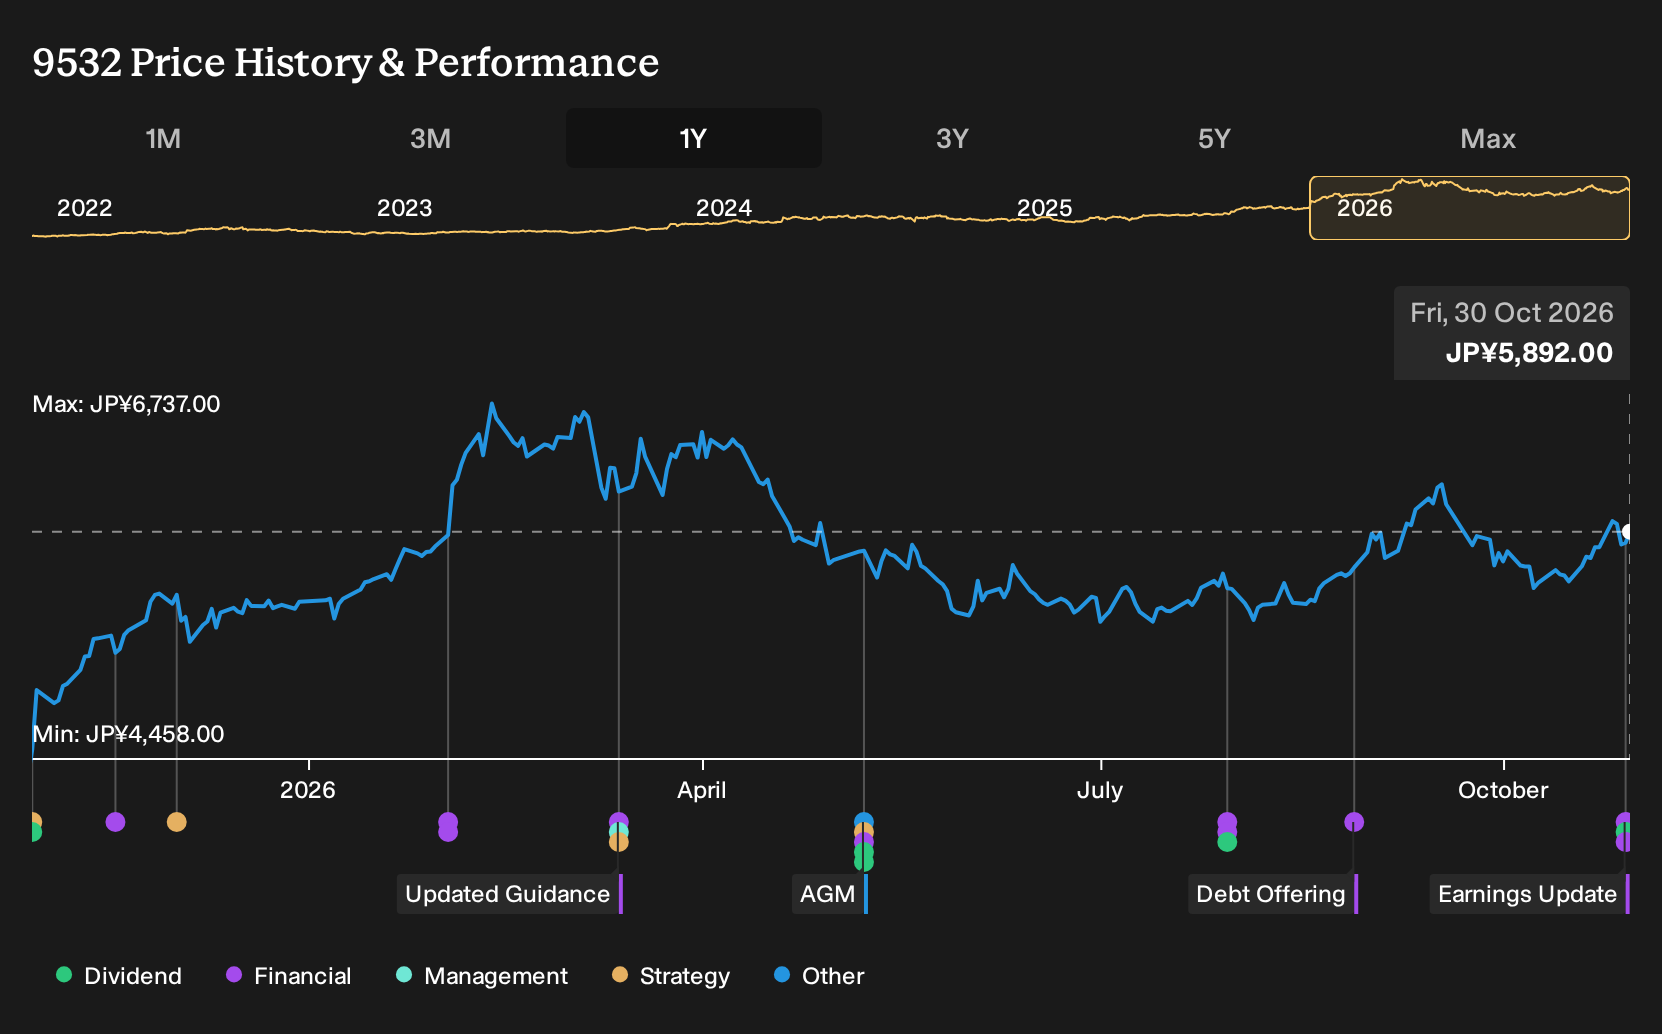
- Osaka Gas revised its forecast for the year ending March 31, 2027, lifting projected net sales to ¥2,254,000m and slightly increasing expected earnings per share guidance while keeping profit targets unchanged. The company also announced a higher interim dividend of ¥65 per share for the second quarter of 2026.
- The combination of higher city gas selling prices under the fuel cost adjustment system and a larger interim dividend signals management’s confidence in Osaka Gas’s cash generation and pricing power, even as profit guidance and half year net income figures remain tightly managed.
- Attention now turns to how Osaka Gas’s investment narrative evolves as higher full year sales guidance reframes the role of pricing power.
Spot similar pricing-power stories to Osaka Gas by scanning our hand picked 14 high quality undervalued stocks that combine resilient cash flows with disciplined balance sheets.
What Is Osaka Gas' Investment Narrative?
To own Osaka Gas, you have to buy into a relatively steady utility model where pricing power matters more than headline growth. The raised net sales guidance tied to city gas pricing and the higher interim dividend both point to confidence in cash generation, even as full year profit targets stay tightly held. In the short term, the real swing factors remain fuel costs, tariff adjustments under the fuel cost system, and how efficiently the business runs its capital intensive network.
Q2 results showed higher sales alongside lower net income and softer margins, so the reaffirmed profit guidance now acts as a line in the sand for execution. Management also runs with a P/E above both peer and fair value estimates, plus a relatively new executive team. This means investors are paying up for the Osaka Gas story while watching how that margin pressure plays out.
That said, sitting underneath the pricing power and dividend story is one awkward pressure point that rarely features in the headline narrative.
There's only one way to know the right time to buy, sell or hold Osaka Gas. Head to Simply Wall St's company report for the latest analysis of Osaka Gas's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Osaka Gas research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Osaka Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Osaka Gas' overall financial health at a glance.
Looking For More Ideas Beyond Osaka Gas?
If the Osaka Gas story has you thinking about pricing power, dividends, or balance sheet strength, it can be useful to widen the lens and compare it with other listed businesses that share similar traits.
- If you want income to play a bigger role in your portfolio, scan through 30 dividend fortresses that focus on higher-yielding payouts backed by substantial operations.
- If capital preservation comes first for you, filter the market using our 24 resilient stocks with low risk scores and see which companies score well on resilience and risk controls.
- If you prefer to cast a wider net for quality at a sensible price, use the curated 71 high quality undiscovered gems that highlight under-the-radar fundamentals the broader market may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com