


FirstSun Capital Bancorp (FSUN) is back in focus after its third quarter 2026 earnings, which combined acquisition driven net interest income, steady per share earnings, a completed buyback tranche, and lower net charge offs.
Recent moves in FirstSun Capital Bancorp’s share price have been relatively soft, with the stock easing over the past week while still showing a positive year to date share price return and a stronger 1 year total shareholder return that points to momentum building over a longer stretch as investors respond to the acquisition integration, completed buyback, and lower net charge offs.
Compare how FirstSun Capital Bancorp’s acquisition fueled earnings stack up against other banks pursuing similar growth by scanning the list of solid balance sheet and fundamentals (24 results).
FirstSun Capital Bancorp has cooled off a bit after a strong 1 year run and a completed buyback, which raises a simple question. Is the better value still ahead, or has most of the easy upside already been claimed in the current price?
Preferred P/E of 30.5x: Is it justified?
Valuation on FirstSun Capital Bancorp is currently framed by a P/E of 30.5x at a last close of $39.17. This sits well above both peer and industry averages and suggests the market is pricing in a stronger earnings profile than many other banks.
The P/E ratio compares what investors are paying for each dollar of earnings. A 30.5x multiple on FSUN means the stock price is many times higher than its recent profit per share. For a regional lender like FirstSun Capital Bancorp, this figure often reflects expectations about future profit recovery, acquisition benefits, or balance sheet resilience rather than just the latest annual result.
That elevated multiple comes with clear context. FSUN is described as expensive versus its peer average P/E of 13.5x and the broader US Banks industry at 11.4x. It also screens rich compared to an estimated fair P/E of 23.8x that its trading level could move toward if sentiment cools or earnings catch up more slowly than implied.
Explore the SWS fair ratio for FirstSun Capital Bancorp.
Result: Price-to-Earnings of 30.5x (OVERVALUED)
Still, the story can break if the benefits from FirstSun Capital Bancorp’s acquisition disappoint, or if the richer US$39 pricing coincides with weaker loan demand and credit quality.
Find out about the key risks to this FirstSun Capital Bancorp narrative.
Another view on FirstSun Capital Bancorp’s value
The high 30.5x P/E paints FirstSun Capital Bancorp as expensive, yet the SWS DCF model points the other way. On that framework, FSUN at $39.17 trades below an estimated future cash flow value of $59.14, which frames the stock as undervalued instead of pricey. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
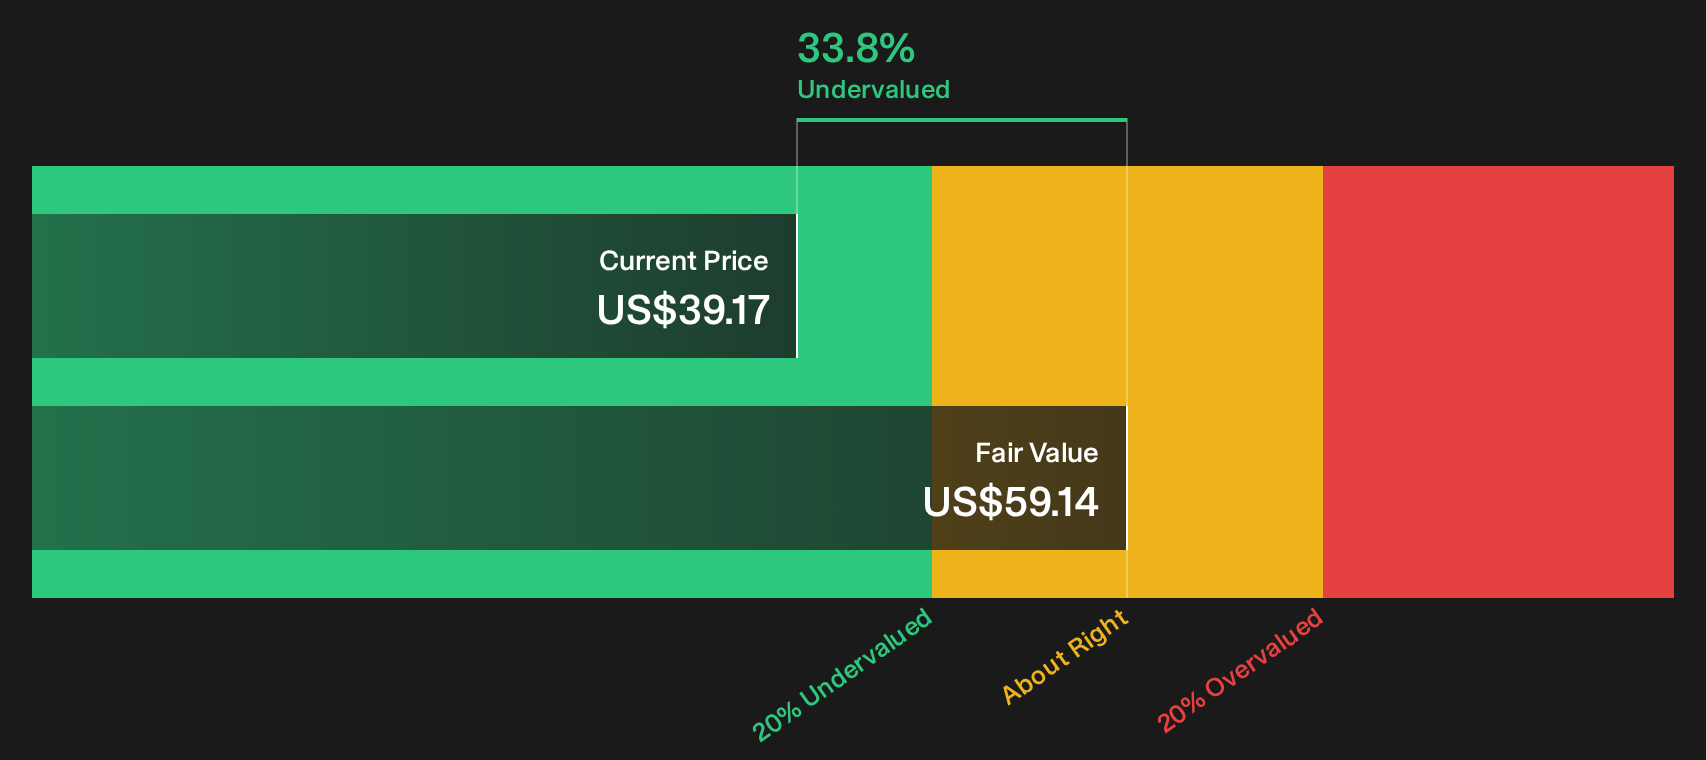
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstSun Capital Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on FirstSun Capital Bancorp’s valuation and outlook make this a judgment call. Move quickly and weigh the upside against the concerns using the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond FirstSun Capital Bancorp?
If FirstSun Capital Bancorp has you thinking more broadly about opportunities, use the Simply Wall St Screener to spot fresh ideas before the crowd does.
- Target value driven opportunities by scanning companies that combine quality fundamentals with attractive pricing using the 33 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses that appear in the 5 dividend fortresses and offer higher yields with a focus on resilience.
- Guard against nasty surprises by focusing on financially robust candidates filtered through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com