


What City Holding’s latest quarter tells investors
City Holding (CHCO) just reported third quarter and nine month results, with steady net interest income, slightly higher earnings per share, and small net charge offs, giving investors fresh numbers to reassess the stock.
City Holding’s latest figures land after a year where the share price has risen 19.02% on a year to date basis. The 1 year total shareholder return of 24.44% and 5 year total shareholder return of 100.30% point to momentum that has built steadily rather than spiking around this quarter’s news.
Scan beyond City Holding’s steady quarter and compare it with a hand picked group of banks and financials that pair earnings resilience with balance sheet strength in our 29 resilient stocks with low risk scores
City Holding appears to be a solid banking franchise with consistent earnings and low net charge-offs. However, its 19% year-to-date share price move raises a different question: Is that stability already fully reflected in today’s valuation?
Price-to-Earnings of 15.5x: Is it justified for City Holding?
On valuation, City Holding trades at a P/E of 15.5x, which sits well above both the US Banks industry and its closest peers, even after a strong share price run.
The P/E ratio links what you pay today to the earnings the bank generates per share. For a regional lender like City Holding, a higher P/E can indicate that investors are willing to pay a premium for earnings quality, balance sheet clarity, or a stable return profile.
City Holding has high quality earnings and has grown profit at 8.4% per year over the past 5 years. Forecasts for earnings and revenue point to growth that is slower than the broader US market. Taken together, this suggests the market may be placing more weight on resilience and consistency than on rapid expansion.
The premium is clear. City Holding’s P/E of 15.5x is materially higher than the US Banks industry at 11.4x and above its peer group at 10.9x. It also exceeds an estimated fair P/E of 10.5x, a level the valuation work suggests the market could move towards if sentiment or expectations cool.
Explore the SWS fair ratio for City Holding.
Result: Price-to-Earnings of 15.5x (OVERVALUED)
Still, the recent share price strength and a market valuation above both peers and an estimated fair P/E leave City Holding exposed if sentiment or earnings quality slip.
Find out about the key risks to this City Holding narrative.
Another view on City Holding’s valuation
The P/E ratio paints City Holding as expensive, yet the SWS DCF model points in the opposite direction. On that framework, the estimated future cash flow value is $219.97 per share versus a recent price of $142.69, which suggests the stock is undervalued by about 35.1%.
Two methods, two very different messages. This leaves investors with a simple question: Which signal deserves more weight for City Holding right now, the earnings multiple or the long term cash flow view?
Look into how the SWS DCF model arrives at its fair value.
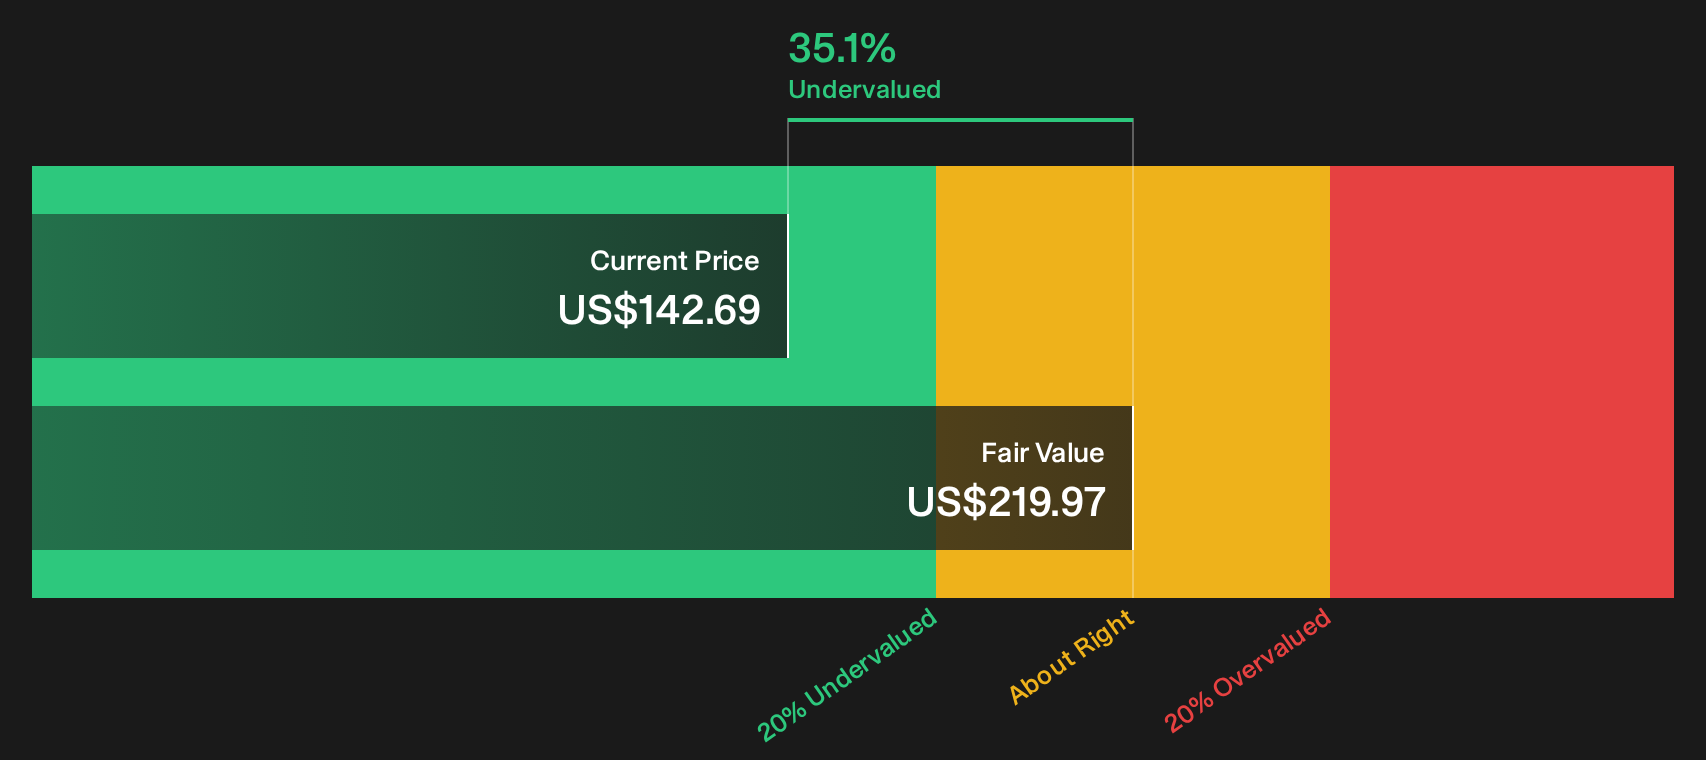
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out City Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the cautious tone here matches your own take on City Holding? Move from reading to testing the numbers yourself by reviewing the 3 key rewards.
Looking for more investment ideas beyond City Holding?
You have fresh context on City Holding. Now use that momentum to compare it with other opportunities so you are not relying on a single banking stock story.
- Target businesses that combine pricing power with a margin of safety by scanning a curated set of quality bargains in the 33 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies with robust payouts and balance sheets using the 5 dividend fortresses.
- Prioritise resilience by filtering for companies with healthier debt levels and funding positions in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com