


Intuitive Machines (LUNR) is back in focus after a rapid refresh in its boardroom, with Michael Blitzer resigning and former National Reconnaissance Office Director Dr. Christopher Scolese stepping in as a Class II director.
Investors have seen Intuitive Machines swing sharply this year, with the share price at US$10.67 after a 1 day drop of 8.65% and a 30 day share price return down 27.46%, even as the 3 year total shareholder return of about 213% points to a very different longer term story.
Scan beyond Intuitive Machines and explore other space and defense opportunities in our hand-picked list of 95 robotics and automation stocks.
The boardroom upgrade, sharp pullback and long term return now collide in one question. Does Intuitive Machines still offer a risk reward skew that justifies fresh money at around US$10.67?
Most Popular Narrative: 64% Undervalued
On the most followed view, Intuitive Machines screens as materially cheaper than a fair value of $29.50, based on a discount rate of 8.23% and long range revenue and margin assumptions that are far more optimistic than current results suggest. That gap between the $10.67 share price and the narrative fair value hinges on how much faith you place in the contract backlog and the move into higher margin services.
Ongoing expansion into high-margin, adjacent markets including lunar surface mobility, in-space networking, reentry vehicles for biopharma and semiconductor transport, and potentially lunar nuclear power creates new scalable, diversified earnings streams with multi-year and multi-billion-dollar revenue potential, helping offset the lumpiness inherent in "success based" mission awards.
See why 160 investors see Intuitive Machines as 64% undervalued.
Result: Fair Value of $29.50 (UNDERVALUED)
Still, Intuitive Machines depends heavily on a few large government contracts, and persistent losses mean any delivery setbacks could quickly erode the undervaluation story.
Find out about the key risks to this Intuitive Machines narrative.
Another View: Intuitive Machines Looks Expensive On Cash Flows
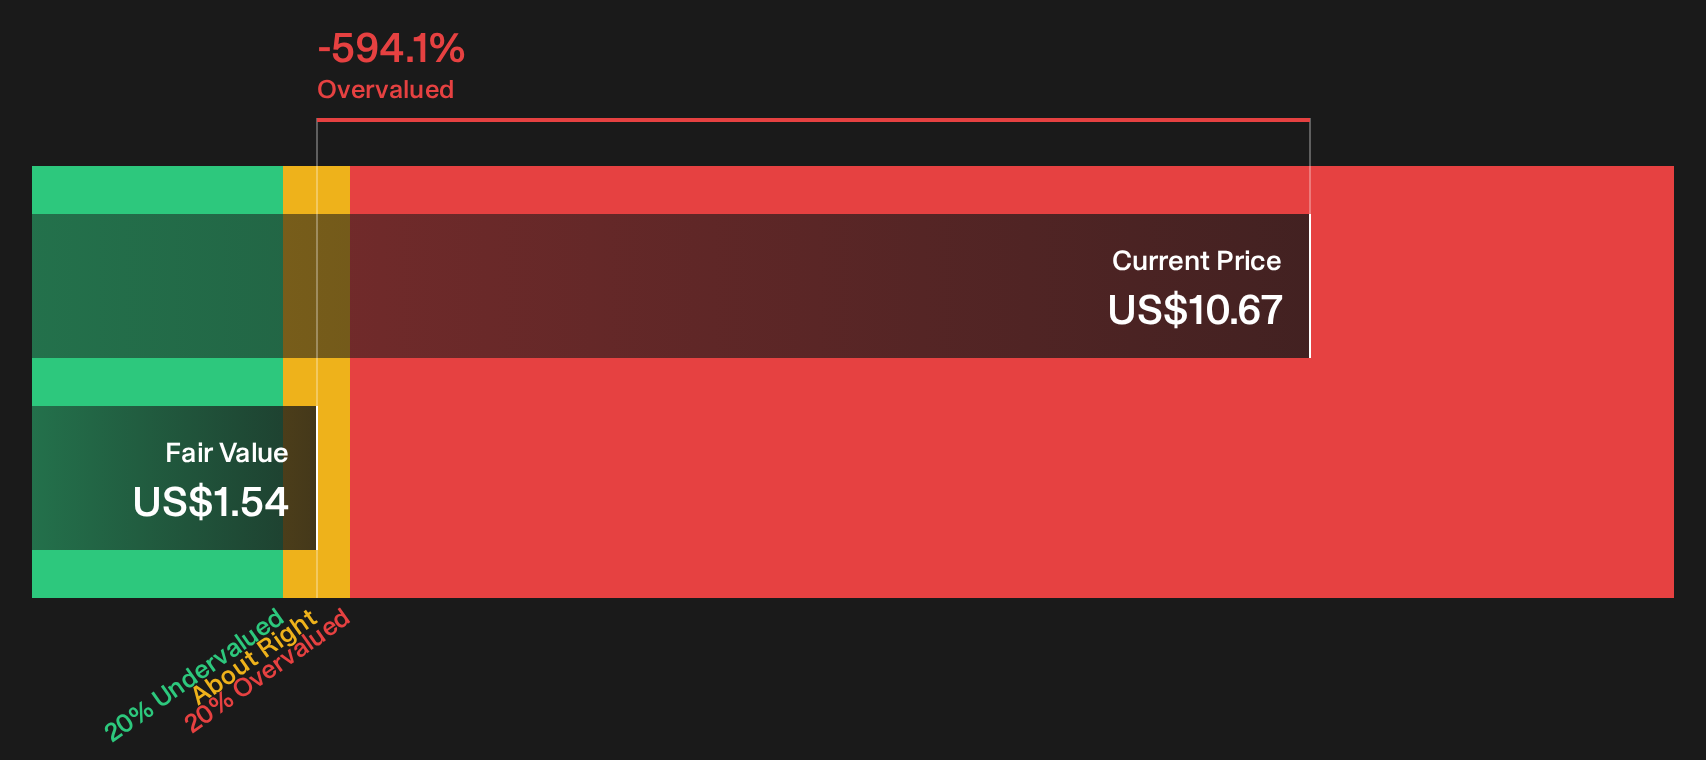
The popular story has Intuitive Machines heavily undervalued against a US$29.50 fair value narrative. Our DCF model points the other way. On that framework, the current US$10.67 share price sits well above an estimated future cash flow value of about US$1.54. Which version of “fair” feels more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Intuitive Machines can feel uncomfortable, so consider acting promptly, reviewing the full dataset, and weighing both the upside and the downside using 1 key reward and 3 important warning signs
Looking for more Intuitive Machines investment ideas?
If Intuitive Machines has your attention, do not stop here. Use the Simply Wall St Screener now to pressure test your next three moves before the crowd does.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (24 results) that can better withstand shocks and funding dry spells.
- Hunt for mispriced opportunities through a curated 19 high quality undiscovered gems that most investors are not watching yet.
- Dial down portfolio stress by focusing on a 29 resilient stocks with low risk scores that keeps volatility and red flags on a tighter leash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com