


- Archer-Daniels-Midland recently entered its latest earnings season with analysts expecting a 77.2% year-over-year earnings jump, supported by forecasts for resilient Ag Services, Oilseeds, and Carbohydrate Solutions, alongside a softer Nutrition contribution.
- The focus now is on how capacity decisions, crush plant investments for biofuels, and any margin commentary could reshape Archer-Daniels-Midland's segment mix and capital allocation priorities.
- We will now look at how Archer-Daniels-Midland's anticipated earnings surge might influence the broader investment narrative around its business mix.
Scan Archer-Daniels-Midland's setup against other potential beneficiaries of stronger earnings and resilient balance sheets with a curated list of list of solid balance sheet and fundamentals (24 results)
Archer-Daniels-Midland Investment Narrative Recap
To own Archer-Daniels-Midland, you need to be comfortable with an agricultural processor that leans heavily on crush economics, ethanol and a higher value Nutrition portfolio, while trying to keep costs in check. The expected earnings jump ties directly into that operating mix. It tests whether strong Ag Services, Oilseeds and Carbohydrate Solutions can still carry softer Nutrition in the near term.
The key near term swing factor is how crush margins and ethanol utilisation hold up against any pressure in liquid sweeteners and trading. The largest immediate risk remains operational and geopolitical shocks that could disrupt grain flows or energy costs, together with any incremental hit from ongoing litigation and compliance issues.
One of the most relevant recent developments for Archer-Daniels-Midland is its plan to spend about US$100 million on phase one debottlenecking at four U.S. crush plants, intended to add more than 700,000 metric tons of capacity by 2028 to 2029. The coming earnings report gives you a checkpoint on how existing crush assets are performing ahead of that extra volume.
Those capacity projects sit alongside expected support from the 45Z production tax credit, which the company has previously guided could contribute around US$250 million in 2026. Together, these factors frame the operational catalyst investors are watching now, while the same report will help you judge whether execution, cost savings progress and governance risks are tracking in line with that longer term plan.
Archer-Daniels-Midland Earnings Setup and Analyst Math
Archer-Daniels-Midland's narrative projects US$89.2b revenue and US$2.3b earnings by 2029. This lines up with analyst expectations for 2.8% yearly revenue growth and an earnings increase of about US$0.5b from US$1.8b today.
Analysts are effectively asking investors to underwrite a steady 2.8% annual top line climb over the next few years for Archer-Daniels-Midland, with profitability edging higher rather than swinging sharply. Profit margins are assumed to move from 2.2% today to 2.5% by 2029, which is a modest shift in percentage terms but meaningful when applied to a revenue base that analysts peg at US$89.2b in that year.
On the earnings side, the consensus view anchors on net profit rising from about US$1.8b currently to roughly US$2.3b by 2029. That US$0.5b step up is tied to both the incremental crush capacity already in the pipeline and the margin uplift that analysts associate with biofuels exposure, ethanol utilisation and a leaner cost structure. It also includes some contribution from the 45Z production tax credit, which Archer-Daniels-Midland has previously outlined as a potential US$250m benefit in 2026.
The valuation element of the story then rests on where the P/E multiple lands against those projected results. For the analyst price target calculations to hold together, Archer-Daniels-Midland would need to trade around 21.3x those 2029 earnings, compared with about 23.2x today. That assumed future multiple still sits above the current 17.3x P/E cited for the broader US Food industry, so the consensus view implicitly assigns a quality or earnings resilience premium to the business.
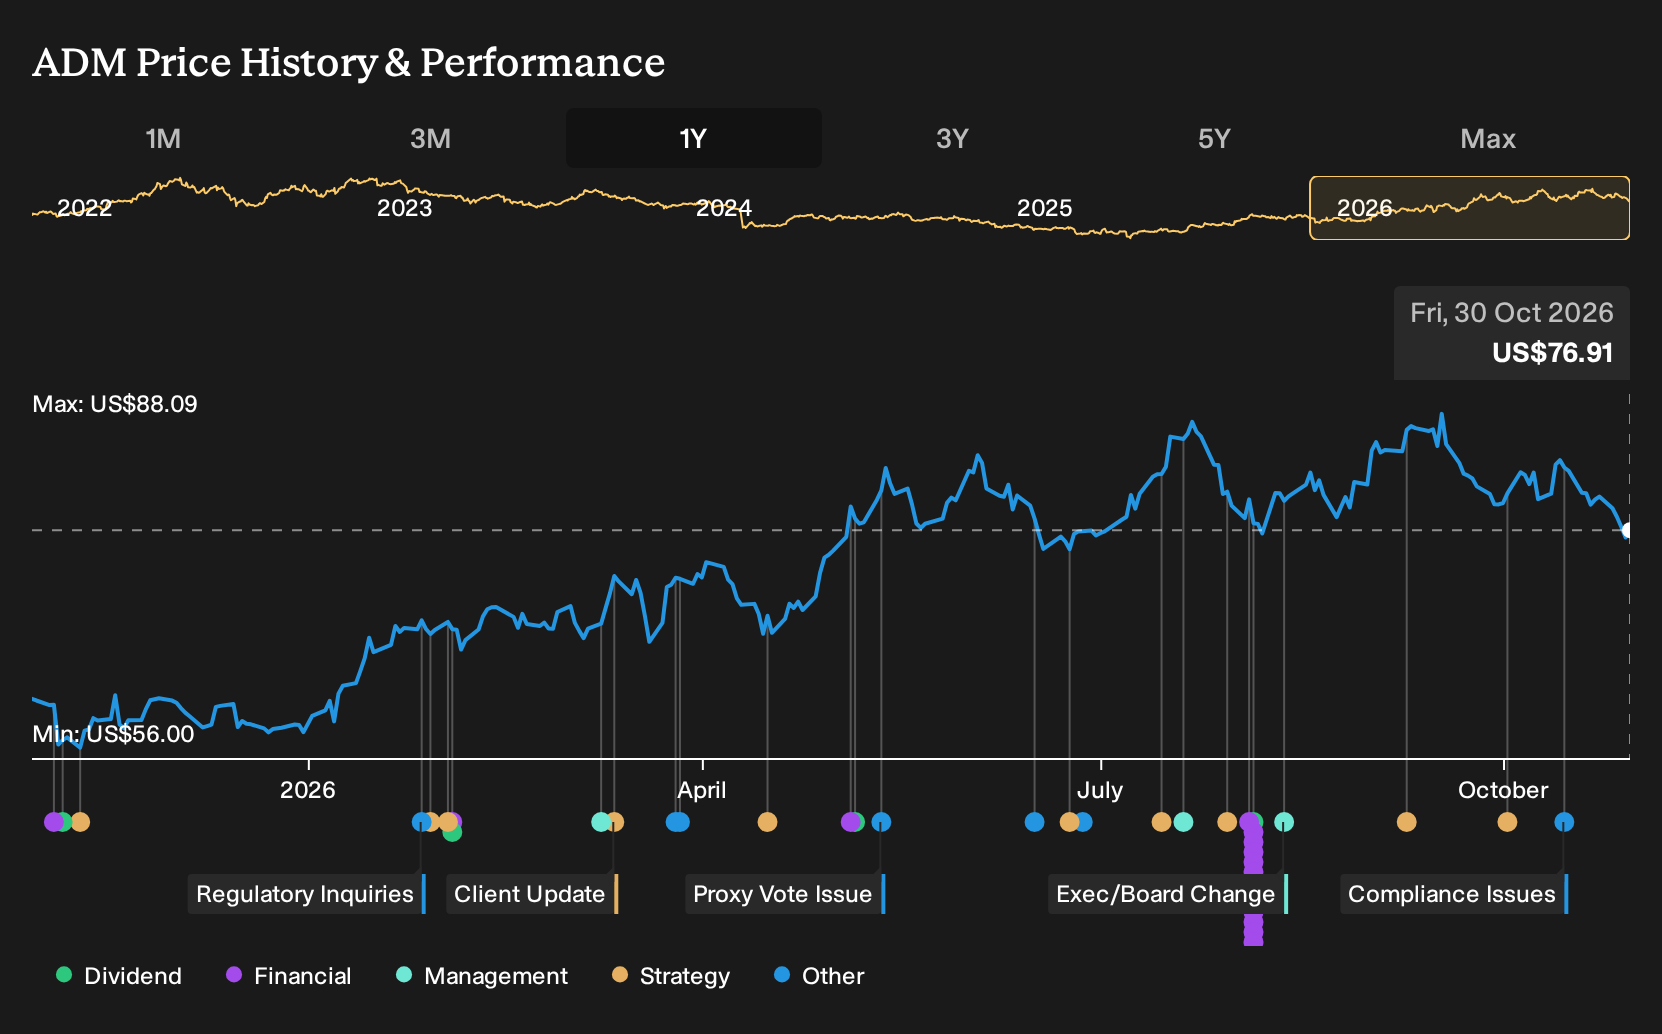
Price targets themselves are clustered but not uniform. The current average sits at US$80.10 per share, with the high forecast at US$95.00 and the low at US$60.00. Against a recent share price of US$85.18, that consensus implies only a 6.3% gap, which suggests analysts on balance see Archer-Daniels-Midland as roughly in line with their fair value framework rather than materially mispriced.
That narrow spread between the market price and the aggregated target turns the spotlight back onto individual assumptions. If an investor expects revenue to compound at 2.8% a year, margins to lift toward 2.5% without major setbacks and earnings to reach US$2.3b while the P/E settles near 21.3x, then the consensus narrative broadly aligns with those views. If there is greater concern around crush cyclicality, Nutrition execution, litigation overhang or geopolitical shocks to grain flows, the same numbers may appear tight, and it may be appropriate to build in more conservative outcomes when assessing Archer-Daniels-Midland today.
Uncover why Archer-Daniels-Midland's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One area where the most optimistic Archer-Daniels-Midland analysts sharply differ is Nutrition. Before this earnings release, that bullish group was pencilling in revenue reaching about US$119.0b and earnings of roughly US$2.6b by 2029, based on a faster rebound in higher margin ingredients. You can now consider whether this new earnings print nudges those expectations up, down, or sideways and explore how far your own view really sits from that upper tier.
Explore 3 other Archer-Daniels-Midland fair value estimates, including one that suggests there could be as much as 51% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Archer-Daniels-Midland research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Archer-Daniels-Midland. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Archer-Daniels-Midland's overall financial health at a glance.
Looking For More Investment Ideas Beyond Archer-Daniels-Midland?
Once you have a view on Archer-Daniels-Midland, it can help to widen the lens and compare it with other opportunities that match different risk and income profiles. The Simply Wall St Screener lets you quickly filter the market so you can focus on businesses that fit your own criteria.
- If resilience and lower volatility matter to you, start with a basket of companies that screen well on stability and risk using the 29 resilient stocks with low risk scores.
- If income is a priority, line up potential payers with robust cash generation by checking out the 5 dividend fortresses.
- If you want to get ahead of the crowd, scan for high quality prospects that are not widely followed through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com