


Q2 2026 earnings put CSW Industrials in focus
CSW Industrials (CSW) moved into the spotlight after reporting second quarter 2026 results on 29 October, with sales of US$361.44 million and net income of US$47.34 million from continuing operations.
The share price of CSW Industrials has eased in recent months, with a 90 day share price return down 16.78% and a 30 day move down 5.46%. Total shareholder return over five years sits at 109.74% and 14.73% over the past year, suggesting longer term holders have still been rewarded despite the latest pullback.
Scan industrial peers showing similar earnings momentum and pullbacks in price by reviewing our hand picked list of 33 high quality undervalued stocks.
After that slide in CSW Industrials despite rising earnings, a near 17% discount to analyst targets and an implied premium to intrinsic value are pulling in opposite directions. Which side does the valuation math support next?
Most Popular Narrative: 19% Undervalued
At the last close of $286.16, the prevailing narrative on CSW Industrials points to a fair value of about $351.86, which implies a material upside gap that investors are weighing against quality and concentration risks.
Growing regulatory drivers around building efficiency, indoor air quality, and refrigerant standards (e.g., American Innovation and Manufacturing Act) are accelerating HVAC maintenance and compliance retrofits. CSWI's strengthened value-added product portfolio and recent acquisitions (like Aspen) directly position the company to capture increased demand, supporting higher revenue growth and potential share gains going forward.
See why 3 investors see CSW Industrials as 19% undervalued.
Result: Fair Value of $351.86 (UNDERVALUED)
Still, the CSW Industrials narrative depends heavily on acquisitions and carries margin pressure risks if tariffs, input costs, or end market demand move in an unfavorable direction.
Find out about the key risks to this CSW Industrials narrative.
Another view on CSW Industrials’ valuation
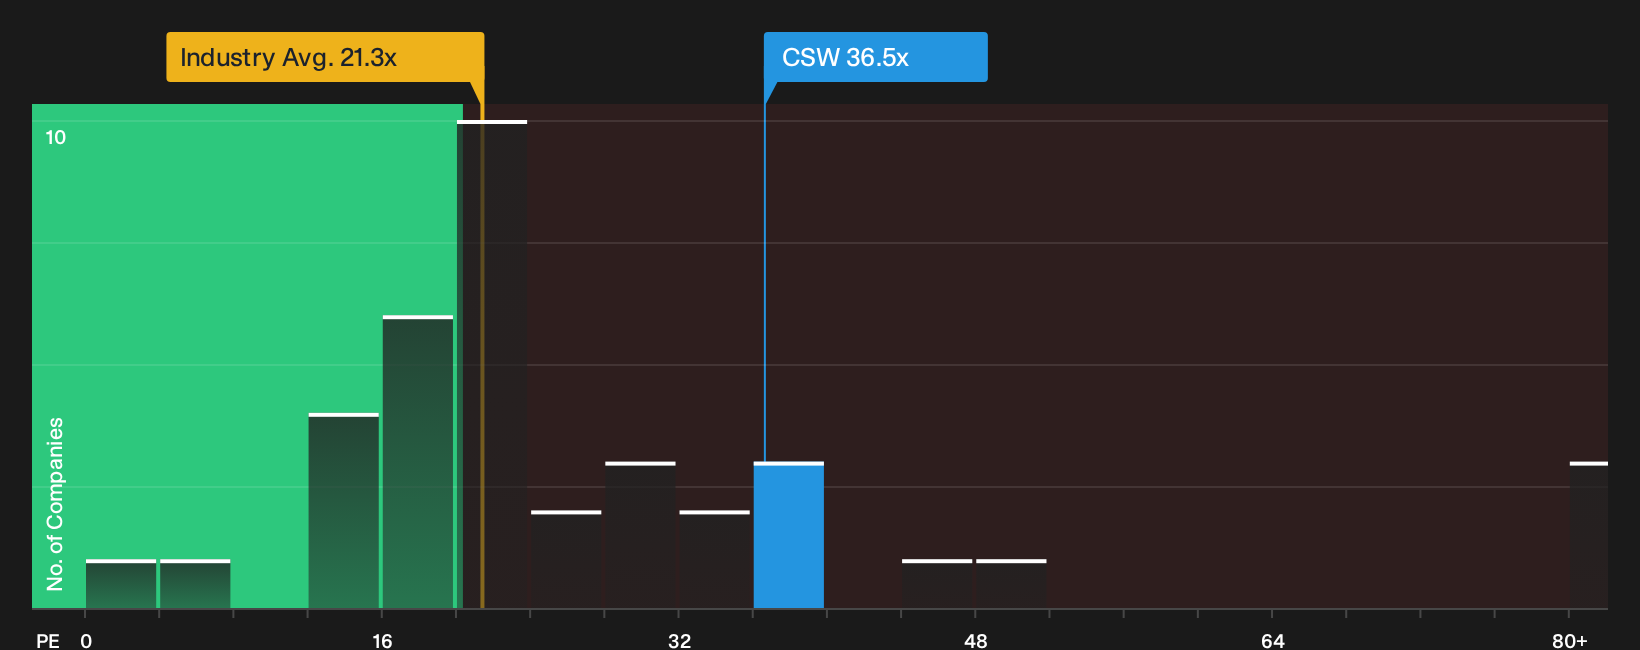
The fair value narrative for CSW Industrials points to upside, yet the market multiple tells a different story. At a P/E of 36.5x, the stock trades well above the US Building industry on 21.3x and above a fair ratio of 21.7x. That gap suggests investors are already paying up heavily for future progress, so it is worth considering how comfortable you are with that kind of valuation stretch if expectations change.
To see how this price tag lines up with earnings power and peer comparisons, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the CSW Industrials story so far. Act while the data is fresh and pressure test it against your own criteria by reviewing 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond CSW Industrials?
If CSW Industrials has sharpened your thinking, do not stop here. Broaden your watchlist with fresh ideas that match how you like to invest.
- Target potential value opportunities before others notice by scanning our 19 high quality undiscovered gems.
- Prioritise resilience and sleep better at night by focusing on a 29 resilient stocks with low risk scores.
- Anchor your portfolio with financially sturdy businesses by reviewing a list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com